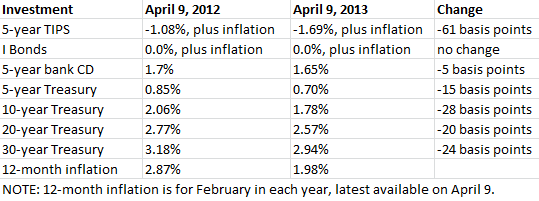TIPS, the suddenly hot topic

Yesterday’s weak auction of a 5-year Treasury Inflation Protected Security, along with last week’s deflationary inflation report, is putting TIPS into the news this week, sometimes in a very negative light. Well, at least it’s nice to see TIPS getting attention.

Remember, just a few weeks ago many of the headlines were strikingly positive, even with TIPS offering pathetically low yields: Why You Should Own TIPS (April 6), State Street Plans Two New TIPS ETFs (March 11), 5 Solid ETF Investment Picks for Retirement (Feb. 28) and TIPS Bond Fund (TIP) Enters Oversold Territory (Jan. 28).

Now we are getting a different view:

‘TIPS are starting to look like Treasurys’ ugly stepsister’: My favorite headline, by far. I love a good headline. This April 18 MarketWatch piece (pre-auction) by Ben Eisen nailed the factors that led to a weak 5-year auction: sagging inflation combined with TIPS’ negative yields to inflation. It’s a bad combination.

“It’s pretty intuitive to think that absence of strong inflationary pressures and a pullback in commodities [would slow] any otherwise perceived demand for TIPs,” said Ian Lyngen, senior rates strategist at CRT Capital Group LLC.

‘Investors Tire of TIPS As Inflation Remains Absent’: Michael Aneiro at Barrons.com (April 17) makes the case that TIPS simply don’t offer enough return to be attractive, and fixed-income investors are moving on.

Investors who have poured money into Treasury inflation-protected securities, or TIPS, however, aren’t really getting the respectable income part of that equation, and they’re getting tired of waiting around for something that isn’t happening …

‘To TIP Or Not To TIP’: Howard Gold at SeekingAlpha.com (April 11) points out that even ultra-cautious economist Robert Shiller thinks stocks might be a better investment than TIPS (for part of your portfolio), given the run-up in TIPS over the last two years.

It’s the negative yield that really bothers Shiller. “Right now, they’re yielding a negative return over the long run, and over the short run it might be even more negative if interest rates go up again,” he said in a recent interview on PBS’s Consuelo Mack WealthTrack.

“Ten-year TIPS are negative substantially, even now to 15 years … which means you’ll get less back in real terms 15 years from now than you have today.”

‘How Much Should Retirees Stake in TIPS?’:  Here’s a thoughtful piece by Christine Benz at Morningstar.com (April 19) that examines the difficulty retirees face in earning income without risk (thank you, Federal Reserve). She remains a fan of TIPS as a hedge against future inflation, especially for retirees, who face heightened risk from inflation.

At first blush it might appear that you’d want all of your fixed-income portfolio in TIPS; that’s the tack embraced by some academics and other investment theorists. After all, if there’s a bond investment that helps offset the corrosive effects of inflation, why would you want to forgo it for one that doesn’t offer that protection? …

The key reason is diversification. … So the answer to the question about how much retirees should hold in TIPS falls somewhere between zero and 100%. But where?
Posted in Investing in TIPS | 1 Comment

5-year TIPS auctions at -1.311%, breaking a string of record lows

A new 5-year Treasury Inflation Protected Security auctioned today with a coupon rate of 0.125% and a yield to maturity of -1.311%, plus inflation. The resulting yield for CUSIP 912828UX6 was  higher than expected, indicating weak demand. Experts had been predicting -1.384% just before the auction, and a similar TIPS that matures in July 2018 closed yesterday on the secondary market with a yield of -1.582%.

Today’s TIPS auction broke a two-year string of 4- or 5-year TIPS issues that set record low yields. Today’s yield of -1.311% is above the record low of -1.496% set in December 2012.

What it cost buyers. The Treasury’s announcement says buyers paid $107.82 per $100 of value for this TIPS, the cost of getting a coupon rate of 0.125% when the actual yield is -1.31%, a boost of 1.435% a year to ‘income.’ That’s still pretty pricey, especially in a time of softening inflation.

Reaction to the auction

On April 5 I posted a blog titled ‘Is buying a 5-year TIPS the most insane move ever?‘ and I guess a lot of people must have agreed. Here are some quotes from the Wall Street Journal report on the auction:

The U.S. Treasury’s sale of $18 billion in five-year inflation-index notes went poorly, drawing the smallest investor interest since October 2008, as inflationary fears faded away. …

The yield was almost seven basis points above the negative 1.380% yield right before the auction results were released, an indication of weak demand.

TIPS are often used by investors to hedge their exposure to commodity prices. “Given the falling commodity prices recently, I think there might be less hedging needs,” said Gennadiy Goldberg, a U.S. strategist with TD Securities. “I have never seen that much struggle for a 5-year TIPS auction.”

From the Bloomberg report:

“TIPS have had a rough time recently with the commodities selloff and renewed fears of deflation,” said Jason Rogan, director of U.S. government trading at Guggenheim Partners LLC, a New York-based brokerage for institutional investors. “People are again more concerned about deflation than they are about inflation. When that occurs, it will affect this market.”

Michael Ashton offers an interesting counter view in his E-pihany blog:

But the main reasons the auction failed were far simpler. Prime among these is that the 5-year TIPS have always had more problems being sold, because people who want inflation protection tend to primarily want long inflation protection. … (T)he 5y TIPS are mainly of interest to (a) indexers and (b) foreign central banks. As such, they are prone to occasional disasters …

Today’s auction might be a signal of a changing trend for TIPS, which have seen steadily declining yields since the Federal Reserve began its aggressive bond-buying programs in mid 2011.

But today certainly wasn’t an Armageddon for TIPS, with the TIP ETF closing at $120.98, down only 0.7% and well above its 52-week low of $118.43. If TIPS are heading into a time of rising yields (which I would love, since I want to be a net buyer of TIPS) there’s still a lot of room to run.

The breakeven rate

Today’s buyers could have purchased a 5-year nominal Treasury paying 0.71%, and so they need to see inflation average 2.02% over the next five years. Not a bad bet, but who is really buying 5-year Treasurys these days? I think a 5-year TIPS compares better with a 5-year insured bank CD, where you can get 1.7% at at least one bank, pushing the breakeven rate up to a more daunting 3.01%.

Posted in Investing in TIPS | 3 Comments

Should TIPS holders root for higher inflation?

Interesting article today in the Wall Street Journal, with the enticing headline: ‘TIPS Investors Rush for Exit.’ Here’s the premise:

A surprise drop in gasoline prices has jolted a corner of the bond market, easing investors’ inflation fears and triggering an exodus from a popular form of Treasury securities. …

The move was triggered by a deterioration in the economic outlook. “People are feeling less positive, so they’re taking that out in inflation expectations,” (said Chris McReynolds, head of U.S. Treasury trading at Barclays).

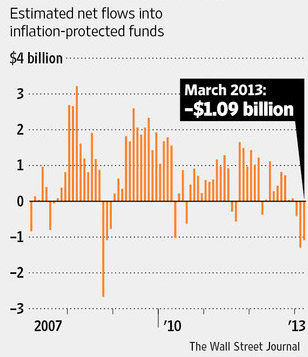
outflowBefore we get to rooting for inflation, let’s look at the article’s premise, that investors are suddenly pouring out of TIPS and into stocks, traditional Treasurys or high-yield bonds. This Wall Street Journal chart does show that TIPS mutual funds have been seeing net outflows for the last three months. These outflows have been fairly rare, and we haven’t seen three consecutive months of outflows since the financial crisis of 2008, when TIPS yields skyrocketed upward, and TIPS values plummeted.

It’s also true that TIPS breakeven rates have been trending down, which was long overdue. As of Tuesday, for example, the nominal 10-year Treasury closed at 1.75%, and the Jan 2023 TIPS closed at -0.699%, putting the breakeven rate at 2.449%, still rather high but a drop from the 2.531% of Jan. 1, 2013.

But overall, I’d say the TIPS market had a pretty mild reaction to this week’s inflation news. In fact, I’d say it was remarkably mild. Here’s a chart of closing prices of the TIP ETF over the last month, versus the AGG (aggregate bond market ETF):

The TIPS market has outperformed the overall bond market in the last month. And look at the volume bar below the chart. Not much action this week. So there’s not much evidence that TIPS investors are fleeing for the hills … yet. Possibly today’s Wall Street Journal article will change that trend. It certainly will get some TIPS investors thinking.

So, do TIPS holders root for higher inflation? The answer is ‘no’ if you have a sensible asset allocation, divided among stocks and fixed-income investments, with maybe 20% of your assets in TIPS and I Bonds. I don’t endorse putting 100% of your investments in TIPS, especially now with yields so low.

TIPS and I Bonds are insurance against inflation, while at the same time providing modest, super-safe returns. Insurance is something better left uncollected. If your house burns down, you don’t say, ‘Wow! I got to collect the insurance!’ Not when your belongings are smoldering in front of you.

TIPS and I Bonds are often described as a hedge against unexpected inflation. If inflation continues in the 1.5% to 3% range, TIPS holders have a boring, safe investment.When the TIPS matures, the investor collects the money and reinvests. That’s how a super-safe investment works.

If inflation suddenly rises to 6% or 7% or 20%, TIPS holders have a safe, protected investment. It won’t be a time to cheer, because your other investments (stocks, bonds and fixed pensions) might be smoldering in front of you.

You’ll never cheer for inflation. But you will be able to say, ‘I did a very smart thing.’

Posted in Inflation, Investing in TIPS | 1 Comment

U.S. inflation fell 0.2% in March

Bureau of Labor Statistics

Today’s tip: Check out the new design of the Bureau of Labor Statistics website at bls.gov. It is user friendly and pretty slick. Impressive for a government site.

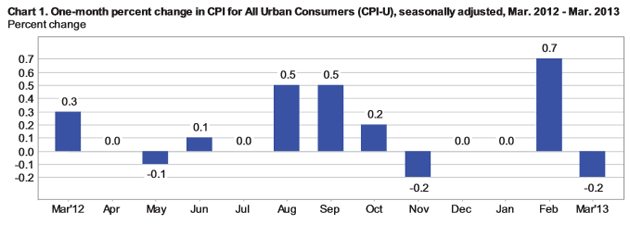
The Bureau of Labor Statistics reported this morning that ‘headline’ inflation – the Consumer Price Index for All Urban Consumers (CPI-U) – fell 0.2% in March on a seasonally-adjusted basis, partly reversing the sharp 0.7% increase in February.

That means inflation over the last 12 months was just 1.5%, down from 2.0% in February.

Read the full CPI report.

The decline, which was deeper than expected, was primarily caused by a 4.4% drop in gasoline prices. The energy index fell 2.6 percent in March after a 5.4 percent increase in February. The food index was unchanged in March. Also interesting is a 1% drop in apparel, which could possibly be linked to the payroll tax increase that took effect in 2013.

Headline inflation is important, because it is the number (minus seasonal adjustment) used to adjust the principal on TIPS holdings and to set the future inflation-adjustment interest rates on I Bonds.

Without the seasonal adjustment, CPI-U rose 0.3% in March, but the number for the last 12 months remains at 1.5%. As a side note, the 5-year TIPS being auctioned Thursday will go off with a yield to maturity of at least -1.5%, meaning a zero return or less in the current inflation environment.

In the last half year, inflation has increased only about 0.5%. Here’s a summary of month-by-month changes in headline inflation:

Month-to-month inflation‘Core inflation,’ which strips out food and energy and is closely watched by the Federal Reserve, increased 0.1% in March and stands at 1.9% for the last 12 months, below the Fed’s implicit ‘danger’ level of 2.5%.

Curious about ‘chained’ CPI, which is being discussed as a new index to lower federal spending? It increased 1.4 percent over the last 12 months. For the month, the index increased 0.2 percent on a not seasonally adjusted basis.

And for the future? Here is some commentary from the Associated Press report:

The figures come a day after the prices of many commodities, including copper and oil, fell in response to a report of slower than expected growth in China. That suggests U.S. consumer prices will likely stay low in the coming months.

The drop “marks the start of what will likely turn out to be a string of declines stretching into the summer,” Paul Ashworth, an economist at Capital Economics, said in a note to clients.

Posted in Inflation | 1 Comment

Buying a 5-year TIPS? The trend is working against you

The U.S. Treasury on Thursday issued its formal announcement for the April 18, 2013, auction of a new 5-year Treasury Inflation-Protected Security.

This will be CUSIP 912828UX6, and although the coupon rate will be set at auction, we can say with 100% certainty that it will be 0.125%, the lowest rate the Treasury allows on TIPS. The yield to maturity is likely to be somewhere near -1.69%, maybe a bit higher.

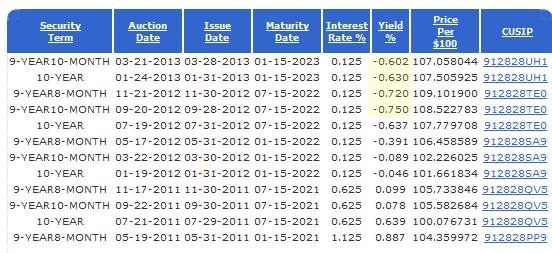
Although several consecutive 10-year TIPS auctions have failed to set record low yields, this 5-year TIPS will probably blow out the record low for any 4- to 5-year TIPS, -1.496% for an auction last December. Here is a history of 5-year TIPS auctions running back to 2005:

5 -year TIPS auctionsI’ve highlighted the last three auctions to show the trend of a sharply declining yield, and that trend appears likely to continue in Thursday’s auction. Compare that with the reverse trend in 10-year TIPS:

10-year TIPSSo 5-year TIPS must have some sort of magical appeal? Why are they so desirable? I can think of only one reason: There has been a surge of money pouring into shorter-term TIPS funds and this has expanded demand for TIPS of 5-year maturities or less.

For the small investor, maybe those short-term TIPS funds make sense, although they offer very little, if any, return. But buying this new 5-year TIPS will have you fighting a trend – one that’s working against you. To demonstrate this, I will compare this year’s TIPS auction versus last year’s (April 2012) and other similar investments:

5-year TIPS, 2013 vs. 2012The key here is that the yield to maturity on a 5-year TIPS has dropped 61 basis points, double, triple or quadruple the decline for nominal Treasuries. An insured 5-year bank CD has barely budged. I Bonds, of course, still pay inflation minus nothing. And this has happened at a time of declining inflation, creating a double whammy for TIPS buyers.

But what about the ‘real’ return, after inflation? Isn’t that where a TIPS should shine? This chart shows the real return buyers could expect at the time of purchase, 2012 vs. 2013:

Real returnBecause inflation has declined and the TIPS yield has also dropped, the current TIPS yield of -1.69% is dramatically more expensive than similar investments, all of which are yielding a better return against current inflation, compared with last year. Except for I Bonds, of course, which pay inflation no matter what.

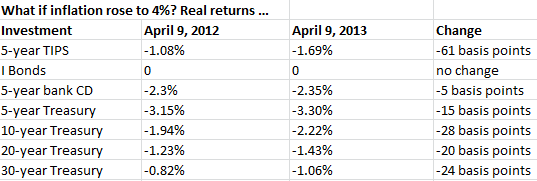
OK, let’s say you believe the current rate of inflation can’t continue, and you believe it is going much higher. (The current trend in housing prices supports that theory, but the weak job market counters it.) Let’s say inflation doubles, to 4%. How would this 5-year TIPS perform, versus 2012 and similar investments?

4 percent inflationHere’s a manta for TIPS buyers: The yield to maturity is the real return. When you buy a TIPS with a yield of -1.69%, you are getting an after-inflation return of -1.69%, no matter how high inflation goes. However, this chart shows that in 2013, a 5-year TIPS provides a better real return at 4% inflation than similar investments, except the stalwart I Bond, which is clearly superior.

It also shows that a 5-year TIPS has gotten much more costly than similar investments in the last year.

That is the trend buyers at next week’s auction are fighting.

Posted in Investing in TIPS | Leave a comment