
Yes, it has been a bad year for Treasury Inflation-Protected Securities, but as I will explain, it all depends on how you define ‘bad.’ As a buy and hold-to-maturity investor in TIPS, with a ladder crossing many years of maturities, I don’t really worry much about market swings after I make my purchase.
The Wall Street Journal last week gave an article about TIPS fairly major play: ‘TIPS Poised for Worst Year Ever.‘ The article pointed out that TIPS underperformed traditional Treasuries this year, mainly because TIPS were overbought through 2012, pushing yields negative to inflation. And then, inflation fizzled:
For years, TIPS owners accepted negative real yields, expecting they’ll get compensated down the line when inflation rises. Payments on TIPS increase as the consumer-price index rises. Now, not only is realized inflation in the economy still tepid, but the Fed’s inflation-inducing stimulus program looks set to wind down without having stirred up much inflation at all.
Quite frankly TIPS got way too expensive from July 2011 to about April 2013. I simply stopped buying during that time, and I got completely out of TIPS mutual funds, way back in 2011 (too early, I admit). But that changed this year, as yields improved:
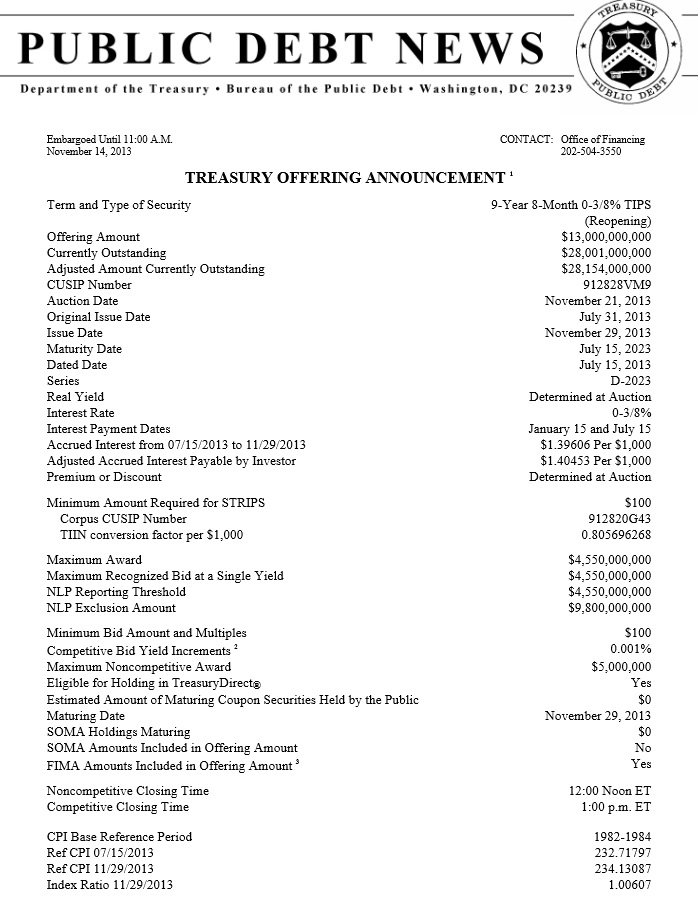
- I again started buying TIPS at auction – cautiously in the May, July and September auctions, mainly to fill holes in my TIPS ladder caused by two years without purchases.
- On June 21, I reestablished small positions in the Vanguard and Fidelity TIPS funds, and I am dollar-cost averaging contributions in IRA accounts. On June 21, the TIP ETF stood at $110.44 and today it trades at $111.19, so most of the damage was done by June 2013.
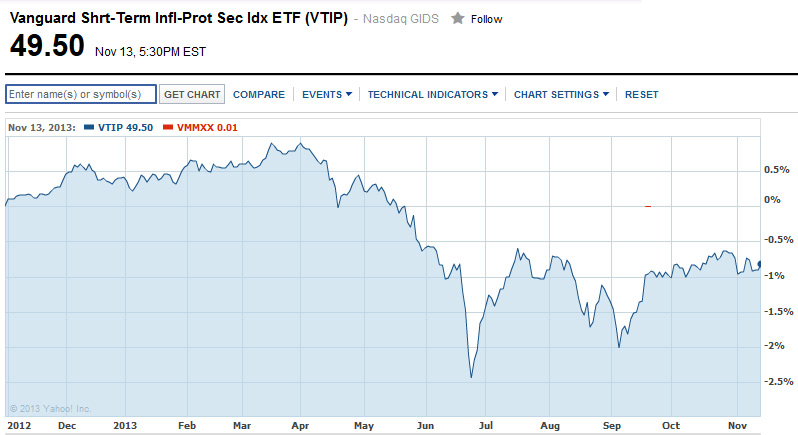
TIPS mutual funds, especially, have been hard hit, with the TIP ETF dropping 8.5% so far in 2013. Yields started rising in the summer, as fears rose that the Federal Reserve would stop its bond-buying stimulus program. Back on June 9, when the TIP ETF stood at $114.64 and the 10-year Treasury was yielding 2.22%, I wrote this (call me psychic):
My theory is that the 10-year Treasury could rise to about 2.75% by the end of the year, and if it does, that would set the 10-year TIPS yield at about 0.5%, about 47 basis points higher than it is today. If that happens, the TIP ETF would fall another 4%, or maybe to the $111 to $110 range. At that point, I might be a buyer.
And voila, within a month the 10-year Treasury yield hit 2.70% and the TIP ETF dropped to $110.50, and I, the psychic, became a cautious buyer.
TIPS mutual funds hit a low-water mark on Sept. 5, when the 10-year TIPS yield soared to 0.92%. Today it stands at 0.66%, 26 basis points lower. I expect that next year, if the economy improves and the Federal Reserve abandons bond buying, the 10-year TIPS yield will begin to ‘normalize,’ possibly somewhere around 1.5% with a traditional Treasury yielding 3.8%.
I laid out my logic in this post back in August: How high will TIPS and Treasury yields rise?
A yield of 1.5% on a 10-year TIPS would be an 84 basis point rise from today’s yield and would cause about a 6% drop in the TIP ETF, giving you a price somewhere in the $104 to $105 range.
I am not saying this will happen, but I do think it could happen, and possibly is likely to happen. In the Wall Street Journal article, J.P. Morgan experts make an even more dire prediction:
J.P. Morgan expects inflation to remain tame next year, seeing year-over-year CPI running no higher than 1.7%. That, alongside an expected 120 basis point rise in real yields, translates into a -8.4% total loss on TIPS in 2014.



[…] Tipswatch, Synthetic calculation results in 0.25% inflation for October (Nov. 26, 2025) […]