
I was on vacation last week in sunny Florida and had limited Internet access. But I wasn’t totally out of touch: I had satellite radio on my cheapo Hyundai rental car, and could listen to CNBC and Bloomberg Radio. So I spent Thursday morning, driving to Sarasota, listening for the January inflation number.
In a two-hour drive, I never heard the number. What I did hear was this: “Treasurys are weakening today on the January inflation number.” That perked my interest. There’s a TIPS auction today! What was the inflation number? Never heard. What was happening to Treasurys? That I did hear: “The 10-year Treasury yield rose from 2.75% to 2.76%.” One basis point! That is not news, and inflation had nothing to do with it.
The inflation number, by the way, was 0.1% in January for the seasonally-adjusted Consumer Price Index for All Urban Consumers (CPI-U). Over the last 12 months, inflation was up a very mild 1.6%, still well below the Federal Reserve’s target of 2.0% and ‘danger level’ of 2.5%.
Read the full inflation report.
The non-seasonally adjusted CPI-U is used to determine the inflation adjustment to principal on TIPS and the future interest rate on I Bonds. In January, the non-seasonally adjusted number was 0.4%, but for the last 12 months the number remains at 1.6%.
Inflation is continuing at a very mild level. Gasoline prices fell 1.0% in January, but fuel oil prices increased 3.7% and natural gas was up 3.6%, the result of a wicked winter on the East coast.
Core inflation, which strips out food and energy, increased the same 0.1% in January and 1.6% for the last 12 months.
30-year TIPS auction
Of course, CNBC didn’t report on the TIPS auction. No mainstream media report on TIPS auctions, especially in the hour after the close. Thursday’s auction for a new 30-year TIPS, CUSIP 912810RF7, went off with a coupon rate of 1.375% and a yield to maturity of 1.495%. That result was slightly higher than expected; a week earlier I had noted a yield of 1.42% looked likely. But, no big surprises.
Read the TIPS auction announcement.
However, this was the highest yield for any 29- to 30-year TIPS at auction since June 2011, when a 29-year, 8-month TIPS went off at 1.744%. That was just before the beginning of a 24-month boom in Treasurys, which eventually deflated (a bit) in mid 2013.
Over the week, TIPS weakened as yields increased, but you can see from this chart that the Thursday auction, which closed at 1 p.m., was a rallying point for TIPS:

The TIP ETF is shown here in blue. It holds the full range of TIPS maturities. Over the last week, it lagged behind IEI (intermediate Treasurys) and AGG (the overall bond market). This means TIPS yields were rising faster than the overall bond market, resulting in a lower price.
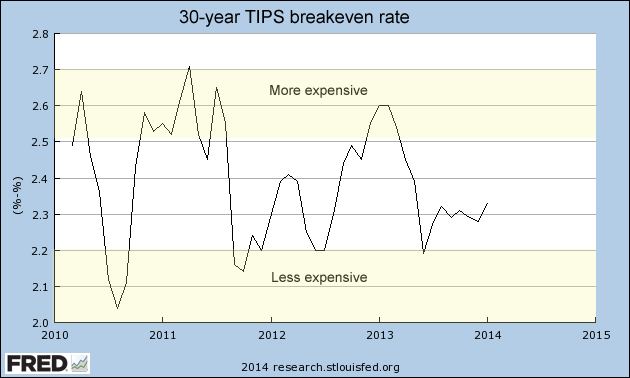
When you see a chart like this, you can conclude that TIPS yields are increasing at a higher rate than the overall bond market, and that should mean a lower inflation breakeven rate. Thursday’s auction resulted in an inflation breakeven rate of 2.23%, in the ‘normal range’ but 5 basis points less than looked likely a week earlier. A lower breakeven rate means that TIPS are cheaper against a nominal 30-year Treasury.
When you are a buyer, cheaper is better.
Reaction to the auction.
The Wall Street Journal noted that demand for the 30-year TIPS was ‘tepid,’ possibly because inflation continues to be muted:
(P)aying for inflation protection is a hard sell these days. The latest CPI reported Thursday morning showed consumer prices gaining just 0.1% last month and 1.6% over the year. Core prices, which exclude volatile food and energy costs, also rose a mere 0.1%. These measures fall well short of the Federal Reserve’s 2% long-run inflation goal. …
The massive amount of bets that piled up against TIPS in 2013 actually helped the market bounce back in January. But bond traders now say that for TIPS to keep buyers around, the economy will have to start showing more substantial signs of inflation.



Lou, the coupon rate should cover the taxes for the inflation accruals.