
TIPS are more attractive, but the I Bond’s fixed rate will be rising.
By David Enna, Tipswatch.com
While Treasury Inflation-Protected Securities and Series I Savings Bonds are both inflation-tracking investments, they each have a unique quality:
- TIPS are reactive, with prices and real yields changing by the hour to reflect the current market value on the secondary market.
- I Bonds are retroactive, with a real yield and interest rate locked in place for six months, based on market trends many months ago. There is no secondary market.
These qualities can work in favor of both investments. In past years, when the Federal Reserve was forcing real yields lower (and often negative), I Bonds had a huge advantage in real yield over TIPS, sometimes by as much as 150 basis points. But that is not the case today.
Market real yields have been soaring in 2026, pushing the 5-year real yield from 1.46% on January 1 to 2.55% at the close on Friday. Meanwhile, the I Bond’s fixed rate, which is equivalent to its real yield, has remained at 0.90% through the entire year.
I consider the 5-year TIPS and I Bond to be comparable investments. The I Bond can be redeemed without penalty after 5 years, matching the maturity of the TIPS. So when you see the 5-year TIPS real yield rise 109 basis points compared to zero for the I Bond, this is an easy conclusion: TIPS are the better investment.
It’s true, though, that I Bonds have several advantages over TIPS: tax-deferred interest, much better deflation protection, a flexible maturity, continual compounding of interest, and accumulated principal that can never go down in value. For that reason, I think a “fair value” fixed rate for the I Bond is equal to a ratio of 0.65 applied to the 5-year TIPS real yield.
Today, that ratio is only 0.35 (0.9/2.55 = 0.35). TIPS are a better value. This chart compares the 5-year real yield to the I Bond’s fixed rate since November 2023. Clearly, the ratio has moved way out of whack in recent months, as the I Bond’s fixed rate remains locked in at 0.9%.
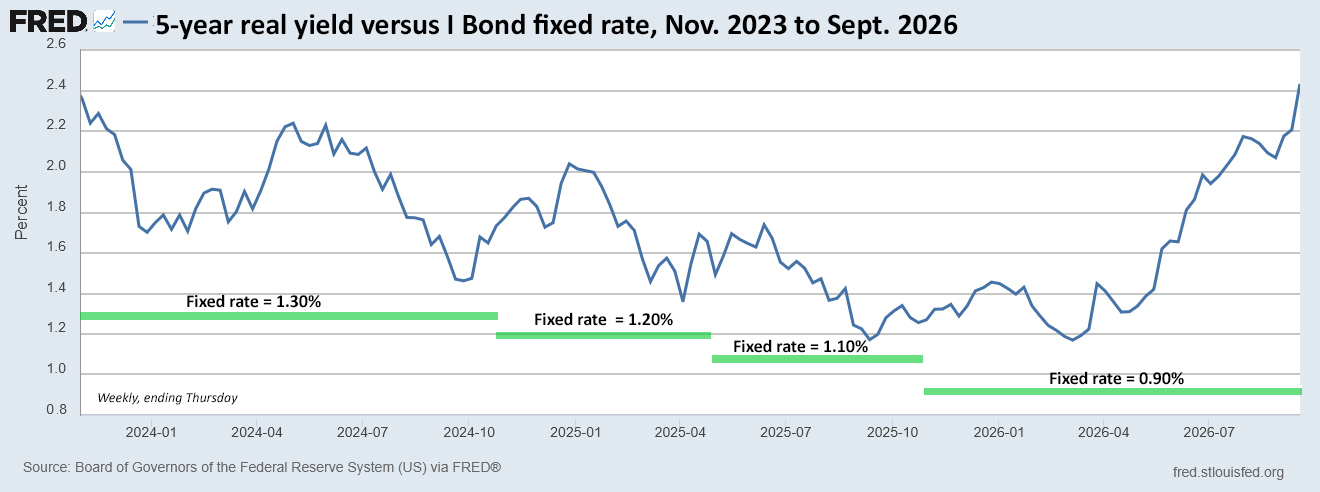
Conclusion. TIPS have a large yield advantage over I Bonds, especially for purchases through October. On November 1, the I Bond’s fixed rate is highly likely to go up, and the new composite rate should be attractive. Let’s scope out that upcoming reset.
Fixed rate: At least 1.30%
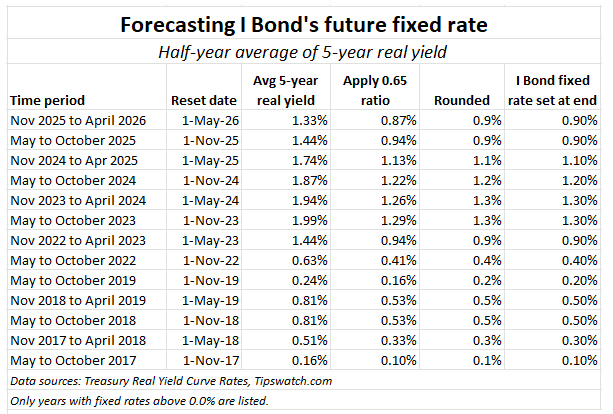
All my forecasts for the I Bond’s fixed rate are based on this formula: Take the average 5-year real yield over the preceding 6 months and apply a ratio of 0.65. This formula has been an accurate predictor for more than a decade. But of course, the Treasury could decide to ditch it. Let’s assume they won’t. Here’s the history:
Fixed-rate projection. As of Friday’s market close, the 5-year real yield had averaged 1.951134 from May 1 to September 18. Applying the 0.65 ratio results in a new fixed rate of 1.30%, up from the current 0.90%.
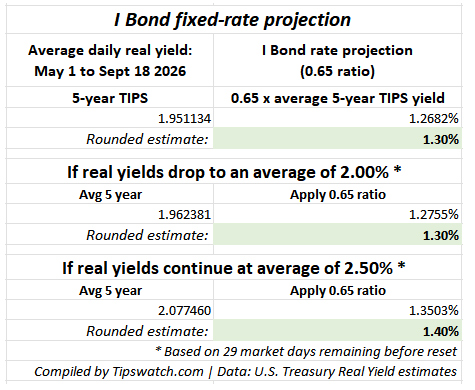
There is nearly zero chance that the fixed rate will fall below 1.30%, if the Treasury follows its traditional rate-setting methods. There are only 29 market days remaining before the reset. As the chart shows, even if the 5-year real yield miraculously dropped to 2.0% for all 29 days, the fixed rate projection remains at 1.30%.
However, if the real yield continues at the current rate of 2.50% or higher, the rate will rise to 1.40%, which would be the highest fixed rate since a reset in November 2006. This is probably a long-shot but is certainly in play.
I think a new fixed rate of 1.30% looks like the most likely result.
Remember that the I Bond’s fixed rate is permanent and is usually the most important factor in an I Bond investment. The exception is for an investor looking for a short-term investment with a high composite rate.
Variable rate
Although just one month of inflation (for September) remains in the six-month rate-setting string, this is a difficult projection. Monthly inflation has been volatile this summer, but rising gas prices this month point to a boost. How much? I’d guess something close to 0.35% to 0.40% for the month.
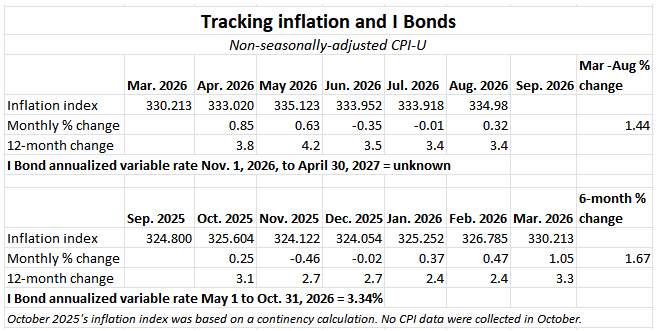
An increase of 0.35% in non-seasonally adjusted inflation in September would give you a 6-month inflation number of 1.79%, which translates to a new variable rate of 3.58%, higher than the current 3.34%. That’s an estimate!
Composite rate
If the reset settles in at 1.30% fixed and 3.58% variable, the resulting composite rate would be 4.90%, much higher than the current 4.26%. That is attractive. Again, this is an estimate. Many readers have told me they were waiting for the November reset to buy their 2026 allocation — $10,000 per person per year. It looks like waiting will have paid off.
Even I Bonds with a 0.0% fixed rate would be getting a composite rate of 3.58% for six months. Not awful. (My Fidelity Treasury money market fund is paying 3.4%.)
Qualifications
Even if the fixed rate rises to 1.40%, the math will favor TIPS. Using the 0.65 ratio versus a 5-year TIPS at 2.55%, the I Bond gets a fair-value fixed rate of 1.70%. At least 1.40% is getting closer.
I would not be surprised, however, if we get a dip in real yields in coming months. The recent run-up has been dramatic. But yields could continue rising if inflation surges higher and the Federal Reserve triggers another rate hike in October or December.
Another qualification for I Bond purchases is TreasuryDirect’s transition to ID.me for login verification, which hard-launches Oct. 28. A lot of people have been troubled by the move, since ID.me is a private company. Does that reduce the attractiveness of I Bonds, which can only be purchased at TreasuryDirect?
My feeling is that a fixed rate of 1.30% or 1.40% will be attractive enough for a purchase in 2027. I can adapt to the ID.me login. The new fixed rate will be available for purchase through April 2027. I will return to this topic in mid-October, after the release of the September inflation report on October 14.
See: TreasuryDirect is launching a controversial login system
And: TreasuryDirect provides more guidance on ID.me transition
• Confused by I Bonds? Read my Q&A on I Bonds
• Wise advice: ‘Don’t die with I Bonds’
• Let’s ‘try’ to clarify how an I Bond’s interest is calculated
• Inflation and I Bonds: Track the variable rate changes
• I Bonds: Here’s a simple way to track current value
• I Bond Manifesto: How this investment can work as an emergency fund
—————————
Donate? This site is free and I hope to keep it that way. Some readers have suggested having a way to contribute. I welcome donations, any amount. And FYI, ads on this site pay for about one visit to Costco.
—————————
Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).
Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.
David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.


 Treasury Inflation-Protected Securities

Excellent summary, as always. The ratio of 0.65 got me thinking as to what weights the Treasury assigned to various factors to bring the fixed rate on iBonds in equilibrium with the nominal rate on TIPs.
TreasuryDirect provides this cryptic information:
“The Secretary of the Treasury, or the Secretary’s designee, determines the fixed rate. The rate is based on market rates that have been adjusted to account for the value of components unique to savings bonds. These include the early redemption put option, tax deferral feature, deferred purchase feature, and Treasury’s administrative costs.”
No question that TIPS are the superior investment at this precise moment. But – if the Fed continues it’s rate hiking campaign thru the fall and winter we could easily see 1.8%+ fixed rate on the I Bond when it resets in April 2027.
Id.me transition aside – it’s looking like I Bonds are going to be quite popular going into 2027.
Two years ago I had a gut feeling the I Bond fixed rate might surpass its recent 2024 peak and hit 1.5% or higher in 2027-2028. Looks like that could happen next year (assuming current trends and the Treasury formula holds). I plan to avoid buying I Bonds this year, and will probably wait until May-Oct 2027 for my next purchase.
As for the November fixed rate, I think 1.4% is out of reach at this point. We don’t know if the Treasury makes its decision a few days before the end of each rate-setting period, so there may be fewer than 29 trading days left. If their calculation includes the last few trading days in April when yields were much lower, that would drag down the six-month average.
David – minor typo …month “point point” to a boost
I’m waiting until November for my personal account to save for a future smallish remodeling project. Then buy again in January. My two corporate accounts that I manage for others now have both TIPS from last January and I-bonds so will wait until January 2027.
They are both 501c (7) and do pay taxes at corporate rates on interest in excess of $1000 so the I-Bonds help manage that. I have 5 year TIPS in their accounts, too. Both could have near term capital needs.
Hard to beat what will likely be well above any 5 year CD rate (4.5% is best I can find). Also hard to imagine $7.00 a gallon diesel and $5 a gallon gas being readily absorbed into commodity and delivery prices while economy still appears robust from traditional metrics.
Thanks for the typo alert (and for being a careful reader). It is fixed.
Excellent summary as usual. On your final point (will the ID.me conversion deter users and affect pricing), I’d suggest “no.” I acknowledge that it’s a bit clunky to set up and can cause failures for some folks. But many people are already users of ID.me for SSA payments, Global Entry applications, or other federal govt interactions. Applying this system to Treasury Direct is fairly straightforward. And let’s not forget – the old TD website itself was a deterrent. Outdated, locking you out of accounts, poor / slow service, etc. The amount of people harmed by the ID.me switch may be balanced by those who benefit from it.
I could mistaken–I’ll welcome correction if I am–but ID.me is only a replacement for the traditional log-in path to TreasuryDirect, and will do nothing to improve “poor/slow service” for conversions of paper bonds to electronic, or transfers between accounts, or settlement of estates/trusts for deceased TreasuryDirect account holders, or anything else requiring the involvment of a human employee at the perpetually understaffed behind-the-scenes TreasuryDirect operation.
For what it’s worth, I have purchased I-bonds in the past and will not be doing so again because of ID.me. There are also other problems with TD, some highlighted in the recent article “don’t die with I bonds”; I’ve also been unable to add a redemption account using their system, which then won’t let me delete the nonfunctional one and try again… taken together, it’s become simply too much trouble. There are rare moments in time when I-bonds are appealing for intermediate-term savings, but I will just forgo the extra returns at those times. If they were to bring back paper bonds, I would consider them again. Otherwise, I’m not interested in new bonds if I have to use TD, and I will be filing form FS 5512 in January to redeem the ones I have. Voting at the ballot box is basically useless, but I also vote with my dollars and they won’t be going to TD ever again. I also sent them a note explaining what I’ve just said here. Obviously they are free to ignore me, but their appetite for borrowing is voracious and they would be wise not to turn away lenders. If Mr. Trump wants lower borrowing costs, he could start by telling Mr. Bessent to listen to his lenders.