Forecast: I Bond’s fixed rate is likely to fall to 0.90%

By David Enna, Tipswatch.com

In two months, probably on Halloween morning, the Treasury will announce a new fixed rate, inflation-adjusted variable rate and composite rate for U.S. Series I Savings Bonds purchased from November 2025 to April 2026.

And I have bad news for I Bond investors: The fixed rate is likely to fall from the current 1.10% to 0.90% at the reset. Of course, this is still up in the air, depending on how real yields track over the next two months. But the path looks pretty clear.

The forecast

The I Bond’s fixed rate is its “real yield” — the yield above future inflation. It is important because it is permanent, staying stable for potentially 30 years. So if you bought an I Bond in 2014 with a fixed rate of 0.2%, it will continue to have a 0.2% fixed rate for the life of the bond. Purchases through October 31, 2025, have a fixed rate of 1.10%.

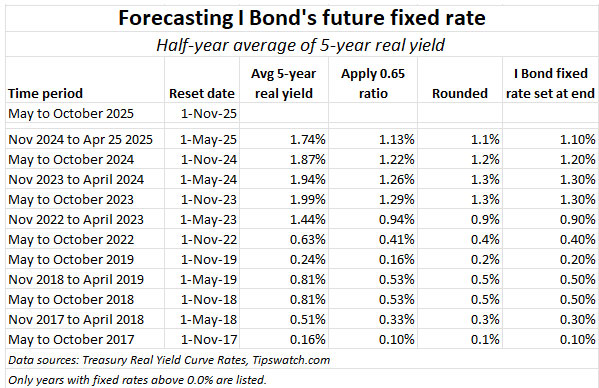
The Treasury has no announced formula for setting the I Bond’s fixed rate, meaning there is no calculation required by law or regulation enforcing the process. It is up to a decision by Treasury officials. However, I Bond watchers have settled on a forecasting tool that seems to work: Apply a ratio of 0.65 to the average 5-year TIPS real yield over the preceding six months. This formula has worked without fail at least since 2017.

With two months to go, I looked at 5-year real yield data from the date of the last reset on May 1, 2025, to the close of Aug. 29, 2025. Looking at just that data, the forecast is for a new fixed rate of 1.00% at the reset.
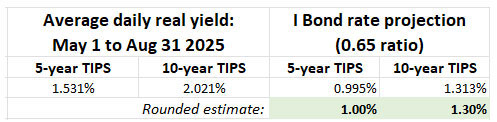
I added the 10-year TIPS information just because it is interesting — using the 10-year real yield data you get an new I Bond fixed rate of 1.30%, much more attractive. The spread between the 5-year real yield (currently 1.21%) versus the 10-year (1.82%) is amazing. But it also probably irrelevant because the forecasting formula has only worked using the 5-year TIPS real yield.

So, with two months of data yet to come, the I Bond’s new fixed rate would be 1.00%.

Extending the forecast

Now, let’s assume real yields hold steady at current levels through the month of October. That’s a bit iffy because the Federal Reserve is likely to cut short-term interest rates on September 17, and the 5-year TIPS real yield tends to move with those decisions. At this point, however, I think the rate cut is priced in.
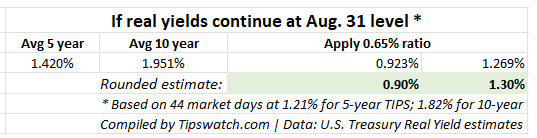
In this chart, I added 44 days at current market real yields, which lowers the 5-year real yield average to 1.420% and in turn drops the 0.65 ratio to 0.923%, resulting in a new fixed rate of 0.90%. The forecast using the 10-year real yield remains at 1.30%, but I don’t believe it is relevant.

Keep in mind: The I Bond’s fixed rate is always rounded to the one-tenth decimal point. That means a further fall to 0.80% is unlikely.

As of today, I project a new I Bond fixed rate of 0.90%.

This chart demonstrates the accuracy of this projection method for every year back to 2017. (Of course, we can’t be sure the current administration will continue on this course.)
What this means

One immediate conclusion is that the I Bond’s current permanent fixed rate of 1.10% and composite rate of 3.98% for six months is attractive. I Bond investors who haven’t bought the full 2025 allocation ($10,000 per person per calendar year) should consider making a purchase before November 1.

Hard to say just yet, but the new variable rate could be around 2.8% to 3.0%, resulting in a new composite rate pretty close to the current 3.98%. But a higher fixed rate, which is permanent, is always preferable. Here is the trend in I Bond rates over the last five years:
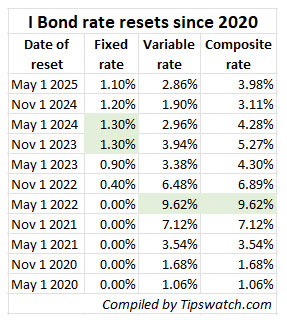
In 2022, we got that gaudy 9.62% variable rate for six months, but it was tied to a fixed rate of 0.0%. After a year or two, investors were dumping that investment, which is currently yielding 2.86%. The fixed rate of 1.30% that came later was much more attractive, in my opinion, as a long-term investment.

In January, would I be buying I Bonds with a fixed rate of 0.90%? Not in January, probably, but later in the year, yes. I’d probably wait until mid-April to see the trend in real yields and inflation.

As the reset date approaches, I will be writing more on this topic. This article is meant as a heads-up for investors speculating that we could get a boost in the fixed rate, which is unlikely.

And, again, we can’t be sure the Treasury won’t simply ditch our much-trusted 0.65 ratio and set the I Bond’s fixed rate in a radically different way. (Not likely, I hope.)

FYI: I focused this article on future rates and didn’t attempt to explain the investing purposes of I Bonds or their intricacies. You can find a lot of that information in these links:

• Confused by I Bonds? Read my Q&A on I Bonds

• Let’s ‘try’ to clarify how an I Bond’s interest is calculated

• Inflation and I Bonds: Track the variable rate changes

• I Bonds: Here’s a simple way to track current value

• I Bond Manifesto: How this investment can work as an emergency fund

—————————

Donate? This site is free and I plan to keep it that way. Some readers have suggested having a way to contribute. I would welcome donations. Any amount, or skip it, your choice. This is completely optional.

PayPal link / Venmo link

—————————

Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).

Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.

David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.

Posted in Cash alternatives, Federal Reserve, I Bond, Inflation, Savings Bond | Tagged , , | 34 Comments

An inflation surge could be coming in early 2026

What will be the effect of ‘big beautiful’ tax refund checks?

By David Enna, Tipswatch.com

Last week I read a report by David Kelly, chief global strategist at JPMorgan Asset Management, that mirrored some of my concerns that sizable federal tax refunds could set off a short-lived inflation surge in 2026.

Kelly’s report is titled, “The Investment Implications of the Refund Surge.” It begins with this:

On August 7th, with little fanfare, the IRS announced that, as part of its phased implementation of the OBBBA (One Big Beautiful Bill Act), it would not be adjusting W2 or 1099 forms for the current calendar year but would provide guidance and new forms, in due course, for calendar 2026.

This seemingly innocuous statement confirms that we will see an even larger crop of personal income tax refunds early in 2026 than was anticipated when the OBBBA was passed. These higher income tax refunds should work much like a new round of stimulus checks, adding to consumer demand and inflation pressures early next year.

Kelly notes that at the same time the refund checks will be flowing, the Federal Reserve may be cutting short-term interest rates, creating a “sugar rush” of consumer spending. He theorizes:

When their effects fade, it is quite possible that Washington will provide yet another round of stimulus to boost demand ahead of the mid-term elections.

Measuring the surge

Kelly notes that most of the OBBBA’s tax breaks are backdated to Jan. 1, 2025, but the IRS will not be issuing new W2 withholding schedules for 2025. The result is that “far too much money will have been withheld from taxpayers and refunds will surge in early 2026.”

But how much? Kelly theorizes: “(T)he total cost of these provisions for fiscal 2027, at $116 billion, should be very close to the amount owed to taxpayers for calendar 2025, deflated by, say 8%, for the growth in income in between – so roughly $107 billion.”

JP Morgan estimates the average tax refund in early 2026 will be $3,743, up about $500 from the 2025 level.

Looking at the overall economic impact, if we assume that 80% of these extra refunds are spent, this amounts to roughly 0.27% of GDP. If this money were spent evenly in the first six months of 2026, it could boost annualized real GDP growth by over 0.5% in the first quarter. If we add to this the impact of lower withholding that should finally kick in at the start of 2026, it could add 0.8% to real GDP growth in the first quarter. ….

If consumers generally use this money quickly, then by the third quarter of next year, consumer spending could slow again and, by the fourth quarter, it could slump. …

It could well be that, faced with this possibility, Congress approves some further fiscal stimulus such as the “DOGE dividends” that were floated earlier this year or the more recently proposed “tariff rebate checks”.

And then what?

Kelly speculates the Federal Reserve will lower interest rates by 25 basis points on Sept. 17, which seems fairly locked in. He adds, “Such a move is unlikely to spur faster economic growth in the short run, setting the stage for another rate cut in October or in December or both.”

So … two or three cuts to short-term interest rates could come just months before the bigger tax refund checks begin rolling out through the first half of 2026. Kelly concludes:

(I)nvestors might doubt the Fed’s commitment to stable inflation, potentially leading to a steeper yield curve, a lower dollar and lower stock prices. For investors, this underscores the need to have a greater allocation to international assets denominated in foreign currencies and the importance of having alternative assets with lower correlations to U.S. stocks and bonds.

My thoughts

It was my theory that several of the OBBBA provisions had the potential to be inflationary in the near term — no taxes on tips, no taxes on overtime, larger senior standard deduction, a new break for auto-loan interest, higher state-and-local tax deductions. The result: more money for consumers to spend.

Kelly’s assumptions make sense, in that a $500 boost to income tax refunds (along with other tax breaks) could trigger more aggressive consumer spending, which in turn could spur inflation higher. Plus, once 2026 begins, W2 withholding levels will be adjusted, giving many consumers an increase in take-home pay.

Will consumers rush to spend? I recall, unfortunately, the sudden explosion of hot-rod vehicles on Charlotte streets during the COVID stimulus roll-outs. For some people, the money was going to down payments on a depreciating asset. Not good.

Or, we could hope, people would try to pay down personal debt. In mid-2025, the average American family was carrying $6,371 in credit card debt, the highest level since the New York Fed started tracking this in 1999.

—————————

Donate? This site is free and I plan to keep it that way. Some readers have suggested having a way to contribute. I would welcome donations. Any amount, or skip it, your choice. This is completely optional.

PayPal link / Venmo link

—————————

Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).

Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.

David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.

Posted in Inflation, Tariffs, Treasury Bills | Tagged , | 25 Comments

Vanguard backs off on raising its bond-trading minimum to $10,000

IMPORTANT NOTE: I wrote this article on Wednesday to be published Sunday while I am visiting family out of town. It appears that Vanguard has backed off on raising the bond minimum to $10,000, based on Boglehead discussions posted Saturday and today.

The note announcing the change has been removed from the trading platform. If anyone gets further updates please post them in the comments.

A rather ominous AI image for “Bond investors locked out of market.” Source: Google Gemini

By David Enna, Tipswatch.com

A few years ago, I was writing about bid-ask spreads for TIPS on the secondary market and noted I was able to purchase a “very small” order of $10,000 with a bid-ask spread only 2 basis points below a high-dollar purchase..

What I meant: In the world of TIPS trading, $10,000 is an insignificant amount. But a reader immediately jumped all over me for saying a $10,000 purchase is “very small” and noted that a lot of investors can’t afford that large a purchase.

Point taken and lesson learned. But then last week we got this message at the top of Vanguard’s bond-trading platform:

Click on image for larger version. (This notice has now been removed from the Vanguard site.)

As of September 13, Vanguard said, it would raise its minimum bond purchase, currently $1,000 par value, to $10,000. That would apply to all bond purchases — including Treasury auctions. Only new issue CDs would be exempt from the new policy.

That would be a dramatic and unwelcome change.

I know that many Tipswatch readers use the Vanguard site to make small Treasury auction purchases, especially for T-bills. For example, an investor could buy $1,000 in 4-week Treasurys every month and then roll them over to cap out at $12,000 in one year. That makes sense for an investor who can’t afford a one-time $10,000 investment.

From my own experience: When TIPS real yields were just starting to rise from below-zero in April 2022 I began “nibbling” into TIPS at auction, usually with $5,000 purchases. That would no longer be allowed.

And this year, as TIPS and other investments in my traditional IRA have matured or paid interest, I have purchased T-bills maturing before the end of the year to prepare for RMDs beginning in January 2026. All of those purchases were less than $10,000.

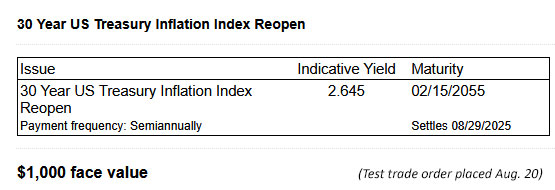
As of last week, you could still do a $1,000 minimum purchase for a TIPS auction, as shown in this quote from Wednesday. That option would have ended on September 13, five days before the next TIPS auction of a reopened 10-year.

I tend to do all my individual bond purchases on the Vanguard site, where I have my individual IRA. I also have an account at Fidelity, where $1,000 remains the minimum bond purchase for a Treasury auction. TreasuryDirect has a $100 minimum.

At all brokerages, bond sellers set minimum lot-size amounts, which will vary and will often lock out a $1,000 purchase. Vanguard said its new policy would not apply to “sell orders” — which are placed on an exchange outside of Vanguard — so it may be possible to find sellers still allowing $1,000-lot offers. I find this very confusing.

Clearly, however, auction purchases would have had a $10,000 minimum.

Why do this?

Vanguard has not stated its reasoning for this move (or the apparent reversal), which is going to lock some investors, especially small-scale investors, out of buying individual bonds. And then what? In Vanguard’s brief announcement, it provides a link to “other products that have lower minimums.” The link goes to a page titled “Investment products: Mutual funds, ETFs and more,” which actually offers no advice at all on products with low minimum investments.

Obviously, Vanguard’s reason No. 1 is cost savings, because these small-lot bond purchases entail some costs and some Treasury purchases have zero commissions. So Vanguard’s aim is to get you out of this market and into one of its other, more profitable products.

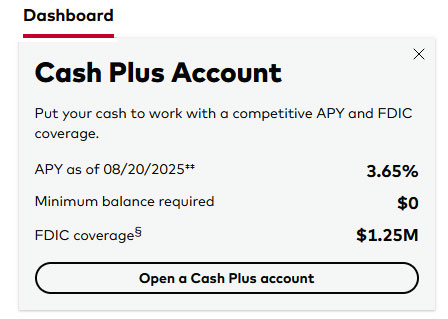
For evidence, just look at the top left corner of your account dashboard for a prominent ad promoting Vanguard’s new and heavily promoted Cash Plus Account:

I don’t have a Vanguard Cash Plus Account (I use Fidelity’s Cash Management Account instead). Vanguard’s version is probably a fine product — and it has no minimum investment — but it is currently paying 3.65% versus 4.24% for Vanguard’s much-loved Vanguard Treasury Money Market Fund (VUSXX).

Of course, I totally accept that a cash management account — with its flexibility for bill payments and withdrawals — would have a higher expense ratio than VUSXX’s ultra-low 0.07%. Fidelity’s CMA allows access to its Treasury Money Market Fund (FZFXX), currently yielding 3.93%. Its expense ratio is 0.42%.

By increasing its minimum bond investment to $10,000, was Vanguard trying to prod small-scale investors to move into its Cash Plus Account? For many investors, that could actually be a smart move. But for others, the higher bond minimum is at least an annoyance.

Reaction or over-reaction?

Vanguard has apparently reversed this $10,000 minimum before it went into effect. I hope that is true and the decision was based on strong investor feedback.

In my case, why buy T-bills in a traditional IRA when I can (and do) use VUSXX for idle cash? The yields are going to be similar. The reason is psychological, I guess, in that I am trying to use T-bills to set aside cash for a specific purpose — in my case, future required minimum distributions.

Other investors may be setting aside locked-up cash for property taxes, wedding expenses, a car purchase, even I Bond purchases next year. Or maybe they want to build a 10-year bond ladder with $5,000 in each year? The new $10,000 minimum is going to throw a wrench into those strategies.

This isn’t an Earth-shattering policy change. But it would affect investing plans for some of Vanguard’s customers.

Years ago, I had a cash account at Wells Fargo that paid current money market rates. For a long time, that rate was about 0.05%, but then over a half year yields surged higher to about 3.0%. I was pleased. Within a month, Wells announced it was changing the terms and the rate dropped to 0.05%, where it remains. I pulled nearly all my investments from Wells Fargo.

I won’t do the same with Vanguard. I am just going to announce that I am disappointed with this decision from an investment firm I have trusted and admired for four decades.

—————————

Donate? This site is free and I plan to keep it that way. Some readers have suggested having a way to contribute. I would welcome donations. Any amount, or skip it, your choice. This is completely optional.

PayPal link / Venmo link

—————————

Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).

Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.

David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.
Posted in Cash alternatives, Investing in TIPS, TreasuryDirect | Tagged , , | 26 Comments

30-year TIPS reopening gets real yield of 2.650%, highest in nearly 24 years

By David Enna, Tipswatch.com

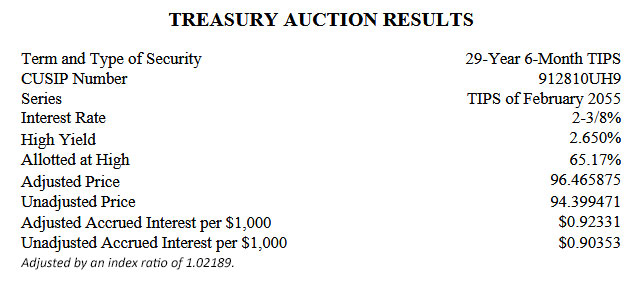
Investors were ready and willing to jump aboard today’s auction of a reopened 30-year Treasury Inflation-Protected Security, CUSIP 912810UH9. And why not? The resulting real yield to maturity of 2.650% was the highest for this term at auction since October 2001.

This TIPS will mature February 15, 2055. It has a coupon rate of 2.375%, which was set by the originating auction on February 20, 2025.

Demand at this auction looked strong. The “when-issued” yield prediction was 2.673%, but bidders brought that down to 2.650%. The bid-to-cover ratio was 2.78, much higher than recent auctions of this term. There is a market for 30-year TIPS!

Definition: The “real yield to maturity” of a TIPS is its yield above official future U.S. inflation, over the term of the TIPS. So a real yield of 2.65% means an investment in this TIPS would provide a return that exceeds U.S. inflation by 2.65% for 29 years, 6 months.

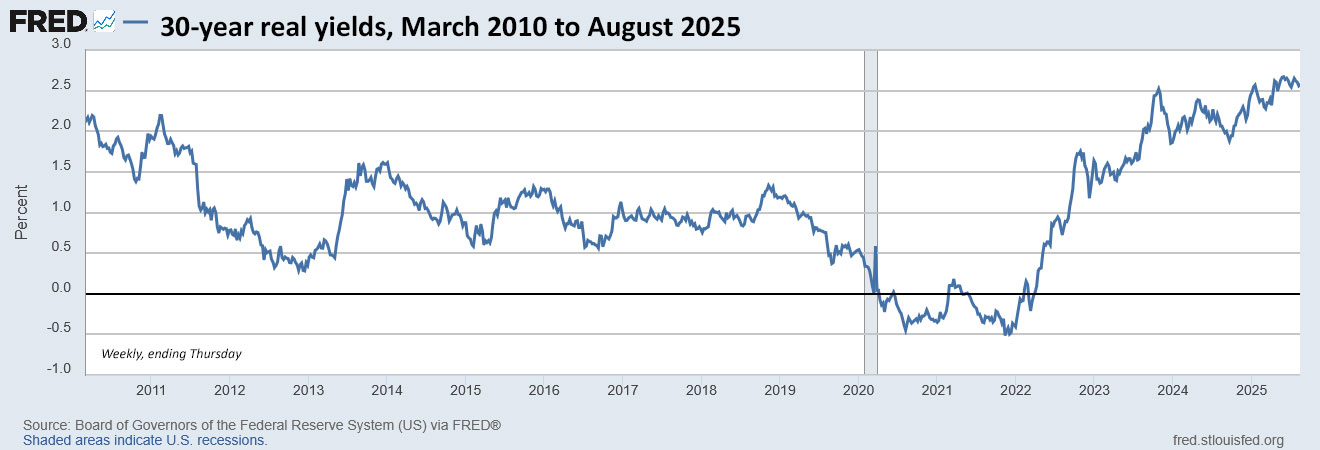
As I noted in my preview article for this auction, the Treasury halted 30-year TIPS auctions from October 2001 to February 2010. Before 2001, auctioned real yields were much higher across all maturities of TIPS. But today’s above-inflation yield of 2.650% was nearly 25 basis points higher than any other auction of this term since 2010.

Here is the trend in the 30-year real yield over the last 2 1/2 years:

Click on image for larger version.

Pricing

Because the auction’s real yield of 2.650% was well above the coupon rate of 2.375%, investors got this TIPS at a substantial discount, an unadjusted price of 94.399471. In addition, it will carry an inflation index of 1.02189 on the settlement date of Aug. 29. With that information, we can calculate the exact cost of a $10,000 investment:

  • Par value purchased: $10,000.
  • Principal on settlement date: $10,000 x 1.02189 = $10,218.90
  • Cost of investment: $10,218.90 x 0.94399471 = $9,646.59
  • + accrued interest of $9.23

In summary, an investor placing an order for $10,000 of this TIPS paid $9,646.59 for $10,218.90 of principal as of the August 29 settlement date. From then on, the investor will earn inflation accruals matching U.S. inflation, plus an annual coupon rate of 2.375% for the next 29 years, 6 months.

Inflation breakeven rate

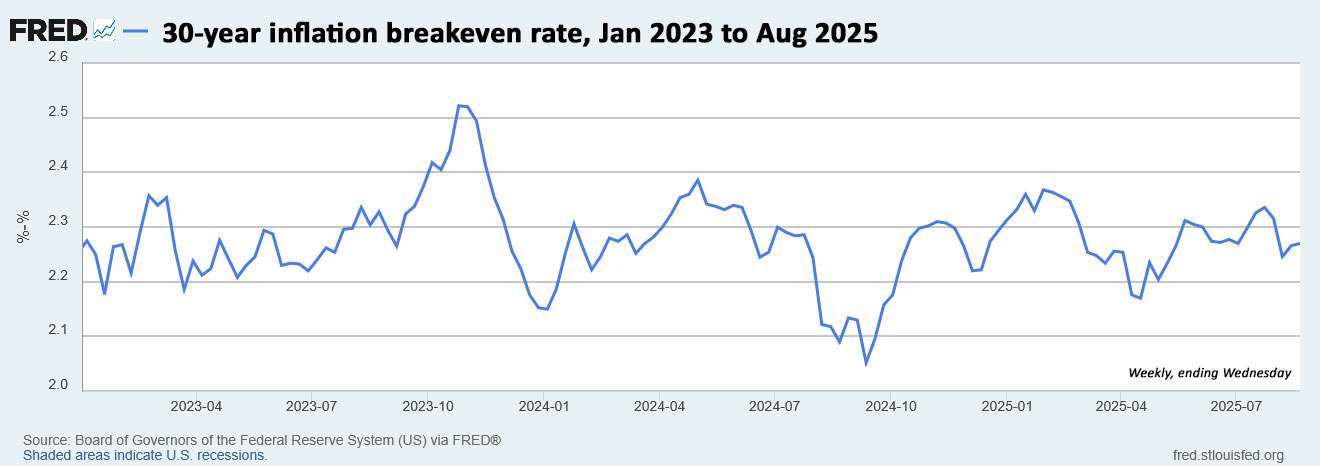
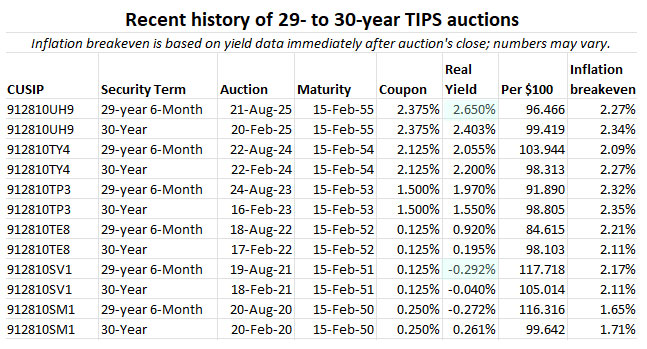
The 30-year Treasury bond was trading with a nominal yield of 4.92% at the auction’s close, so this TIPS gets an inflation breakeven rate of 2.27%, in line with recent auction results. This means it will outperform the nominal bond if inflation averages more than 2.27% over the next 29 years, 6 months.

Some perspective: Look at 30-year inflation averages over the last 55 years. Only one 30-year period (ending in 2020) had average inflation of 2.2%. Every other one was higher.

The inflation breakeven rate isn’t truly a prediction of future rates. It is a measure of current sentiment. Here is the trend in the 30-year inflation breakeven rate over the last 2 1/2 years:

Click on image for larger version.

Reaction

For daring investors willing to take on the very long term, this TIPS ended up being a strong investment. Yes, real yields could continue to climb, but getting 2.65% above inflation makes for a strong asset — one you couldn’t find for nearly 24 years.

The auction result wasn’t much of a surprise, but demand was strong. That hasn’t always been true for this 30-year term, one reason the Treasury has kept auction sizes steady for four years, while bumping up sizes for 5- and 10-year TIPS.

For today’s buyers, I just want to point out that just four years ago this same term and same auction size got a real yield of -0.292%. Today’s result was a whopping 294 basis points higher. Congrats on your purchase.

Here are auction results for this term over the last five years:

• Now is an ideal time to build a TIPS ladder

• Confused by TIPS? Read my Q&A on TIPS

• TIPS in depth: Understand the language

• TIPS on the secondary market: Things to consider

• TIPS investor: Don’t over-think the threat of deflation

• Upcoming schedule of TIPS auctions

—————————

Donate? This site is free and I plan to keep it that way. Some readers have suggested having a way to contribute. I would welcome donations. Any amount, or skip it, your choice. This is completely optional.

PayPal link / Venmo link

—————————

Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).

Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.

David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.
Posted in Inflation, Investing in TIPS, TreasuryDirect | Tagged , , , , , , | 20 Comments

30-year TIPS auction could snag highest real yield in nearly 24 years

Aug. 21 update: 30-year TIPS reopening gets real yield of 2.650%

By David Enna, Tipswatch.com

The U.S. Treasury on Thursday will offer $8 billion in a reopening auction of CUSIP 912810UH9, a 30-year Treasury Inflation-Protected Security. The auction, which will create a 29-year, 6-month TIPS, has the potential to set a multi-decade high for real yield.

This TIPS originally auctioned February 20, generating a real yield to maturity of 2.403%, the highest in 23 years for this term. Its coupon rate was set at 2.375%, also the highest for this term in 23 years.

CUSIP 912810UH9 trades on the secondary market. According to Bloomberg’s U.S. Yields, it closed Friday with a real yield of 2.65%, well above the February record. The U.S. Treasury is currently estimating the real yield of a full-term 30-year TIPS at that same number, 2.65%.

Definition: The “real yield to maturity” of a TIPS is its yield above official future U.S. inflation, over the term of the TIPS. So a real yield of 2.65% means an investment in this TIPS would provide a return that exceeds U.S. inflation by 2.65% for 29 years, 6 months.

Reality check. When I talk about a nearly 24-year high, I have to note that the Treasury stopped offering 30-year TIPS from October 2001 to February 2010. Before 2001, auctioned real yields were much higher across all maturities of TIPS, which were very new and little understood at the time. These early TIPS were spectacular investment opportunities.

So what we are really looking at is the 15-year history of the 30-year TIPS since 2010, which is charted here and clearly shows that the above-inflation yield in August 2025 is historically significant:

Click on image for larger version

Dangers of the 30-year term

My investment philosophy for TIPS is: buy and hold to maturity. For an investor with a 30-year time-frame — say someone aged 50 to 60 — this week’s TIPS auction should be attractive, potentially as the top rung of TIPS investment ladder. It should also be attractive for TIPS traders willing to bet that real yields will be declining in the future.

A 30-year TIPS is highly volatile. For example, a 30-year TIPS issued just three years ago — CUSIP 912810TE8 — auctioned with a real yield of 0.195% and a coupon rate of 0.125%. Today, that TIPS is trading with a real yield of 2.67% and a price of 51.90, meaning it has lost nearly 50% of its market value in three years.

(Side note: On the day of that 2022 auction, February 17, the 30-year Treasury bond had a nominal yield of 2.31%, less than real yield of similar TIPS today.)

That February 2022 30-year auction was potentially disastrous for investors who could not hold to maturity. This week’s auction is much more attractive, and offers some potential for capital gains for TIPS traders. But that would backfire if real yields continue rising.

Want to speculate? Go for it. My recommendation is always to buy a TIPS with the plan to hold to maturity.

Pricing

At Friday’s close CUSIP 912810UH9 was trading with a discounted price of 94.38 because the market real yield of 2.65% was above the coupon rate of 2.375%. This will likely change before the Thursday auction, but can give us an idea of pricing:

  • Par value purchased: $10,000
  • Inflation index on Aug. 29 settlement date: 1.02189.
  • Actual principal purchased: $10,000 x 1.02189 = $10,218.90
  • Cost of investment: $10,218.90 x 0.9438 = $9,644.60
  • + accrued interest of about $9.23.

So in this scenario — meant to be an illustration — an investor would pay $9,644.60 for $10,218.90 in principal as of the settlement date of August 29. From then on, the investor would earn accruals matching future inflation, plus an annual coupon rate of 2.375% paid on inflation-adjusted principal for 29 years, 6 months.

Inflation breakeven rate

The 30-year Treasury bond closed Friday with a nominal yield of 4.92%, which means this TIPS at 2.65% would have an inflation breakeven rate of 2.27%, more or less in line with recent auctions of this term. This means it will out-perform the nominal Treasury if inflation averages more than 2.27% over the next 29 years, 6 months. (Inflation over the last 30 years, ending in July, has averaged 2.5%.)

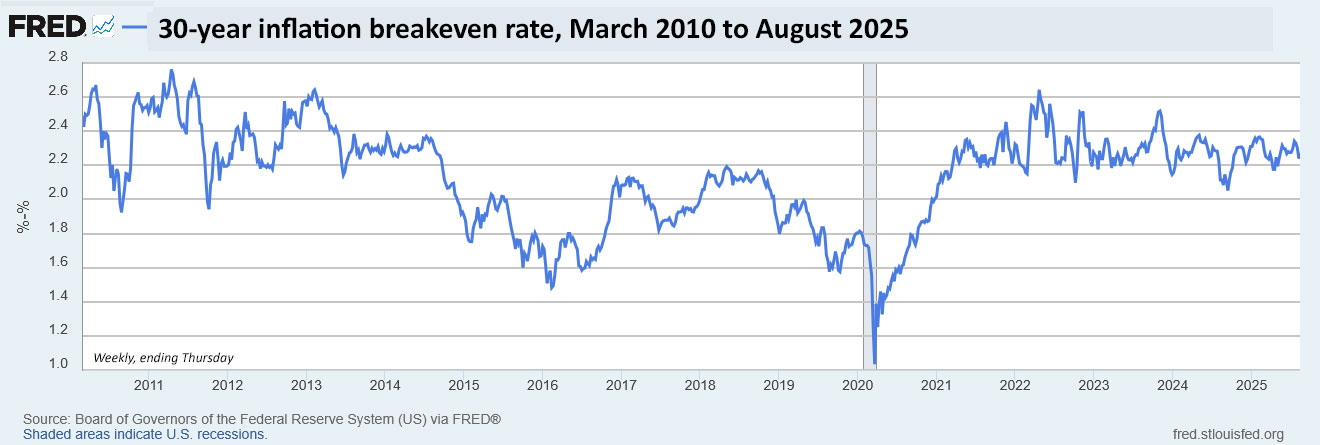
My quick impression is that a 30-year nominal approaching 5% is pretty attractive. But I’d still prefer the inflation-protection that comes with the TIPS. Here is the trend in the 30-year inflation breakeven rate over the last 15 years:

Click on image for larger version.

This chart is historically stunning, in my opinion, with 30-year inflation expectations waffling between 2.2% to 2.4% for nearly four years. This seems to be a remarkably consistent view of future inflation — which probably means it will be wrong.

Thoughts on the auction

There is no particular reason to wait for Thursday’s auction to purchase CUSIP 912810UH9 unless you want to buy a small amount at TreasuryDirect. If you have access to a major brokerage, this TIPS is trading on the secondary market and can be purchased any time you see a real yield you like.

The advantage of buying at auction, especially through TreasuryDirect, is that even small-lot purchases will get the auction’s high yield. The advantage of the secondary market is that you can see exactly the price and real yield you will be receiving. The negative is that you may face a small bid-ask spread. Most of the time, it doesn’t make a huge difference, but if you see a real yield you like, know that you can probably get it on the secondary market without dealing with the auction’s uncertainty.

I won’t be a buyer because my TIPS ladder tops out in 2043, when in theory I will be 90 years old. I don’t think I need to extend beyond that year.

For the right buyer with a true plan to hold to maturity, I think CUSIP 912810UH9 looks like a solid investment. As always, do your own research.

This TIPS auction closes Thursday at 1 p.m. ET. Non-competitive bids at TreasuryDirect must be placed by noon Thursday. If you are putting an order in through a brokerage, make sure to place your order Wednesday or very early Thursday, because brokers cut off auction orders before the noon deadline.

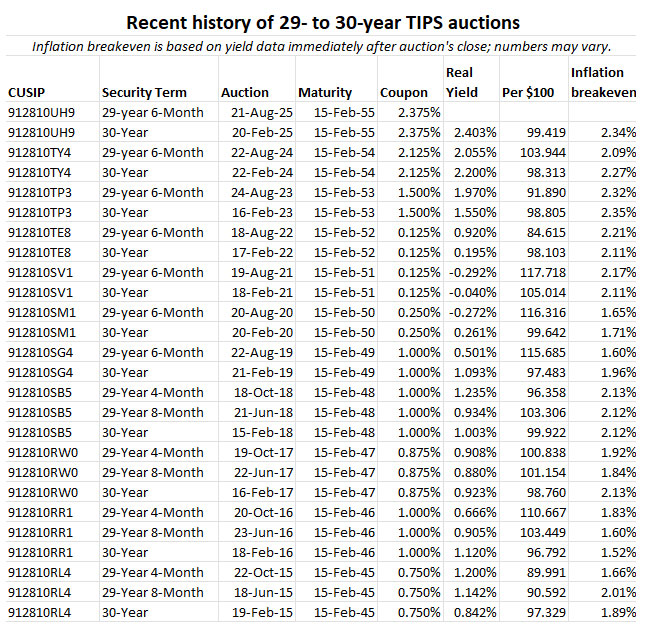
Here is a history of auctions of this term over the last 10 years:

• Now is an ideal time to build a TIPS ladder

• Confused by TIPS? Read my Q&A on TIPS

• TIPS in depth: Understand the language

• TIPS on the secondary market: Things to consider

• TIPS investor: Don’t over-think the threat of deflation

• Upcoming schedule of TIPS auctions

—————————

Donate? This site is free and I plan to keep it that way. Some readers have suggested having a way to contribute. I would welcome donations. Any amount, or skip it, your choice. This is completely optional.

PayPal link / Venmo link

—————————

Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).

Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.

David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.

Posted in Inflation, Investing in TIPS, TreasuryDirect | Tagged , , | 22 Comments