
Auction update: 5-year TIPS auction gets real yield of 2.367% on a strong day for Treasurys
By David Enna, Tipswatch.com
The U.S. Treasury on Thursday will auction $26 billion in a new 5-year Treasury Inflation-Protected Security, CUSIP 91282CRR4. While the real yield and coupon rate will be determined by auction results, this TIPS looks highly attractive, for just about any conservative investor.
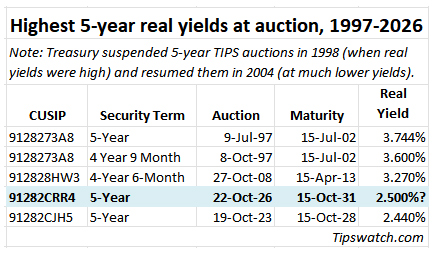
At Friday’s market close, the Treasury was estimating the real yield of a full-term 5-year TIPS at 2.52%, down from recent highs but up 88 basis points since June 1. If this TIPS gets a real yield above 2.44%, it will be the highest at auction for this term since the financial crisis of 2008.
Definition: The “real yield to maturity” of a TIPS is its yield above future U.S. inflation, over the term of the TIPS. So a real yield of 2.52% means an investment in this TIPS would provide a return that exceeds official U.S. inflation by 2.52% for 5 years.
This is a near-zero risk investment (when held to maturity) with a term of only 5 years, the shortest the Treasury issues for TIPS. It will auction at a price very close to par value, and probably get an attractive coupon rate of 2.375% to 2.50%.
During the dreary and not-long-ago era of very low real yields, I was a fan of the 5-year TIPS for one reason: “The term is only five years.” Its value isn’t going to fluctuate wildly with changes in market real yields. Just hold it and forget it.
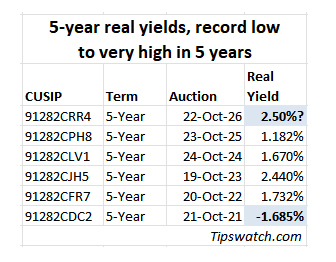
And don’t underestimate the value of tracking future inflation. See that 5-year TIPS issued in October 2021 at the bottom of the list, with a miserable real yield of -1.685%, the lowest for any TIPS in history? It matured last week. Because of surging inflation, it ended up generating a nominal return of 2.375%, well above the 1.20% offered on a 5-year Treasury note in October 2021. (I will post an article on this soon. Meanwhile, see my TIPS vs. Nominals page.)
Today, real yields are much higher. Getting an inflation-adjusted return of around 2.5% for five years is a safe, sensible investment choice for money you are putting aside for use in 5 years.
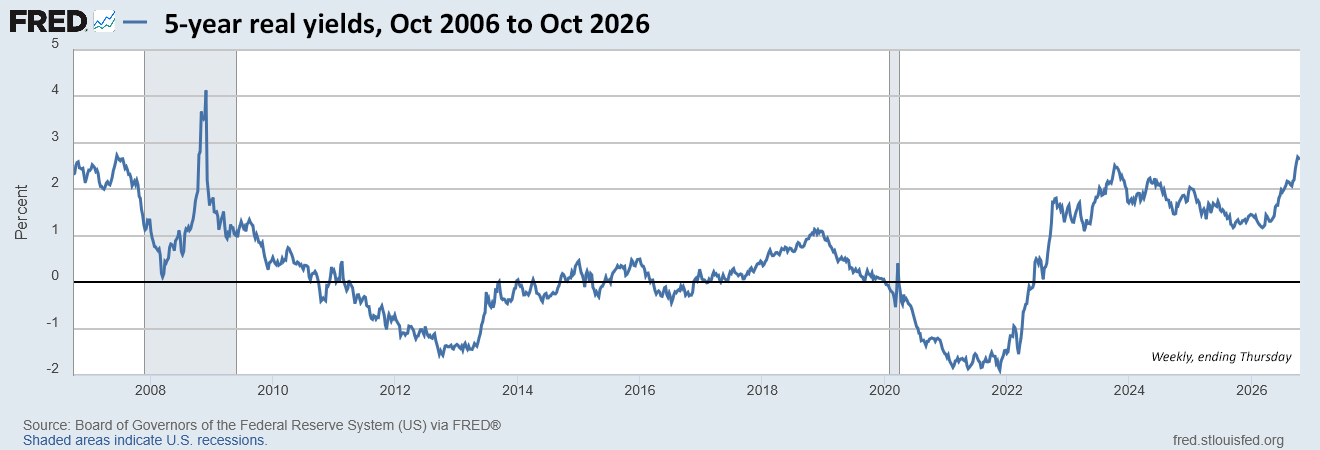
Here is the trend in the 5-year real yield over the last 20 years. With the exception of the very quick spike in 2008 (as all financial assets were being sold off), the current real yield is a two-decade high:
The October quandry
I’ve discussed this often but it is important to remember: The October auction of a new 5-year TIPS will almost always get a real yield to maturity that is lower than the “market” real yield you will see listed at your brokerage or in financial charts. That market number is based on the current trading yield of the most recent 5-year TIPS, CUSIP 91282CQP9, issued in April.
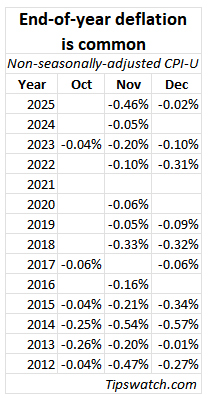
The April 5-year generally gets a higher real yield because it will be exposed to late-year non-seasonably adjusted deflation in its closing months, which happens almost every year. I wrote about this in October 2023: “There is an explanation for everything, right?“
The October 5-year auction is hard to predict, especially when real yields are volatile as they are today. Because that April TIPS closed Friday with a real yield of 2.439%, we could potentially see Thursday’s auction result come in below 2.52%, which is the Treasury’s current estimate. Be ready for anything, including volatility.
Pricing
Because this is a new TIPS, its coupon rate will be set to the 1/8th percentage point below the auctioned real yield, resulting in a slightly discounted unadjusted price. It will also carry an inflation index of 1.00154 on the settlement date of October 30, which will slightly raise the adjusted price. Overall, the auction should go off near par value. In other words, order $10,000 par value and the cost will be about $10,000.
Inflation breakeven rate
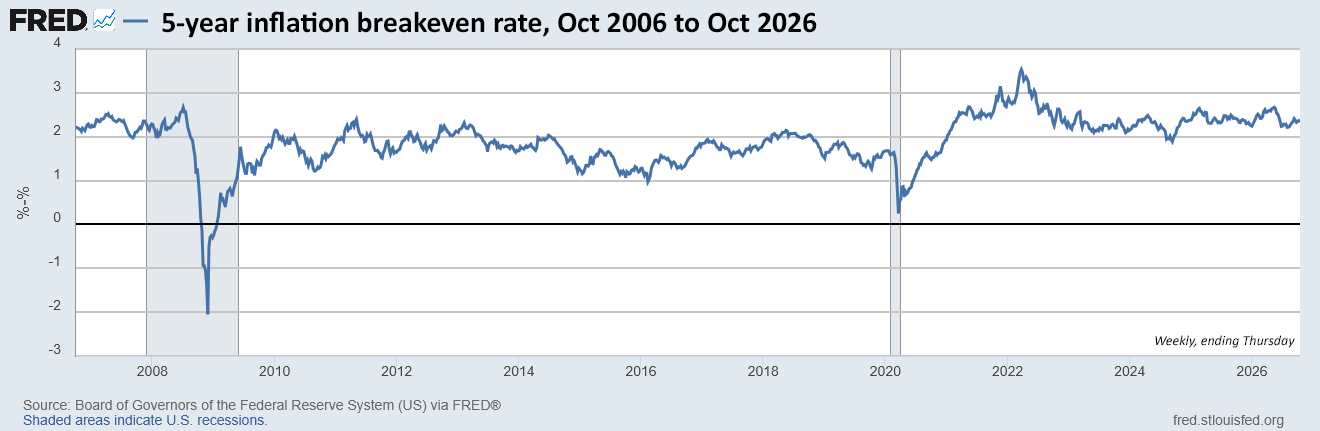
With the 5-year Treasury note trading with a nominal yield of 4.89%, this TIPS currently has a 5-year inflation breakeven rate of 2.37%, in line with recent trends. So it will outperform a nominal 5-year if inflation averages more than 2.37% over the next 5 years. (Nominal yields have also fallen a bit in recent days; the 5-year note topped at 5.09% on September 30.)
Here is the trend in the 5-year inflation breakeven rate over the last 20 years. Notice the amazing stability in inflation expectations since late 2022:
Thoughts
Market conditions can change by the Thursday auction, but this should be a very attractive issue. I emphasize that the term is only 5 years, so holding to maturity is not a chore, and even if you need to sell, volatility should be fairly low.
I won’t be a buyer because the 2031 rung of my TIPS ladder is complete. Otherwise, I would be jumping on this one. Why is it a strong conservative investment?
- It has the full backing of the U.S. Treasury, which makes it near-zero credit risk.
- The 5-year term makes it less volatile than other auctioned TIPS maturities.
- The investor will be paying close to par value, which is guaranteed to be returned at maturity even if severe deflation sets in. (That’s unlikely, by the way.)
- The investor will earn an annual coupon rate of, let’s say, 2.375% on inflation-adjusted principal through the entire 5 years.
- The principal balance at maturity will be adjusted for official U.S. inflation. Even if you doubt those numbers, inflation is a serious risk for conservative investors.
This TIPS auction closes Thursday at 1 p.m. ET. Non-competitive bids at TreasuryDirect must be placed by noon Thursday. If you are putting an order in through a brokerage, make sure to place your order Wednesday or very early Thursday, because brokers cut off auction orders before the noon deadline.
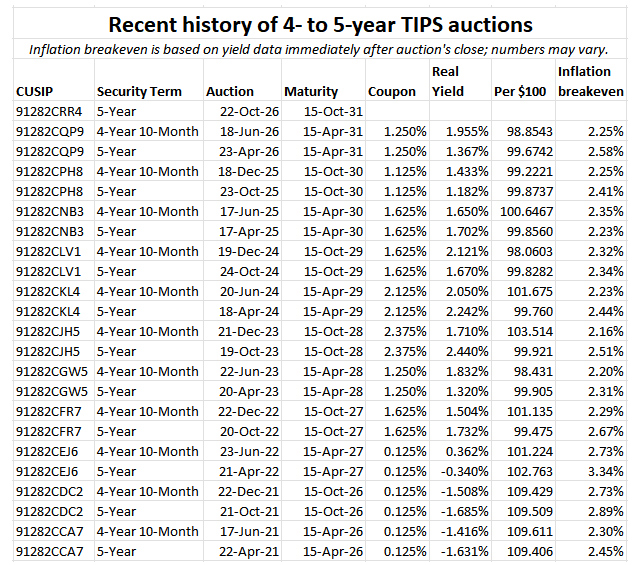
I will be posting the auction results soon after the close on Thursday. Here is a history of auction results for this term over the last 5 years:
• Now is an ideal time to build a TIPS ladder
• Confused by TIPS? Read my Q&A on TIPS
• TIPS in depth: Understand the language
• TIPS on the secondary market: Things to consider
• TIPS investor: Don’t over-think the threat of deflation
• Upcoming schedule of TIPS auctions
—————————
Donate? This site is free and I hope to keep it that way. Some readers have suggested having a way to contribute. I welcome donations, any amount. And FYI, ads on this site pay for about one visit to Costco.
—————————
Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).
Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.
David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.


Thursday morning pre-auction UPDATE: Real yields are tumbling this morning amid market turmoil. The April 2031 TIPS is now trading with a real yield of 2.45%, down about 7 basis points from yesterday. This is just hours before the auction, so the auction is going to be highly unpredictable.
I am not surprised because this seems to be common when the the 5 year TIPS auctions arrive. Maybe because it is a popular individual choice.
On another note, I was wondering David, whether you think it is a good idea to have ID monitoring, such as LifeLock?
I don’t use LifeLock, which is what I would call a “peace of mind” investment. I do have credit freezes at all the credit monitoring services and try to keep track of my financial accounts. Then I … hope.
I’ve been subject to various data breaches and have had free ID monitoring up until this year. So it doesn’t feel good to go without. AAA members get a free version, which has been reviewed as being better than nothing. AARP has some good discounts for LifeLock. This is off the subject of inflation protected securities, but with the ID Me conversion I thought it might be appropriate.
David – Been a Tipswatch follower for a few years. This may be an idea for a full article, but how much should younger investors put into TIPS and I-Bonds? I’m 34 (probably on the younger-side here) and I’m afraid I’m being too conservative. I’ve maxed my I-Bond purchases for the past 4 years with an average fixed rate about 1%. In this high fixed rate environment, should I continue investing in inflation protected securities or move into equities. Right now, about 25% of my annual savings go into I-Bonds. No big short-term purchases are expected, so my plays are longer-term.
Eric, does your portfolio have any real assets as a hedge against stagflation and/or a BLS that fiddles with the official inflation numbers to understate inflation?
I Bonds create an excellent, very safe secondary emergency fund. After 5 years, with no penalty, you can redeem any amount you want to pay for “emergencies,” or things you need like home repairs or travel. So then the question is: How big of primary and secondary emergency funds do you need? At the age of 34, I feel you can safely be investing 75% or 80% of your asset allocation in low-cost stock ETFs, U.S. and international. But I am not a financial adviser. I suggest reading this book by my friend Allan Roth: “How a Second Grader Beats Wall Street.” It provides a simple and entertaining guide to sensible investing.
David, I have some Roth IRA money becoming available today or tomorrow that I was thinking about using to buy a 5.2% 5-year call protected brokered CD in my Fidelity account. Do you think this 5-year TIPS would be a smarter choice? Thanks!
This is always a toss-up: real yield versus nominal yield. With that CD, you are looking at an inflation breakeven rate of about 2.65%, which might be about right over the next 5 years. The CD interest won’t be reinvested with a brokered CD (I assume) and you will have to pay state income tax on the interest, if that applies. My wife would buy the CD and I would buy the TIPS, personal choice.
This auction is going to have very strong demand.
If I didn’t have to buy these Tips at auction at the Treasury website, I might have wanted to do it. I wish Treasury would allow the brokerage firms like Fidelity to participate in the auctions like they do with treasuries.
They do. Just check your brokerage. Exactly the same terms, with no commission. Probably a $1,000 minimum purchase.
Thanks for the tip (pun intended). If I buy these from a taxable account, will I receive sufficient income from the semi-annual interest payments to pay the taxes.
Lou, the coupon rate should cover the taxes for the inflation accruals.
Look for menu item ‘Fixed Income, Bonds & CDs’, then ‘New issue’ and you can select TIPS in the drop down box below that. $1,000 is the minimum. It says orders close at 10:00am on the auction date, but has a disclaimer that Fidelity reserves the right to close sooner. I’d get in at least the day before to be sure.
As far as yields peaking, the USA is still running two trillion dollar deficits. It’s hard to see inflation and yields going down even if the war ends and oil returns to $60-$80 a barrel.
I have had some money in a stock bond income fund that has gone nowhere for years. I am selling about 20% of the fund and using the money to buy this 5 year TIPS since it fits perfectly into a needy spot in my ladder. Maybe I am right. Maybe I am just another fool. It’s a jungle out there. Good luck to all.
FWIW, Earlier I purchased some of the 10 year TIPS that had a yield of a bit more than 2.4%. I thought I was a real winner. Now we have 5 year TIPS at near 2.5%. Not bad. I think my following TIPS news and people like Mr. Enna has helped me get on board when at the right times. Thanks.
Uncle Sam paying over a Trillion dollars this year just in interest with our tax money is obscene. They should all be fired.
The elected ones fired at least.
Excellent info, thank you David! It makes me wonder…
I have cash to deploy for my 5 year TIPS allocation. I tend to go lump sum and “bird in the hand”, but with such volatility right now, my current plan is to spend half at this auction and half at the reissue in December.
With the great points and discussion here, I wonder if it’s better to adjust that strategy back to lump sum or something else? I’d love to hear opinions, thank you all!
Alan Roth has been known to promote a 50% solution to these type quandaries.
FWIW, in the near past, I have split my lump sum in half. Half went to the TIPS and half to the nominal bond of the same duration. I did this because my history of predicting interest rates proves I am not good at predictions. However, this current 5 year real return seems to be good enough to skip the splitting this one time.
At this point, I am only looking to fill TIPS ladder spots in 2037 to 2039. For those, I really like to buy at the January auction and then I know each year the TIPS will mature and I will have the cash (or close to the amount) to withdraw my RMDs in those years. I can then sit on the cash until I want to make the withdrawal. So I have a special logic in buying at the January auction.
This is what I do
Thanks for the food for thought, I appreciate it! I’m 14 years from retirement so I’m just looking to fill my 5 Year TIPS allocation, I think I’ll be fine either way.
FWIW, you don’t have to wait for the reissue to purchase your second half. You can buy more anytime the bond market is open. If real yields jump again in November — buy — don’t wait until December. Since buying half now and half later is a kind of market timing, then you might as well actively time the market.
You could always buy half now, watch real yields until the reissue, and either buy along the way or buy at the reissue.
Thanks for always previewing these auctions. I purchased the 5-Yr. TIPS issued this year on 4-30-26, CUSIP 91282CQP9, with a 1.25% coupon, and now I’m wondering if I should sell that, and reinvest the proceeds into this auction with the much higher coupon? How would the math work on that? Thoughts anyone?
When you sell a TIPS on the secondary market, the buyer will be getting a real yield at current market, well above 1.25%. That means you will be selling at a discount, about 5.5%. The key here will be if you can take a capital loss on that sale. (I am not a tax expert and I have never sold a TIPS.) If so, that might make a sale and repurchase make sense. Otherwise, just keep holding.
You will be selling at a price that equates to about the real yield to maturity of what you will be buying. Largely a wash, though you are extending the maturity by six months.
Even though it will look different on a spreadsheet or your brokerage statement, you will simply be earning the return of your April purchase by making such an exchange.
The only reasons to do this are because you want the higher annual cash payments of the newer bond, you have a bond with lots of inflation built in and you want to reset it to eliminate deflation risk (not your case), or to take a tax loss if held in a taxable account. A tax loss is not a free lunch though because while both the old bond and the new bond earn the same inflation rate adjustments so trigger the same tax on phantom income, the higher coupon on the new bond means higher taxes on the cash interest. So save this year, pay more for the next five.
There will be some minor differences, but they will be minor.
There was an article this week in Barrons about why the market hasn’t yet offered an all-in-one TIPS ladder in ETF form. Thoughts? How big would a market be for something like that? Would a product like that obsolete the current TIPS ETF’s?
That was by Alan Roth, I believe. He is pushing this idea hard and it would be an excellent advancement. The fund companies could promote this well, I think.
https://www.barrons.com/advisor/articles/tips-ladder-etf-retirement-income-54afa420?mod=searchresults_article&pos=1
Yes.
Brian is this what you’re looking for:
https://www.ishares.com/us/products/340132/ishares-ibonds-1-5-year-tips-ladder-etf
Thanks John. Very intriguing.
just curious, would you consider using the iShares fixed maturity Tip ETFs to build your ladder (for example 3 years to 10 years) instead of buying the Tips on secondary market?
I would rather own the individual TIPS, especially a new one like this with a high coupon rate. But the iShares fixed-maturity TIPS ETFs are a good substitute. I wrote about those here: https://tipswatch.com/2026/05/24/ishares-target-date-tips-etfs-are-growing-in-appeal-but-i-have-cautions/
My quandary: I learned about TIPS (and tipsladder.com) last year and considered converting my IRA bond ETF position, but dithered. If I were to go ahead now I’d be taking a significant haircut, so I wonder about waiting out the current downturn…
I did this exact move in 2023 when real yields were nearly as high. If these are bond ETFs, an upturn in those will probably mean lower real yields on TIPS. Year to date, the total bond fund ETF (BND) has total return of -1.45%; not disastrous. It is helped by the current yield of about 5%.
Thank you for this preview. There’s no way to know what inflation will be over the next five years, but it helps me to see what the nominal return would be for this TIPS offering at various inflation rates assuming the 2.52% number, so I asked ChatGPT to generate that from 0%-5% inflation.
At 0.0% inflation, the exact nominal yield is 2.52%.
At 0.5% inflation, the exact nominal yield is 3.03%.
At 1.0% inflation, the exact nominal yield is 3.55%.
At 1.5% inflation, the exact nominal yield is 4.06%.
At 2.0% inflation, the exact nominal yield is 4.57%.
At 2.5% inflation, the exact nominal yield is 5.08%.
At 3.0% inflation, the exact nominal yield is 5.60%.
At 3.5% inflation, the exact nominal yield is 6.11%.
At 4.0% inflation, the exact nominal yield is 6.62%.
At 4.5% inflation, the exact nominal yield is 7.13%.
At 5.0% inflation, the exact nominal yield is 7.65%.
My guess is we will see inflation continue in the 2.5% to 3.5% range through the next 5 years. If the economy keeps booming, maybe higher. If we hit a recession, probably lower. Inflation predictions are just guesses, though.
I am thinking that real yields may have peaked, so this could be an attractive auction not only because the high YTM, but you could enjoy some capital gains if you need to sell before maturity.
We’ve just seen an amazing run-up in real yields, so I could see at least a pause coming. Eventually, investors should see how attractive these yields are and pile in, which would cause yields to fall. (And then pair that with a stock market correction? … which never seems to come.)