
By David Enna, Tipswatch.com
Talk about a contrary opinion: Real yields for Treasury Inflation-Protected Securities have risen to their highest levels in nearly 20 years and still we can easily find negative opinions on this unique investment.
The latest opposing view is from Ed Al-Hussainy, fixed-income portfolio manager for Columbia Threadneedle Investments. He was quoted in a recent Unhedged newsletter posted by the Financial Times:
The quip is ‘TIPS are for losers’ and it’s very hard to find evidence to challenge that. Often investors come to the TIPS market thinking it will protect them from inflation — that’s the intuitive power of TIPS. What can often happen [is that] you can get punished even more in the TIPS market than the nominal Treasury market because it’s so small and the investor base for that market is so thin relative to nominal Treasuries.
The newsletter’s author, Hakyung Kim, raised the obvious counterpoint, “But can’t these risks be avoided by holding to maturity?” Then:
Al-Hussainy notes, “everyone thinks they’re going to hold Treasuries until maturity, whether it’s TIPS or nominals”. Nobody plans to need liquidity all of a sudden, but sometimes they do. TIPS are just about 7% of the total Treasury market. … The lack of liquidity in the TIPS market compared to Treasuries creates wide bid-ask spreads when volatility goes haywire, making them look more like corporate bonds than a safe-haven government security, notes Brij Khurana of Wellington Management.
Kim closes with this:
If you’re confident inflation is set to run hot for years and are certain you can hold until maturity, TIPS might be a good bet. Otherwise, just buy plain old Treasuries.
The big picture
Kim’s newsletter article was actually quite positive about TIPS, pointing out the high real yields offered across the yield curve:
- 5-year, real yield of 2.68%, up 104 basis points since June 1.
- 10-year, real yield of 2.91%, up 84 basis points.
- 20-year, real yield of 3.17%, up 69 basis points.
- 30-year, real yield of 3.32%, up 61 basis points.
She wrote:
If held to maturity, those are compelling yields, especially if you think inflation is set to rise further.
And there is the key point. The best way to invest in TIPS, and the only way I participate in this market, is to buy with a firm intention to hold to maturity. This is the strategy used by the large community of TIPS ladder-builders, creating a packaged investment that can deliver a predictable and safe inflation-adjusted dollar amount in the future (plus collect a coupon rate along the way.)
Invest $40,000 in a TIPS maturing in 2036, and at maturity you will get the inflation-adjusted equivalent of $40,000 at maturity. Plus an annual coupon payment of 2.375%, based on the most recent 10-year auction. The coupon pay-out will rise along with official U.S. inflation until maturity.
The latest update from Tipsladder.com says: “At current yields (as of 2026-10-09) a 30 year TIPS ladder can provide a Safe Withdrawal Rate of 5.1%, and a real yield of 3.2%.” This is highly attractive, and has been nearly impossible to attain for last 20 years. (Emphasis on safe.)
Kim then goes on to quote a highly positive Substack article written by respected economist Laurence Kotlikoff, with the title: “TIPS Are Screaming — Buy Me!” Kotlikoff writes:
The last half dozen years have witnessed a 30 percent inflation-generated effective default on nominal federal debt. Yet purchasers of nominal long-term Treasuries aren’t, it seems, worried about inflation long-term. …
To me, TIPS dominate nominal Treasuries. They have the same default risk, roughly the same tax treatment, and, given survey data, the same expected real return. But TIPS come with seemingly free insurance against a massive risk — another major bout of inflation. …
A strategy of buying and holding, through maturity, a portfolio of TIPS — building a TIPS ladder — appears the safest way to secure one’s retirement.
Aligned with this theme, Morningstar just posted an instructive article: “How to provide guaranteed retirement income while paying no commissions.” Among the points:
Unscrupulous financial planners want us to believe we can’t, by ourselves, secure our financial security for retirement – and therefore we need them to do it for us. That’s just not true, especially now, given the recent surge in TIPS yields.
The author, Mark Hulbert, provides a suggested way to build a TIPS ladder, and it makes sense to me:
The solution is to allocate only a portion of your retirement assets to a 30-year TIPS ladder and invest the remainder in a broad stock-market index fund that you don’t touch for 30 years. This approach extends the life of your guaranteed income to over 40 years.
TIPS haven’t been ‘losers’
I am not a fan of TIPS ETFs and mutual funds, but I can understand that for some investors this is the easiest solution to investing in TIPS. I do like the iShares iBond Target Date TIPS ETFs — which I wrote about here — because these ETFs have a specific maturity date and can be compared to TIPS held to maturity. The only complication is that for these ETFs, inflation accruals are paid out as current income and must be reinvested at a similar real yield.
But even traditional TIPS ETFs — rolling over a set series of maturities — have done “reasonably well” in recent years versus the total U.S. bond market. In this case, I want to highlight my favorite TIPS ETF: Vanguard’s Short-Term TIPS, ticker VTIP. This fund invests in TIPS maturing in less than five years, so the volatility is much lower than traditional broad-spectrum TIPS funds.
VTIP tends to track inflation better than the wider TIPS funds. It has less downside risk, and of course, less upside potential if real yields begin falling.
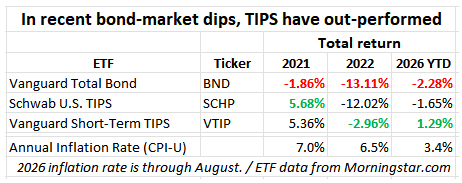
In all cases in these examples, the total U.S. bond market was the loser, falling a massive 13.1% in 2022, as inflation was rising 6.5%. VTIP was the best performer in this group, holding its loss to 2.96% in that year. Painful versus inflation, but not devastating. VTIP continues to out-perform in 2026.
In contrast, TIPS held to maturity gained 7.0% in inflation accruals in 2021, 6.5% in 2022 and 3.4% for the partial year of 2026. Yes, the market value of those TIPS declined, but remember this: At maturity, there is no such thing as “market value.” The investor gets:
Par value x inflation index + one final coupon payment.
For example, look at the 10-year TIPS that matured in July 2026. It was auctioned with a real yield to maturity of just 0.045%, and yet CUSIP 912828S50 outperformed a 10-year Treasury note purchased in July 2016 by a wide margin: An annual bonus of 1.86%. That is significant. The reason was unexpectedly high inflation over the ensuing 10 years. Read about this here.
Also: Check my ‘Tips Vs. Nominals’ page for historical data.
Conclusion
TIPS held to maturity will out-perform a similar-term nominal Treasury if inflation runs higher than expected. That expectation is currently around 2.35%, fairly high by historical standards but perfectly reasonable in 2026’s economic environment.
I am not against investing in nominal Treasurys — today’s yields cresting 5% are highly attractive. But I would tend to go nominal for five years or less, and use TIPS to do the heavy lifting of inflation protection.
Coming Wednesday …
The most important inflation report of the year, for September 2026, will be released at 8:30 am ET. This report will set in stone the I Bond’s new variable rate, to be reset on November 1, and also determine the Social Security COLA for benefits paid in 2027. I will be posting Wednesday morning, possibly in a breaking news format that will update over a couple hours. Visit often!
• Now is an ideal time to build a TIPS ladder
• Confused by TIPS? Read my Q&A on TIPS
• TIPS in depth: Understand the language
• TIPS on the secondary market: Things to consider
• TIPS investor: Don’t over-think the threat of deflation
• Upcoming schedule of TIPS auctions
—————————
Donate? This site is free and I hope to keep it that way. Some readers have suggested having a way to contribute. I welcome donations, any amount. And FYI, ads on this site pay for about one visit to Costco.
—————————
Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).
Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.
David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.


Please stop using generative AI images for your posts. Generative AI devalues the work of human artists and allows corporations to exploit human effort without paying for it.
I will continue to use AI images (from Perchance.org, which is open-source and free) and some financial data collected by Claude and Chat GPT. But I will ALWAYS tell you the source. My writing and analysis appears all over AI compilers, sometimes with links but those links probably don’t result in page views. I get nothing for that research analysis and I can’t do a thing about that.
He will have to double the subscription fee.
David and community,
I just want to clarify that YTM does NOT require reinvestment of coupons at the same rate. Realized Compound Yield is the financial term for reinvesting at the same rate. This difference has been ignored in academic circles for decades until zero-coupon and STRIPS bonds came along. Textbooks are slow to catch up but that is where are today.
This is true. However, with a TIPS purchase, the real yield does depend on the inflation accruals being added to principal and the coupon payment rising over time with inflation. That’s the inflation factor, and it works without the coupon payment being reinvested.
Some older investors may remember 2013 “Taper Tantrum” when the Vanguard intermediate‑duration TIPS ETF got hammered with a ~20–25% price decline. That woke a lot of people up when their real yield was destroyed in a short period of time.
The thing is you hold your bond allocation to supply cash in “bad” times, which by the way you don’t know when they can come. Unless you are super risk adverse you could expect to spend most of your bond allocation in a 2-5 year downturn. Having longer term TIPS ladders for most of this may be a problem in this type of upset, which is accompanied by an equity drop as well. If your bond ladders are set to turn over in 5 years, meaning short term ladder (3-5 yr) then not so much a problem. ETFs, a little more of a problem.
I am not a fan of long TIPS ladders because most people can’t anticipate the future and also might puke them up rather than hold to maturity, as longer maturities are volatile.
I am retired and have a ten year ladder of individual TIPS that starts next year. I am considering extending the ladder another ten or eleven years, but with a twist. Significantly smaller, but sufficient, dollar amounts for the extension. Statistically both of us have over 90% odds of living for the full period.
I was a bit surprised when I modeled this and realized how little it cost to effectively inflation protect the additional ten years using the smaller amounts. The ability to do so at roughly 3% real yields is a plus (though the volatility and the potential deflation risk are minor concerns).
I have not pulled the trigger yet, and am not in a rush to fill the slots even when I do, but doing so clearly isolates the portion of our assets that can fund 20+ years of more than our current lifestyle. This has both psychological benefits, and is easily understood by spouse, even if TIPS themselves are complicated – just spend the maturities when they happen.
Your thoughts?
Seems fine if it fits your needs. In my case, I am targeting expected RMDs for each year to age 90, only for my traditional IRA. I think it will work, or be close to working after inflation adjustments and declining balances over time.
One has to have a reason to put money in harms way when you don’t have to. I got my biggest Ibonds coming up for redemption soon am then Im out.
Back in 2021 I wrote a look back to 2013, which was another of the bad years for bond funds and broad-spectrum TIPS funds. VTIP’s total return was -1.51%, versus -8.10% for SCHP and -2.10% for BND. The U.S. inflation rate in 2013 was only 1.5%, which made it a bad year for TIPS — rising yields and meek inflation. Here is the article: https://tipswatch.com/2021/07/06/lets-take-a-deep-dive-look-at-my-three-favorite-bond-funds-vtip-schp-and-bnd/
I would load the boat if that situation repeated.
Just looked it up: for 2013 VIPSX – just shy of -9% total return. Meaning it lagged “flat to inflation” by 10.5%.
Hey Dave we discussed Income Rider Annuity years ago. I turned lifetime income on a few yrs ago. The guaranteed rider payout was exactly like the projections claimed by insurance company up front. Feelings alot better when the funds are flowing my way.
Yes, income riders are essentially an expensive way to buy a deferred annuity. The problem is most people like to put them inside an IRA, which defeats the tax incentive that the annuity usually supplies. A couple years ago I found a product (Calamos ETF) that allows you to convert your cash to LTCG which tracks the SPY with a cap much like the index annuity. The downside is clamped at essentially the expense ratio of .7% which is about .3% less than income rider annuities and has an annual reset which protects your gains very similar to index annuity products. Found it very useful in a taxable account where you don’t need to spend the cash but you want to keep some handy.
By the way I just cashed out our ibond accounts. Taking the 12% ordinary income hit now, in favor of zero LTCG in the future at returns that will likely beat any TIPs or ibonds and will step up on death like any Stock or fund. Something ibonds won’t do.
One really has to buy whats available. Incomer riders is insurance not an investment, so had nothing to do with taxes, etc but security. This was IRA money so had to take RMDs out anyway. Yes I wasted all that money on home and auto insurance all those years for something that did not happen. The best current product I saw has a starting 20% payout on premium after 10yrs.guarenteed. I was able to take extra risk with my basic income covered. Like that 6 figure gold speculation I closed out first of the year. Tax man gonna like me.
Dave, is the Calamos ETF CPSL?
Basically the ETF holds ETFs which hold put and call options on the S&P 500 to create a capped upside, limited downside return.
This is analgous but different than BOXX, which uses a box spread to yield short term t-bill rates while using the ETF exchange mechanism to avoid distributions and thus deferring ordinary income and converting it into LTCG if you hold for over 12 months. (Undistributed income increases net asset value.)
Treasury/IRS are moving slowly, but surely on certain tax aware fund schemes. Recently issued Treasury Notice 2026-62 (and a Revenue Ruling) putting the screws on one approach and alerting others they are looking.
Unsure how CPSL fits in that but will take a look.
For others considering this, it is only 0% LTCG if you have taxable income below the threshold, which is $49,450/$98,900 (single/married filing jointly). It only gets step up in basis if you hold until death. Good for those with terminal illnesses, not so good otherwise. Gives hold to maturity a new meaning!
Isnt LTCG just the same as ROC with one more letter?
Risk disclosure sez, ” no assurance”, hardly a substitute for gov securities. You cant afford a mistake when retired.
There is some truth to the fact that you can’t afford a mistake in retirement, but to be honest the “later” you make the mistake, the “less” it will affect you. Compounding is funny that way. I had a $10k mistake that went to zero in my 20’s which literally cost me probably close to $1m at a 10% annualized rate. Some are under the illusion they have time to “recover” from a mistake, but that is really ridiculous if you ask me. Sure, you learn from early mistakes and hopefully don’t make them again later. Every time an investment is sold, or goes to zero that “lesson” is over, you can’t make up for it by taking on more or less risk. There is no recovering, the future will either be kind or it won’t, but has nothing to do with your past “lessons.”
You cant make big mistakes when old unless one has guaranteed sources of income and long term care. Never outlive your money. I recently used up all my carryover loses from years in the market, 22 cents on the dollar is better than nothing that went down the drain.
And if you hadn’t made all those earlier little mistakes that created those loses you would now have compounded your retirement into a much better outcome, where the same sort of mistakes wouldn’t hurt the outcome at all.
I should of invested in a simple index fund, but that would not have been any fun. Thrill of victory and agony of defeat. I started to make money when I made more then losing and never lose more then I can make back in a year. Turns out a financial education is not free, imagine that and did not lose more than a PHD would of cost me or paying a money manager, who I did from time to time.
Dave, I ran by the spouse, if we die tomorrow we got enough money, she didnt go for it.
Looked at the Seeking Alpha you mentioned about buying. Checked the Calamos web page. They have a chart that looks like a closed end fund type record where some of these traded below their NAV about a third of the year time frame. Why not just look to buy at a discount rather then on the opening of the rollover. (I really hate to be rushed to buy anything.) Of course if in a raging bull market trading below NAV probably aint gonna happen.
gg,
This is my just released article:
Calamos Buffered ETFs As A Zero-Tax-Drag Investment | Seeking Alpha
Yes, the NAV tracks around both sides of the price chart, but that is not the issue. The issue is your potential loss has nothing to do with NAV or price directly. It is controlled by what is called the reference price which is established on the day after the reset date. So, say you see a price that is a few pennies below the NAV in December on a June ETF and you buy it when the June ETF is up 8% in December. You have just bought into a potential 8% loss with your money as the 100% downside protection is fixed to the opening reference price that has now run up 8%. There is rarely a reason to ever buy these and put yourself in a position to lose money if the market turns down.
Your link behind a paywall. Calamus got lots of info what the starting price is so buy below and one might even make up for the expenses. The expiring Nov CPSN contract had 11 times to buy below the $26.71 starting price according to their download. But Im thinking a big market pullback? Could I play a recovery risk free buying below the issue price? https://www.calamos.com/funds/etf/calamos-sp-500-structured-alt-protection-etf-november-cpsn/#_literature
gg,
You won’t find out what that new reference price is until Mon Nov 2nd. Probably around $28.41, but yes looking at the trend chart of CPSN shows there was a large enough pullback in March of this year for it to dip slightly below the ref price. If you only get it at the reference price you still can lose the expense ratio of .69%. So riskless is at a point .69% below the reference price, which is very hard to do. I suppose anything is possible with a limit order, but I have not seen it trade that far below the reference price.
CPSL is just an ETF ladder of all 12 months. I prefer to put my money in the actual single month outcome periods which last 365 days and then reset the baseling. I am working on an article that covers how they have done over the last two years, which is somewhere between 5%-6%. My previous article that explains how these work is here:
CPSJ ETF: Buffered ETFs, Limitations And Cautions (NYSEARCA:CPSJ) | Seeking Alpha
This became very low priority once I saw that the monthly ETFs are tiny ($30 million in assets), and *at a glance* the cap appears to drift down (initial cap was higher than current caps on all), and hitting the roughly 6% cap appears to require 12% plus SPY returns.
So yes, downside protection in a decline, but pretty limited upside. Outperform TIPS with 2.25% or greater real yields? That is pretty uncertain and even one year of no return from the ETFs will offset a number of years of 6% returns while TIPS seem likely to generate 5% +/-.
But I have not read Dave’s recent article cuz behind a login and maybe a paywall too.
Rocky,
Most of what you say is correct, there is no guarantee they will generate larger returns than TIPs, but TIPs, depending on duration can definitely lose money if not held to maturity. I don’t hold them for return. I hold them to convert ordinary income to the tax deferral of LTCG at my own timing, just like last year when I paid zero tax on a sale. It’s not for every situation, but the comment you need returns far above the cap to get the cap is wrong. If the cap is hit at the end of the outcome period you will get the net gain, which is gross minus .69% ER. In between the start and the end of the outcome period there is no guarantee as the price is set by the market, but the options used are pretty predictable. If the SPY is above the cap you should be able to sell for the cap. If you want to email me, you can at financialdavid@gmail.com
Mr. Enna: Thank you for all your work for individual investors in inflation-protected securities. Question about iBonds held at Treasury.gov. Mine are in the name of my revocable trust (which has my social security number). Is it your understanding that (A) if my successor trustee transacts before my death (but he is functioning as successor trustee due to my e.g. disability), my social security number will work; but (B) once I die, Treasury.gov account is frozen until the trust obtains an EIN number for my estate at which time the account will be unfrozen & he can transact? TIA for any assistance you can provide.
Not David here, but to answer your questions. (A) Your successor trustee would have to sign into your trust account with your ID.ME login. Once there he could act just like you, (probably not legal). (B) You have that correct. He would be sending in the TD Form 5446, completing parts A, D-4 and E, and providing a copy of the trust, any letters of appointment, and death certificate. You might download and read Form 5446 if you haven’t already.
Thank you for your response. I appreciate it.
I got to believe now that once that SS number is reported deceased anywhere accounts are dead. Sounds like alot of phone calls and snail mail. This process for trusts isnt just TD, the process for any asset named in the trust like your home.
Here’s an article that is on the topic of a TIPS ladder by Allan Roth. 4 Practical Uses of TIPS in the portfolio. https://www.advisorperspectives.com/articles/2026/10/05/4-practical-uses-tips-in-portfolio
Alan Roth was my one-time financial advisor in 2019. Hourly fee and well worth it. Then in 2023 he became a huge inspiration for TIPS ladder-builders.
I’m impressed. He is amazing.
I recall, he didn’t like you owning TIPs in a taxable account. He seems to have changed his tune (somewhat) about that.
Yes, his California clients changed his view. Roth’s asset location theory stresses holding most fixed income in tax-deferred accounts
Really looks like the I-Bond fixed rate is going to creep up to 1.4, which I would have thought impossible as recently as a month ago.
At this point, a fixed rate of at least 1.3% looks rock solid, assuming the Treasury doesn’t abandon practices of the last decade. If 5-year real yields hold at current levels for 13 more market days, we do get to 1.4%. I will update my projection later in October.
My partner and I often split our individual and gift-purchases and different times of year to hedge our bets. She bought her individual and gift bonds in April. I will now do the same in November. Sorry to miss out on the extra 0.4% (or 0.5%) fixed rate on those April bonds, although we can always gift each other more in 2027 before the May reset, depending on where it looks like the new fixed rate will reset based on the Treasury’s 0.65 x 5-year real yield formula. Thank you for all you do, David. Looking forward to your final projection post.
The 5 year TIPS is coming up too. Busy month!
What’s “interesting” to think about is May 2027.
So much at a macro level would need to change to see a reversal in the current yield trends. I don’t realistically see May 2027 below 1.3%; probably not below 1.4%.
* 1.5 – 1.6% I-Bond fixed in May 2027 seems likely.
* 1.7% is a real possibility.
* 1.8% is what would be remote, but… not impossible.
We’re living in interesting times.
Chester, so much can occur between now and May 2027 that it’s impossible to say what will happen with inflation and interest rates. We have the Midterms a few weeks from now. We have extreme unprecedented tariffs that can remain in place or be lifted entirely. We have a war in Iran destabilizing the Middle East and a war in Ukraine that are disrupting the oil market and gas prices that can drag on or end entirely. We have a a deficit and debt which could impact our economy or remain mostly a non-issue in the short term. We have a roaring AI-driven stock market (bubble perhaps) that can remain hot or can Peter out. We have a Federal Reserve that can act or sit on the sidelines. Your scenario is equally as plausible as the one where the war ends, tariffs subside, and inflarion and interest rates come down substantially in that timeframe. Interesting indeed. Scary too.
Only bad things happen instantly. The Ukraine war started, 2022
Agreed.
Generally I-Bond fixed rates have moved 50 basis points over 6 months only a few times since their introduction.
This appears to be one of those times.
2022-2023 was another of those recent times.
The wild oscillations during the GFC though were… really something. 1.20% -> 0.00% -> 0.70% -> 0.10%
Apologies for the typos for some reason the edit option was not available this morning.
In commentary from Vanguard I have read, they make the argument that there are downsides to being a DIY’er who holds a bond to maturity, as opposed to buying a bond mutual fund. The argument is of course self- serving but it goes like this. There is an opportunity cost to buying bonds on your own and holding to maturity. You miss out on the professional management that a bond mutual fund has. When yields rise, you miss out on buying newer bonds that pay more. The fund manager can tweak the portfolio by including issues that pay a higher yield. So that at the end of the day there is no advantage and perhaps a disadvantage to holding to maturity in a rising yield environment. I suspect that sometimes this is true. However we have been in a long term bond bear market, especially punishing for nominal bonds which started out prior to 2022 paying very little. The 10 year returns on I bonds and TIPS have been superior to nominal bonds. I think somebody else here has said that cash is king– that has certainly been true for 2026 and not what had been predicted.
In the case of TIPS, there are only 44 bonds existing on the market at any time. So the choices are limited, and even more for a fund like VTIP that holds TIPS maturing in less than 5 years. There are only 24 of those. VTIP is not really actively managed, it just owns TIPS maturing in less than 5 years, more or less. And that is why the expense ratio is just 0.03%.
What interest rates wise and any of my tips go down, especially the wants to sit outside of my ladder. For example I have a 2047 chip, and that money used to be and a 2045 tip, interest rates went up I booked the loss on the 2045 and redeployed it in the 2047. I I suppose a professional money manager would have done the same thing, but I get the immediate loss, tax loss or I can make the judgment to just hold it until maturity if I don’t need to book the loss
I should add, I’m not arguing against your professional Management thesis, just adding one more bit of perspective.
We just had a philosophical conversation about this very topic at my latest Bogleheads chapter meet-up. For me, I like holding I-Bonds as my bond allocation. Admittedly, some of this is due to recency bias after 2022, although I still prefer I-Bonds because they are as risk-free as one can get and I prefer to keep risk in equity and out of bonds.
But what’s most important is what works for you and helps you stay the course. And of course there’s nothing wrong with holding bond diversity. Inflation-protected securities and a bond fund.
But you surender the safeguard of maturity with funds.
On the issue of TIPS versus Nominal Treauries bonds, there is no law against owning both. If I had some dry powder for my bond allocation , I would seriously consider buying a 5 year nominal at about 5% and a 5 year TIPS at about 2.6%. There is no reason it has to be all one or all of the other.
Great article. Touches on all points I have been mulling over in this 3%+ real yield world. However, I have a few counterpoints 🙂
1. Short Term TIPS offer the best protection to unexpected inflation (commodities in the form of managed futures offer better inflation protection only when their curves are backwardated – “Commodities for the long run” – Bhardwaj, Gorton & Rouwenhorst, 2018 and “The Tactical and Strategic Value of Commodity Futures” Claude B. Erb and Campbell R. Harvey , 2005). Vanguard had released a paper on short term TIPS when they rolled out VTIP – while I can’t find it anymore, it is part of their annual retirement research ever since.
This has important implication for I-Bonds : With 0 duration are in many ways superior to VTIP. Infact I compared the total return of I-Bonds vs VTIP in an IRA (with dividends reinvested) and from 2012-22 I bonds beat VTIP every period. Since 2023 the real yields have been meaningfully higher for TIPS. In the short term I Bonds may lag but over long periods like 20-30 years, I bonds will beat VTIP (and 5 year TIP) most of the time. Infact since ’98 most I bonds have beaten VIPSX and VBTLX but that’s another matter!)
2. On the flip side over long periods (statisticians many not consider 30 years is long enough) expected inflation ≃ realized inflation so 30 year TIPS should in theory with a high probability have the same total return as the nominal 30 year. The long bond could be a lot more volatile along the way and could also be subject higher sequence of return risk.
TIPS ladder however has the benefit of enhanced safe withdrawl rate
Except the problem with IBonds is the the purchase limit. So its a young mans game. Tips are unlimited purchase, ibonds not so much. So the comparison is invalid.
True, but Ibonds are designed for the average consumers where that limit isn’t much of a limit. Joe Six Pack isn’t likely to be putting anything close to 10k (20k if married) aside in a year.
also, there are work arounds to get more into Ibonds in a year (gift boxes, trusts, businesses, etc) Still won’t get the numbers up to “rich man’s” level but it can get it to several multiples of the 10k limit.
I’m a uk resident investor buying linkers for 20 year retirement ladder drawdown rate is 6% overpriced equities can’t get near that with sequence risk and worse. Index linked sovereigns are a contact and default in UK or USA unheard of.
sounds like its similar in concept to the US Ibond but without the purchase limit (but with eligibility limits on access – you need to be a member of the DMO’s Approved Group of Investors according to google, not sure what that entails).
David, thanks for all you do on this site, always very informative. Seems to me one of the cornerstones of a TIPS ladder is holding individual issues to maturity in a tax qualified account. If a holder dies with the ladder extending past the ten year period to empty a qualified IRA, doesn’t this force that portion of the ladder into the beneficiaries non-qualified account (with adverse tax effects) or alternatively, a liquidation before maturity? Is there a work-around to that? ( Other than not dying, which would be the preferred alternative).
Yes, if a TIPS is in a retirement account and you die, the beneficiary can always transfer the TIPS “in-kind” to their taxable account if they need to distribute it.
Excellent point, for those who can hold to maturity. The challenge is not only to those who have an emergency and need to raise money quickly but also to those who need income to live on. They are also exposed to the vagaries of the market with the potential of having to raise money by selling at a time when their value has dropped significantly since purchase.
This is why I do not recommend holding anywhere near 100% of your portfolio in TIPS. You need the balance of low-cost equity funds, some nominal Treasurys, and plenty of cash to deal with a downturn.
If I’m investing in an IRA, and I don’t have a large amount to invest and I’m basically working with annual contributions, do you have a preference for the ishares ETFs or just buying as many bonds as I can when I have the cash? Thanks!
Possible disadvantages of the ETF: my understanding is the ishares TIPS fixed maturity ETFs, even if held to maturity, take some interest rate risk on reinvesting the dividends (dividends consist of the coupons plus yearly inflation adjustments), if I understand all this correctly. If interest rates and real yields fall after the ETF purchase then the reinvested quarterly/yearly dividends will be purchasing new ETFs with the underlying TIPS bonds’ real yield being the new market rate (lower market real yield than at the time of ETF purchase). Therefore the compounded total return could be significantly less than a TIPS bond purchased at the time of the ETF. Furthermore, the ETF investors will be buying and selling, so there could be lots of churn in the ETF creation/destruction process, selling and buying new underlying TIPS bonds in the fund. For example, say interest rates, inflation, and real yields fall, and 30% of the ETF shareowners sell, and later there are 50% more ETF purchases. The new purchases will be underlying TIPS bonds on the after-market with possibly much lower real yields. If enough churn happens I think the ETF real yield and total return will be less than expected at purchase time.
Market timing: if you can buy TIPS bonds at a time of historic real yield highs then I’d guess it’s very possible that may have a higher total return than the ETF. On the other hand, if real yields are very low or negative (2021) then the ETF may be able to adjust upward if real yields rise during your holding time.
Thanks for the insightful comment. But if you buy the actual TIPS, what do you do with the coupon payments? Because the YTM assumes you’re reinvesting everything at the same rate. And if you get $179.42 in interest, for example, what do you do other than keep it in a money market?
Response to “But if you buy the actual TIPS, what do you do with the coupon payments?”
In an IRA, all other things being equal (they usually aren’t), I prefer the lowest coupon. Because yeah, reinvesting the coupon is a nuisance, and not easy to get a good real yield.
For small coupon amounts I might accumulate in VTIP, and periodically buy a new TIPS bond if I can. Or just reinvest the coupon in the fixed maturity ETF (bit if a hassle, I agree).
If the YTM assumes reinvestment at the same real yield, then that doesn’t fit the real world. Perhaps you could argue that’s an advantage of the fixed maturity ETF, but if my understanding above is true, if real yields fall significantly after the ETF purchase that may dwarf the problem of reinvesting coupons (if you can somehow figure out how to reinvest coupons).
The ETF can’t be beat for convenience and simplicity.
JohnW, yes, reinvestment is a problem with the iShares ETFs, which are lightly traded. (I am not sure that Vanguard allows reinvestments, but other brokerages might.) The fact that future TIPS will be added (for a total of four for each ETF) could end up working for or against the investor.
Yes, I would prefer to simply own the individual TIPS.
I reinvest my TIP interest payments in VTIP. I also have auto-reinvestment of dividends set for VTIP. Not a perfect match, but close. This came up several times in comments below.
Dazzling, I would prefer to own the individual TIPS, if possible. The iShares ETFs are a good option for people who don’t want to deal with the complexity of TIPS. I Bonds are another option.
What do you all think about the effect of taxes when I Bonds mature or TIPS held in traditional IRAs are subject to RMDs? I’ve been buying I bonds since 2000 and individual TIPS recently, but I’m concerned that inflation protection will be much diminished by taxes. Thoughts?
Taxes will limit your returns for I Bonds unless they are used for purposes like education spending where they will avoid the tax. If inflation averages 2.5% through the future, a 0.5% to 0.6% fixed rate will cover the tax bill for most investors in moderate brackets. Similar for TIPS, and for all investments in a taxable or tax-deferred accounts. TIPS in a Roth avoid the issue.
2030 is the reconning year coming 4 more years for 2000ish bonds. Those ibonds maturing first will have the highest gains cuz the fixed was so high and they compounded. We can only hope that the tax tables get adj for inflation, the thing we were trying to outrun. Remember they dont send out 1099s.
The business of investing is very unsavory. Even if the people who work in these institutions show off their Ivy League credentials. Pay attention to academic research and folks like David who bring useful information to us without bias.
At maturity you receive a return of the sum of “inflation” and the real rate you locked in at purchase. Entry point is critical. If you’re like me and started investing earlier, about 100bps lower in terms of real rates, you’ll wait till maturity like me. And then, will you have been made whole? Maybe. But consider why have real rates gone up so much lately? Harley Bassman, father of the MOVE index, posits that it is compensation for inherent deficiencies in the CPI index’s ability to represent the “real” rate of inflation. Fortunately, 30% of my TIPS bonds nature in the next 18 mos.
Thanks for pointing out the AI image’s right hand but the left is deformed as well. 🙂
Is VTIP the right TIPS investment in a regular account because of the fantom tax. All my tips are in my IRA
VTIP does work well in a regular account, since the inflation accruals are paid out in real time. The iShares target-date ETFs also work in a taxable account, same reason.
After 2022 I decided VTIP does not work well in a taxable account. VTIP took an approximate -3% nominal loss in 2022, and worse after inflation.
I created an AI generated report showing ETF BND, VTIP, and SCHP nominal and real performance, and also gold-adjusted performance (nominal performance minus the return of gold, GC=F), which I can’t share here.
VTIP has a -0.32% real (inflation adjusted) average annual total return for 10 years! Before taxes. That is not getting the job done, and is not protecting real purchasing power. BTW VTIP underperformed gold for 10 years by -8.8% (a reason to hold some gold as a diversifier in case of currency debasement).
Sure a TIPS bond has phantom interest tax liability (the lower the coupon, the higher the inflation, and the higher the tax rate, the worse the phantom interest tax drag). But another way to think about this is the inflation adjustment is similar to reinvesting dividends in an ETF, and when the bond matures you don’t owe any tax on the accrued inflation adjustments. So there’s some tax drag along the way, but it’s not so bad in the end.
A TIPS ETF I think has similar tax drag in the inflation accrual similar to the TIPS bond. You’re gonna pay the tax in that year, which is tax drag. Intuitively it seems fairly similar to me if you have other money available to pay the tax on the TIPS inflation accrual.
For all this talk and effort to parse out a few basis points here and there on bonds, how have TIPS and other nominal Treasuries performed vs. cash in the past five years? With bonds performing so badly lately, it is starting to feel like cash is becoming a more viable “investment,” or should at least have a more sizeable allocation in someone’s portfolio. Thoughts anyone?
Cash is looking very good right now, I agree. I was expecting money-market yields to fall with Fed rate cuts, but those never came and we got an increase instead. Last year I wrote on I Bonds vs. T-bills, here is the article: https://tipswatch.com/2024/04/21/lets-weigh-in-on-the-i-bonds-vs-t-bills-debate/ The chart in that article presents a sad history of Fed intervention in the T-bill market, while I Bonds continued chugging along, at least matching inflation. But again, right now cash is looking great. So are I Bonds at 4.26% currently.
Thank you for the link, I just read it, and I agree – it is hard to match iBonds. Too bad you can only buy $10,000 annually. I think Bessent’s intent is to finance on the short end, so how will that affect those rates? I watched a video on YouTube three years ago on how to ladder 4, 8, and 13 week T-Bills by Jennifer of Diamond Nest Egg, and copied her strategy in my Fidelity brokerage account. It worked flawlessly and I had monthly liquidity if needed, while continuing to capturing slightly higher yields than a money market (and with no state taxes). It took a couple of months of monitoring initially to set-up, but then the auto roll option made it effortless. I turned off auto roll when I needed the cash to deploy elsewhere, and I should consider doing it again in combination with iBonds for short-term cash (I’ve been lazily using SGOV of late). I do have a small $50,000 TIPS ladder in my IRA, and I’m curious about your thoughts on selling a recent 5-Yr TIPS purchase this year with a much lower coupon (1.25%) and re-purchasing it in the upcoming auction this month with almost twice the coupon now? Looks like the current par value of it is only about $20 less than my original cost basis. Am I “chasing yield” here? Which is exactly what my original question sort of hinted at. Enjoy your analysis as always, THANKS!
Right now I’ve a HYSA with a TEY higher than VUSXX and FDLXX.
Not by much, but it is higher. at a bank I’ve been at for 13 years, where I keep most of my cash-cash “emergency fund.” Then there’s I-Bonds.
I’m in a situation now where my excessive (it is!) E-fund may be tested by unemployment. We’ll see by end of the month. Though if I survive[1], I had already made plans to DCA out some excess first into additional “rungs” (beyond 6 mo.) in CDs/Treasuries to be working harder, with the remainder being DCA’d to taxable brokerage as it should.
—
I’m still far too young for TIPS, but in coming years I do eventually will build a ladder to provide $X/yr, which combined with SSA and I-Bonds, entirely covers a baseline (+extra) standard of living. Spikier expenses come out of Trad. 401K to get ahead of RMDs. Perhaps Roth conversions to fill 22%, but I’ll plan that out more in the next ~7 years.
Trad 401K, taxable and especially the Roth will still grow like crazy.
[1] Already having conversations. and looking at going independent again. Cuts to appease investors are coming, it’s a matter of time
Problem with “official inflation” as as benchmark, if your goal is to maintain overall purchasing power “inflation benchmark is a loser. M2 money supply is purchasing power index. Stock Market returns are more closely related M2. Unless your a big gambler or deep pockets, the avg person has to back out of the market and settle for less risk, less rewards, less purchasing power. The whole fix income is a losers when it comes to keeping up with purchasing power, but what your buying is insurance, insurance cost money. https://www.longtermtrends.com/m2-money-supply-vs-inflation/
I do have Ibonds with a big fixed rate and tax deferred, reinvested dividends, but that issue isn’t available anymore. Even if the fixed rate goes why up ibonds the limitations on purchase amount just are not worth significant.
I have to settle for simplicity, making MM rates with and keep a token amount in the market. Time to BBQ that $25 ribeye steak thats gone up much more than inflation.
Inflation has been sticky, but what if it’s not for much longer? Let’s say the Iran War ends (all wars end eventually) in 2027, oil prices drop back to their historical norms, inflation craters thereafter, and that gives the Fed the green light to lower interest rates a year from now. What is the impact on TIPS in that scenario, which is not out of the realm of possibility?
If inflation plummets back down to 1.8% (let’s say) for many years, TIPS you purchase today will underperform comparable nominal Treasurys. But with a real yield of 2.68% on a 5-year, you are still getting a nominal return of 4.48%, versus 5.02% for the current 5-year Treasury bond. It’s not a devastating difference.
I think the biggest loser part of tips is that we are effectively buying them because we don’t trust the government to manage inflation, and yet their payout is a direct function of what the government says Inflation is, requiring us to trust the government. I’m still a buyer, but it is an obvious problem.
I find myself wondering if a future (or current) administration will try to undermine or even eliminate TIPS due to our increasing deficit. It seems our government has relied on “growth” and inflation to help deal with this self-imposed problem. TIPs seem to run counter to this effort to use inflated dollars to pay off our debt. Call me paranoid, but nothing would surprise me at this point. Thoughts?
I agree with the statement, “Nothing would surprise me.”
If new TIPS issuance were suspended, would the yield on existing TIPS rise?
I don’t know. I wonder if the rarity created would cause yields to fall, with increasing demand.
Did we forget that WE, the People, are not powerless? If we ignore the cacophony on X and the posturing by our elected politicians, we can bring about the change we desire.
The fear of losing the power and privilege of spending our tax dollars will keep the politicians straight and narrow.
Too late for the keeping politicians “straight” but at least if you vote you might be able to shorten the time period for all the corruption!
Hi David and thanks for all you do! I’ve been spending a lot of time on our iBonds since your article about the administrative headaches expected by heirs when we die. I’ve learned (I think) that one strategy to eliminate individually owned iBonds from those delays is to designate the ownership as Jane Doe WITH John Doe. That way ownership transfers to John if Jane dies. We’ve also granted each other TRANSACT rights so after one spouse dies, the other can still access and manage/redeem the bonds. Then, the strategy is for the surviving spouse to change the ownership to WITH one of the heirs (with TRANSACT rights). This can be done with multiple heirs by designating WITH ownership on different, equivalent value bonds, or splitting the bonds into smaller denominations. This doesn’t protect heirs if both spouses die simultaneously, but generally, that’s a fairly low risk, in my view.
The bigger problem seems to arise for ibonds held in the name of our Revocable Trust. In our case, we listed my SSN for the Treasury Direct Trust account, but named my wife as manager. In fact, most of our bonds are in our Trust account, since we figured, like every other bank or brokerage account, our heirs (successor trustees) would simply be able to liquidate the bonds upon our deaths. But, my research so far suggests that once Treasury Direct learns of a death, if the account is in the SSN of the deceased, the account is frozen and the bureaucratic nightmare ensues. I’ve sent an email to Treasury Direct to check this, but meanwhile, I’m planning to sell a portion of our holdings, the ones older than 5 years with a 0% fixed rate, pay the tax, and re-invest in some regular TIPS with a higher fixed rate.
Thats a great point about the SSN! Was gonna do a trust but does look like it solves little for heirs for me. I think you hit on what really happens until the changes come though with a new EIN.
While you can no longer use your Social Security Number (SSN) for the trust’s financial activities, the trust itself remains active and functional. lol, I’m sure its locked until,
I buy discounted TIPS in the aftermarket inside my Roth IRA. Imputed interstate is never an issue.
The discount over compensates for inflation. At the extreme, 2051 & 2052 TIPS more than double the rate of inflation.
I may not hold till maturity, but I will hold through several Presidents and long enough to move down the yield curve, creating capital gains.
Interest not “interstate”.
I am not as risk adverse as many, or most, TIPS buyers. I hope to die with my Roth untouched, which gives my heirs another decade. But disabling health conditions might force me to liquidate part of my Roth IRA in the future. Which part will depend on conditions then.
There are so many financial terms that I don’t understand, I thought that was a new one.
I think you made the point those having to sell before maturity may be a loser.
Or a winner. Given that real interest rates on TIPS are at 20 year highs, the odds of winning – or at least breaking even, look very good.
Plus with decade plus holding periods, the bonds will move down the yield curve.
Since the coupon is 1/8%, much of the YTM is reinvested (effectively) at the current high real interest rates. Plus the discounted TIPS are over indexed for inflation.
As I have other assets in my Roth, *IF* I have to sell before my death, I can pick & choose which assets to sell – or at least the order in which to sell them.
To me, the risks of discounted TIPS vs par TIPS are far smaller than the potential rewards (if I hold for a dozen plus years).
To go with the person that replied to your comment about the low coupon, purchasing super low-coupon TIPS on the secondary market, at least to my layman’s mind, is like purchasing treasury-protected zero-coupon bonds. Except they’re not really zero-coupon. They’re 1/8 of 1% coupon or 1/4 of 1% coupon. In this case the reinvestment risk is close to zero, and the tradeoff, of course, is deflation eating away some of that extra principal you paid for. how far off is my logic here?
David, first-time poster here, long-time lurker and loser. Typo: Unhedged, not Unhinged, in the second paragraph hyperlink.
Earlier in the week, prior to Hakyung’s TIPS article in the newsletter, her boss and Unhedged founder, Robert Armstrong, said he was long TIPS in the Unhedged podcast Long/Short game. He also said it was not investment advice.
Darn, I think “Unhinged” would be a much better title. Thanks for the alert, and this is fixed.
A plus one for those Target maturity etfs. I’ve never even considered them before, but with popularity for tips rising, I tried to buy a couple of rungs for my ladder at vanguard and couldn’t get any of the years I wanted for under a hundred thousand. 2029 to 2033. I’ve always been able to grab $10,000 chunks without a hitch. So these Target maturity ETF strike me as a very valuable product.
Kenneth, here’s my tip on the secondary market: Try making a purchase during open market times, Monday to Friday. (Maybe you are already doing that?) At Vanguard, when the market is closed, you can find very few TIPS with reasonable purchase limits. I have succeeded during weekday market times to make $8,000 or $10,000 purchases, even when the list seemed to indicate that wasn’t possible.
The truth is, I actually don’t know if my $100,000 wall was the result of trying to order outside of hours or not. Thank you for bringing this to my attention. In the past I found with vanguard that I couldn’t even get to the bond screen during off hours, or at least that’s what my 61-year-old memory tells me. I’ll give it another try!