10-year TIPS reissue auctions at -0.602%

Treasury logoThe Treasury just announced that its reissue of CUSIP 912828UH1 – creating a 9-year, 10-month TIPS – auctioned with a yield to maturity of -0.602%.

That means buyers of this Treasury Inflation-Protected Security are accepting 0.602% less than the rate of inflation over the next 10 years. This TIPS has a coupon rate of 0.125%, the lowest possible. Buyers will therefore ‘pay up’ to earn the auctioned yield, about $107.06 per $100 of value.

Today’s rate, though, is slightly higher than the -0.630% yield generated at auction when this TIPS was born in January.

Read the Treasury’s auction results summary.

Today’s auction continued a trend of TIPS offerings with yields rising above record lows. The record low yield for any 9- or 10-year TIPS offered at auction is -0.750%, set last September. But as recently as 10 days ago, a -0.5% yield looked possible for today’s auction. That trend turned when economic turmoil in Cyrpus gave Treasury markets a boost.

The breakeven rate. The 10-year Treasury is currently trading at 1.94%, down from 2.06% as recently as March 7. That sets the 10-year breakeven rate for today’s TIPS at 2.54% – meaning that buyers are betting that inflation will average 2.54% over the next 10 years.

Any number over 2.5% is historically high for the breakeven rate. Inflation has been running at 2.0% over the last 12 months.

Reaction to the auction. The Wall Street Journal’s Cynthia Lin called demand for this auction ‘decent,’ despite the negative yield.

Despite the negative yield and little sign of inflation in the U.S. economy, some investors are still willing to pay up for inflation protection because of the Federal Reserve’s ongoing easy monetary policy. The central bank aims to induce inflation by buying bonds, currently set at $85 billion a month. The Fed on Wednesday affirmed this policy. …

 

Posted in Investing in TIPS | Leave a comment

Another 10-year TIPS auction, and another world crisis …

I am getting tired of this pattern. I will attempt to offer no proof, but I am getting a strong feeling that just before every significant TIPS auction, we get a world crisis that drives up the prices of Treasurys, especially TIPS.

Thursday, we will get a reopening of a 10-year TIPS, and yields to maturity had been trending up toward the lofty level of -0.5%, meaning a half percentage point less than inflation over 10 years. That’s a lousy investment, but better than several recent 10-year TIPS auctions.

At the same time, Europe unloads the most idiotic scheme ever — taxing bank accounts in Cyprus to bail out banks for their foolish investments. Simply put, taxing the wise to bail out the fools. From New York Times coverage:

In a rare move, Cyprus is trying to raise around 5.8 billion euros ($7.5 billion) from a one-time bank charge on local deposits. … “If the problem escalates, the entire euro zone banking system could implode,” said Cormac Leech, a banking analyst at Liberum Capital, in London.

Fearing similar moves to those in Cyprus, local depositors in countries like Spain and Italy may look to shift their money to banks in stronger European economies. … “This is certainly new territory,” said Pete Hahn, a banking professor at Cass Business School in London. “What is confronting Cyprus is a unique situation, but the idea could be applied in other places in Europe.”

For even more fun, read Michael Ashton’s E-phinay post today, ‘Stealing Really Is That Bad.’:

Here is the problem: you didn’t ask them if they would “accept” at least a “minor” bailing out. You ordered people who didn’t need a bailout – savers with earned balances in the banks – to pay for the bailout. I daresay that it doesn’t seem “minor” to those who had their money stolen to save someone else. …

Now, in the micro picture none of those reflections are very market-oriented, but in the macro picture they certainly are. We all have to deal on a day-to-day basis with the reality that markets are nakedly manipulated by central banks these days.

In the face of this amazing stupidity, investors (the wise ones, not the fools) are naturally heading to safety, and that means U.S. Treasurys. The 10-year Treasury closed today at 1.96%, 5 basis points up from Friday. The TIP ETF was up 0.2% today.

OK, that’s not Earth-shattering, but it broke the trend toward a favorable rate in Thursday’s 10-year TIPS auction. Today, CUSIP 912828UH1, the one being reopened Thursday, closed on the secondary market with a yield to maturity of -0.617, down from Friday’s close of -0.582%.

Again, not disastrous, but the trend is now moving against buyers of this week’s auction.

All in all, TIPS-week Monday could have been a lot worse.

Posted in Investing in TIPS | Leave a comment

Inflation shot up sharply in Feburary

‘Headline’ inflation – properly called Consumer Price Index for All Urban Consumers (CPI-U) – rose a very sharp 0.7% in February, the Bureau of Labor Statistics reported this morning. It was the biggest monthly rise since June 2009.

This was somewhat expected, because gas prices have risen sharply in the last two months. Gasoline prices – up 9.1% in February – accounted for about 3/4 of the overall increase in prices, the BLS said. The food index was up a tame 0.1%.

Read the CPI summary from the BLS.

Headline inflation is important, because it is the number (minus seasonal adjustment) used to adjust the principal on TIPS holdings and to set the future inflation-adjustment interest rates on I Bonds.

Without the seasonal adjustment, CPI-U rose 0.8% in February. Today’s number sets inflation over the last 12 months at 2.0%, up from 1.6% in January.

Here’s a summary of month-by-month changes in headline inflation:

one-year inflation

The Federal Reserve watches ‘core’ inflation more closely, stripping out the volatile food and energy indexes. Core inflation was mild in February — 0.2% versus 0.3% in January. For the last twelve months, it is running at 2.0%, still giving the Fed room to continue monetary stimulus.

The takeaway for TIPS  holders is … you got a 0.8% boost to your holdings, long overdue after four months of zero inflation. What’s ahead? Gasoline prices have been moderating, and today’s coverage by the Associated Press downplayed inflation fears:

“Aside from the spike in gasoline prices, which is already being reversed, it is hard to find any evidence of major price pressures,” said Paul Dales, senior U.S. economist for Capital Economics.


Posted in Investing in TIPS | Leave a comment

Does the world really need more TIPS mutual funds?

Apparently so. State Street Global Advisors, the world’s second largest asset manager, says in a regulatory filing that it is launching two new ETFs based on Treasury Inflation-Protected Securities:

  • SPDR Barclays 0-5 Year TIPS ETF, which will track the Barclays 0-5 Year Government Inflation-linked Bond Index.
  • SPDR Barclays 1-10 Year TIPS ETF, which will track the Barclays 1-10 Year Government Inflation-linked Bond Index.

The filing does not reveal the ticker symbols or the expected management fees associated with each ETF. Let’s see if State Street can approach the 0.10% expense ratio of the Vanguard Short-Term Inflation-Protected Securities ETF (VTIP), which was launched in October 2012.

State Street currently provides an overall TIPS market ETF, the SPDR Barclays TIPS (IPE), with $740 million in assets and an annual expense ratio of 0.19%. But the giant here is the iShares Barclays TIPS Bond (TIP), with more than $21 billion in assets and an annual expense ratio of 0.20%.

Too many TIPS funds? Maybe not, but the surge in TIPS ETFs mirrors investors’ high interest in inflation protection, as the Fed pours cheap money into the economy, and the U.S. government fails to get deficits under control. ETFs often seem to be a lagging indicator — they rise up well after a sector goes hot.

Here’s a list from Yahoo Finance of currently available funds seeking inflation protection:

  • FlexShares iBoxx 3-Year Target Duration TIPS Index Fund (TDTT)
  • FlexShares iBoxx 5-Year Target Duration TIPS Index Fund Profile (TDTF)
  • Global Advantage Inflation-Linked Bond Exchange-Traded Fund (ILB)
  • iShares Global Inflation-Linked Bond Fund (GTIP)
  • iShares International Inflation-Linked Bond Fund (ITIP)
  • iShares Barclays Treasury Inflation Protected Securities Fund (TIP)
  • iShares Barclays 0-5 Year TIPS Bond Fund (STIP)
  • PIMCO Broad U.S. TIPS Index Exchange-Traded Fund (TIPZ)
  • PIMCO 1-5 Year US TIPS Index Exchange-Traded Fund (STPZ)
  • PIMCO 15 Year US TIPS Index Exchange-Traded Fund (LTPZ)
  • Schwab U.S. TIPS ETF (SCHP)
  • Vanguard Short-Term Infl-Prot Sec Idx ETF (VTIP)

I can understand the desire to go with shorter-term TIPS, because when rates begin rising the longer-term Treasurys are going to be slammed. A rise of just a half percentage point will drop the value of a 30-year TIPS by nearly 15%.

Short-term TIPS, though, lock in a return that will lag inflation by at least 1.6%. So it will take mighty high inflation to get any sort of return. On the other hand, your money market fund will lag inflation by the rate of inflation.

I don’t have a great answer for storing short-term cash. My personal preference is the Vanguard Short-Term Corporate Bond ETF (VCSH), with $5.4 billion in assets and an expense ratio of 0.12%. I can buy and sell this at Vanguard without any trading fees.

It currently yields 1.22%, versus a big question mark for a fund like Vanguard’s short-term VTIP. Vanguard, being super responsible as usual, lists VTIP’s current yield as  -2.13%, but that is before inflation, which is running about 1.7%. This means VTIP has a negative current yield. (On the other hand, VTIP’s net asset value has risen by about 1% more than VCSH’s since the launch in October, and that helps even out total return.)

This again points out the need to shop for the lowest possible expense ratios and trading fees when you invest in short-term bond ETFs.

Posted in Investing in TIPS | 2 Comments

Next up: 10-year TIPS reissue to be auctioned March 21, 2013

The U.S. Treasury will announce Thursday – just a formality – that on March 21 it will auction a reopening of CUSIP 912828UH1, a 10-year Treasury Inflation-Protected Security that was first auctioned on Jan. 24. This creates a 9-year, 10-month TIPS.

This TIPS has a coupon rate of 0.125%, but will end up auctioning with a yield to maturity well below that, probably around -0.526%, where it was trading on the secondary market on Monday. This also means that buyers at the March 21 auction will have to ‘pay up’ to get that 0.125% coupon rate, probably around $106.10 for every $100 of value.

TIPS yields are gently rising, but earning 0.5% less than inflation for 10 years won’t be attractive to a lot of small investors. Buyers who hold to maturity won’t be looking for income, they will be seeking: 1) Capital preservation with a super-safe, conservative investment, and 2) protection against a burst of inflation in the next 10 years. These buyers can ignore the secondary market and just hang on to maturity.

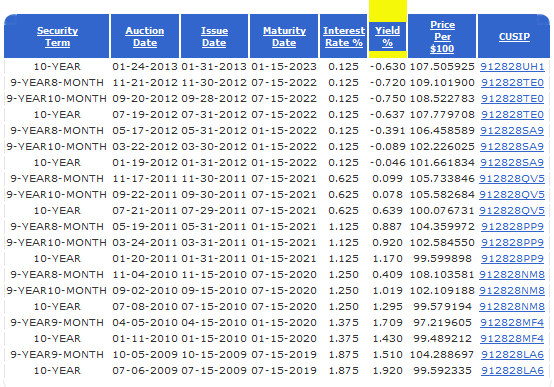
TIPS traders, though, will want to be cautious. Not long ago, every single TIPS ever issued was trading above its original value, as yields to maturity dropped to record low after record low. That trend has now broken, as shown in this chart of recent 10-year TIPS auctions:

10-year TIPS auctions

If the March 21 auction goes off with a yield of -0.52%, it will mark the third consecutive 10-year TIPS auction with a higher (although still negative) yield. Buyers of CUSIP 912828UH1 back in January have already seen its market value decline by about 1%.

The question is always: Where are interest rates headed, and when? Wish I knew the answer.

Breakeven rate. The 10-year Treasury closed Monday at 2.07%, its highest rate for the year. If the TIPS reissue goes off at -0.52%, it sets the 10-year breakeven rate at 2.59%, meaning that buyers are betting that inflation will average higher than 2.59% over the next 10 years. A breakeven rate above 2.5% is considered very high. Keep in mind that inflation in 2012 was only 1.7%.

Posted in Investing in TIPS | Leave a comment