
By David Enna, Tipswatch.com
The Treasury’s auction of a new 5-year Treasury Inflation-Protected Security, CUSIP 91282CRR4, generated a real yield to maturity of 2.367%, a disappointing result on a “risk-off” day that sent investors flooding into the safety of U.S. Treasurys.
Each October, the 5-year new issue is difficult to predict, but after yesterday’s close I would have guessed today’s real yield would have come in about 2.47%. A series of events overnight — a tech-stock rout, an escalation of tensions in the Mideast, and a debt-frenzy hitting Europe — resulted in investors swapping out of stocks and into Treasurys.
Both nominal and real yields have declined today. The yield of the 10-year Treasury note, for example, has fallen from about 5.13% yesterday to 4.96% today. That is significant, and today’s TIPS auction was caught in the wave.
Demand did not look surprisingly strong. The auction’s bid-to-cover ratio was 2.41, the lowest since a similar auction in April 2025. The “when-issued” yield prediction used by bond traders was 2.36%, and the auction result came in a bit higher.
The coupon rate for this TIPS was set at 2.25%.
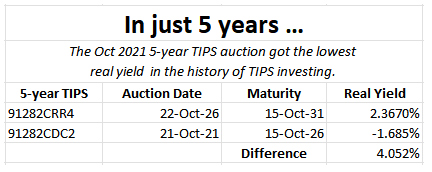
It’s important to note, however, that the real yield of 2.367% was the highest at auction for this term in the last three years. And it was massively higher than the October auction of 2021. Investors should feel good about that.
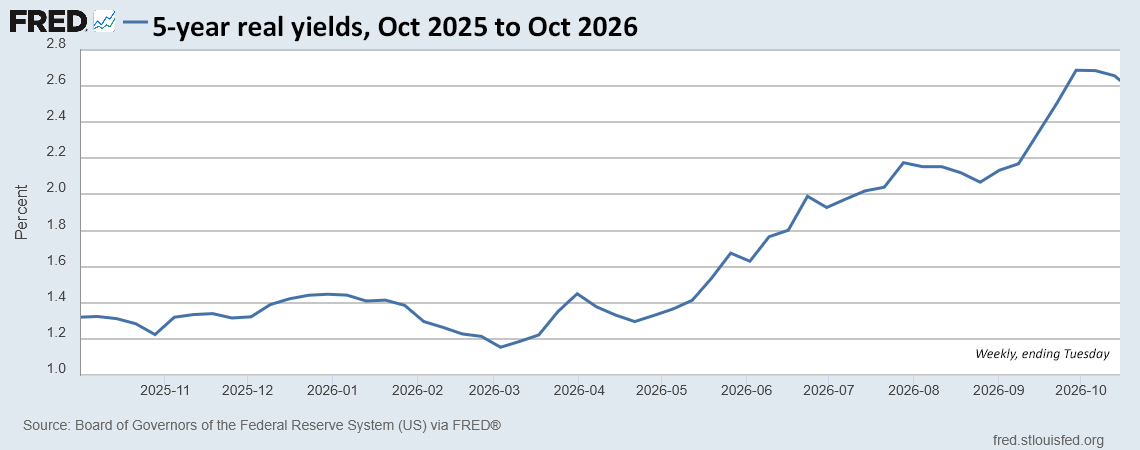
Here is the trend in the 5-year real yield over the last year (ending Tuesday), showing the remarkable surge higher since May:
Pricing
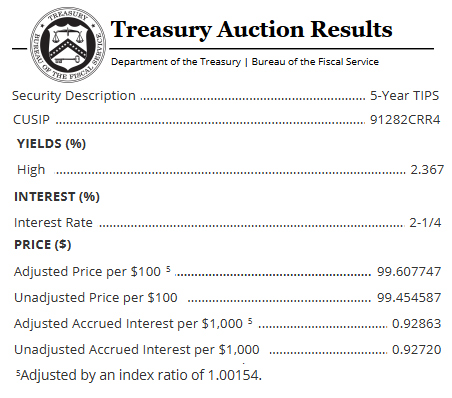
CUSIP 91282CRR4 got an unadjusted price of 99.454587, at a discount because the coupon rate was set below the auction’s high yield. It will also carry an inflation index of 1.00154 on the settlement date of October 30. With that information we can calculate the cost of a $10,000 par value purchase at this auction.
- Par value: $10,000.
- Principal purchased on settlement date: $10,000 x 1.00154 = $10,015.40.
- Cost of investment: $10,015.40 x 0.99454587 = $9,960.77.
- + accrued interest of $9.29.
In summary, an investor paid $9,960.77 for $10,015.40 of principal on the settlement date. From then on, the investor will earn accruals matching official U.S. inflation, plus annual coupon interest ot 2.25%, for the next five years. The accrued interest will be returned at the first coupon payment in April.
Inflation breakeven rate
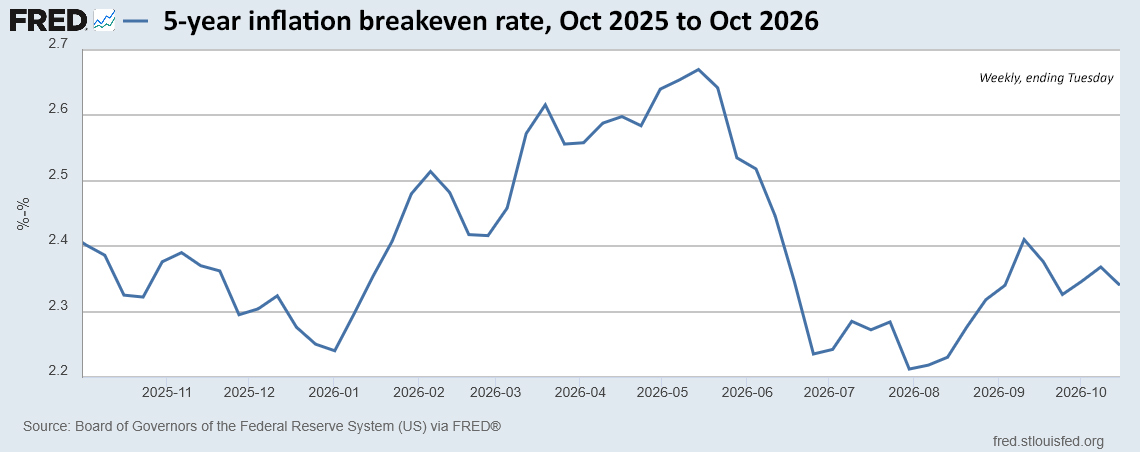
At the auction’s close, the 5-year Treasury note was yielding 4.78%, giving this TIPS a 5-year inflation breakeven rate of 2.41%, a bit higher than recent trends for this term. The breakeven rate means the TIPS will out-perform a nominal Treasury if inflation averages more than 2.41% over the next five years. To me, this breakeven rate looks about right, but I’d prefer the inflation protection provided by the TIPS.
Here is the trend in the 5-year inflation breakeven rate over the last year, showing the decline in inflation expectations since mid-year:
Auction thoughts
Heading into this week, this auction looked very likely to set a 20-year high in real yield — possibly around 2.50% — but market turmoil broke that trend. The Treasury’s daily Yield Curve Estimate still showed 2.55% for a 5-year TIPS at yesterday’s close. (I thought the Treasury estimate was probably too high, as I explained in my preview article for this auction.)
So we end up with a real yield of 2.367%, a good result but not awe-inspiring. This TIPS will begin trading soon on the secondary market, and it will get a reopening auction on Tuesday, December 22. If we end up getting a rate increase from the Federal Reserve on December 9, that auction could get interesting.
Coming up. I will be posting a “forecast” for the I Bond’s new fixed and composite rates on Sunday, 8 a.m. ET. There is a lot of uncertainty for the fixed rate at the November 1 reset and this could go down to the wire.
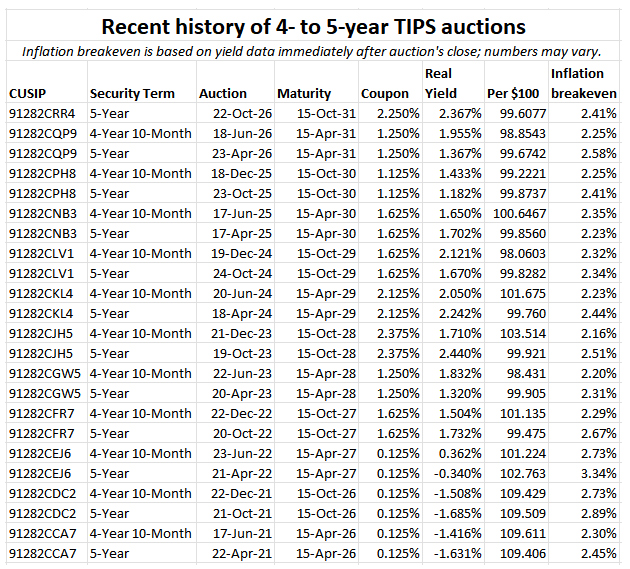
Here are results for every 4- and 5-year TIPS auction over the last five years:
• Now is an ideal time to build a TIPS ladder
• Confused by TIPS? Read my Q&A on TIPS
• TIPS in depth: Understand the language
• TIPS on the secondary market: Things to consider
• TIPS investor: Don’t over-think the threat of deflation
• Upcoming schedule of TIPS auctions
—————————
Donate? This site is free and I hope to keep it that way. Some readers have suggested having a way to contribute. I welcome donations, any amount. And FYI, ads on this site pay for about one visit to Costco.
—————————
Follow Tipswatch on X for updates on daily Treasury auctions and real yield trends (when I am not traveling).
Feel free to post comments or questions below. If it is your first-ever comment, it will have to wait for moderation. After that, your comments will automatically appear. Please stay on topic and avoid political tirades. NOTE: Comment threads can only be three responses deep. If you see that you cannot respond, create a new comment and reference the topic.
David Enna is a financial journalist, not a financial adviser. He is not selling or profiting from any investment discussed. I Bonds and TIPS are not “get rich” investments; they are best used for capital preservation and inflation protection. They can be purchased through the Treasury or other providers without fees, commissions or carrying charges. Please do your own research before investing.


Trying to decide between buying this 5-year TIPS on the secondary market versus a 5-year targeted maturity TIPS ETF in a taxable account (with a relatively low tax bracket). Thoughts? Thank you.
So there are apparently some ‘pressures’ that tend to bring down yields at auction, as compared to the secondhand market. Is this repeatable? Surely not or nobody would buy at auction. There must be times when the auction outperforms the secondhand market? Ignoring the other aspects (know what you are getting), I would expect, on average, the auction should outperform the secondhand market, or nobody would ever go to auctions. Is there some historical record of the spike or dip at auction compared to the baseline rates of the time period?
I believe the June 5-year TIPS reopening was the opposite situation, better than expected: https://tipswatch.com/2026/06/18/5-year-tips-auction-gets-a-real-yield-of-1-955-a-good-result-for-investors/
When you participate in the auction, you are a noncompetitive bidder and automatically “win” the auction in that you get the same yield as big institutional bidders.
Because all secondary market supply ultimately comes from the primary market, if you could consistency outperform primary by buying secondary, wouldn’t that mean the big institutional competitive bidders are consistently losing money, and so it would self-correct as they bid higher yields?
The June TIPS auction is much easier to predict because the market rate is based on the April-issue TIPS and the June auction is reopening that same TIPS. The TIPS market is really not designed for small-scale investors. These are big-money investors — central banks, hedge funds, insurance companies — and the auction gives them the opportunity for a large purchase. That’s a lot more limited on the secondary market for the big-money people.
Regarding the Dec22 reopening, you state “If we end up getting a rate increase from the Federal Reserve on Dec 9, that auction could get interesting.” As a TIPS newby, interesting in what way?
The 5-year TIPS is most sensitive of the auctioned maturities to changes in the federal funds rate. Its real yield tends to track higher when the Fed raises short-term rates. The same is probably true for the 5-year Treasury note. Longer-term issues have less of a direct tie-in.
Buying the 5 year TIPS at today’s auction is hardly a mistake. For me, this is the highest real yielding 5 year TIPS I have. My lowest is 1.6% real. So getting approximately 2.3% is a win for me. Furthermore earlier this year I bought a 3 year CD at 3.8%. That was an unfortunate purchase. Win some. Lose some.
Josh, this is the correct view. I just looked over all the TIPS in my ladder out to 2043 and my lowest real yield at purchase was -0.589 (a nibble) and my highest is 3.899%, purchased back in 1999. Most of my TIPS have a real yield in the range of 1.75% to 2.55%. I am fine with all those purchases.
I’m a bit disappointed in the drop myself, but it doesn’t seem that long ago that I was wondering if we’d see 2% again, so I’m happy enough.
I was a buyer and am happy with the real yield… close enough to my expectations.
I’m in the middle of building a ladder for 2028-2048. Having filled the rungs for 2040-2048 yesterday, I was hoping to fill the rungs for 2028-2036 today. I participated in today’s auction, but I lost heart after seeing yields fall by 14-15 bps by midday. Any reason why I shouldn’t proceed as planned over the next few days? Yields for 2028-2036 are still quite good from a historical perspective, aren’t they?
Great work yesterday; those yields were probably fantastic. Now, are we moving into lower yields? Only if the economy tanks, I’d guess.
Two questions:
Question 1: Normally, there would be zero effect this late in the six-month cycle, but the call between 1.3% and 1.4% remains extremely close. So it could have an effect. Only a few days left. I will post that preview Sunday morning, but it will be somewhat a guess.
Question 2: I’d say the 5-year TIPS continues to have a small yield advantage (given other factors in the I Bond’s favor) with the fixed rate at either 1.3% or 1.4%. I’m using a fair-value ratio of 0.65.
Minor typo error: In the first line of the Auction Thoughts second paragraph, you wrote 3.763%, it should be 3.673%
Thanks. It’s fixed
It’s probably simplistic but I think you get a lower rate for being locked in for fewer years.
This is generally true, but not always! There were times during the dark days of financial repressions (post 2011) that the real yield curve basically flattened. In September 2023, when the Fed was raising short-term rates, there were a few days when the 5-year real yield exceeded the 10-year. The 5-year is more sensitive to increases in short-term rates.
I understand the disappointment that the auction yield came in below what some were expecting. I was a buyer, and I too was hoping for more…. But I think there’s a bright side here too.
You can easily find it in the historical perspective: this was the highest 5-year TIPS auction real yield since October 2023, AND, beyond that you have to go back to 2008 to find a higher yield. That’s a pretty remarkable result when you look at the bigger picture.
I think that’s a very good outcome. Could the yield have been better? Sure. But, is it really all that bad? Putting expectations aside, are you really unhappy with 2.367 percent above inflation for 5-years?
I’m pleased to secure a real return at this level, and I suspect I’ll be glad I did when I look back five years from now. Best, to all.
Thank you for this, I appreciate it! My initial reaction was disappointment – I’d stuck to my plan to buy at this auction and hoped for better results….but as they say, “When in doubt, zoom out!”
Absolute agree that 2.367% is good, both in absolute and in recent historical terms. I, like David, was looking at those predictions–hard to believe it was just yesterday–of 2.5% or more, so that the actual auction result proved to be just a bit of a (literal) downer.
My first time buying 5 yr TIPS at auction. I already bought some STRIPS a few weeks ago at 5%.
I bought a bunch of STRIPS as well
Wouldn’t surprise me too much if it turned out the Treasury itself had something to do with helping the rate lower.
The results are still a nice Real yield for 5 years.
I did participate and was really disappointed by this ‘surprise’ turn of events overnight. This is the second time I’ve received disappointing results from an auction compared to the day before’s expectation. I doubt I will be doing this again, and instead will buy on the secondary market where I will know for certain what I’m paying and what real yield I’m getting. I expected a 2.50% coupon to be set today, and instead I got a 2.25% coupon. I expected right around 2.50% yield and got 2.367%. I note that within the past month, similar maturities traded as high as 2.70% yield and I was watching them on that date
Len, I’m in the same boat as you. Bought today, although less than I’d originally intended.
In my case, the TIPS are in a Roth IRA, which means submitting the purchase order before the brokerage’s breakfast-time deadline to meet Treasury requirements, even though the auction itself won’t officially conclude until hours later.
And that’s one of the problems with auctions: waiting to see what happens, participants but also bystanders, we can get caught up, for better or for worse, in assorted lemming behaviors of the big institutions that really influence the bond market.
Right now I’m inclined to share your thinking: Must . . . remember . . . to . . . stick to . . . secondary market . . . where . . . I know . . . exactly what I’ll be getting. 🙂
I also did some today although less than I originally planned. Glad so! I did it in a tax deferred account and placed the trade yesterday. I did sense it would not be awe inspiring today.
I have accounts at Vanguard, Schwab, Wells Fargo, and E-Trade, which came from the allure of new account joining bonuses over time to move accounts. All but WF do not charge markup/down or commissions on secondary treasury trades and the bid/ask spreads seem to be quoted the same on actively traded treasuries, very reasonable, although wider on TIPS. Today’s buy was at WF and the reason I did the auction was they DO charge markup/down on treasuries, they do not give bond desk prices, so in recent weeks when I saw something I liked at Schwab, normally got the identical bid quote at E-Trade, when I went to WF where the money was the quote was higher due to a markup, about 0.5% in principal as I recall which is significant, and I balked. I have no other issues with WF but for this reason I will likely soon be seeking another new account bonus and moving that IRA somewhere else, perhaps E-Trade which is offering a bonus on new to E-Trade money added to an existing account.
PS to clarify, WF does not charge any markup/down on treasuries bought at auction, only on secondary market trades. Their inventory also is poor, not all existing bonds show up when searched. Of course all new treasuries at auction are available.
Thanks for the clear reporting, David! I debated but didn’t jump in on this one. Planning a shift from I bonds and may shift some funds from nominal Treasuries as well.