Inflation shot up sharply in Feburary

‘Headline’ inflation – properly called Consumer Price Index for All Urban Consumers (CPI-U) – rose a very sharp 0.7% in February, the Bureau of Labor Statistics reported this morning. It was the biggest monthly rise since June 2009.

This was somewhat expected, because gas prices have risen sharply in the last two months. Gasoline prices – up 9.1% in February – accounted for about 3/4 of the overall increase in prices, the BLS said. The food index was up a tame 0.1%.

Read the CPI summary from the BLS.

Headline inflation is important, because it is the number (minus seasonal adjustment) used to adjust the principal on TIPS holdings and to set the future inflation-adjustment interest rates on I Bonds.

Without the seasonal adjustment, CPI-U rose 0.8% in February. Today’s number sets inflation over the last 12 months at 2.0%, up from 1.6% in January.

Here’s a summary of month-by-month changes in headline inflation:

one-year inflation

The Federal Reserve watches ‘core’ inflation more closely, stripping out the volatile food and energy indexes. Core inflation was mild in February — 0.2% versus 0.3% in January. For the last twelve months, it is running at 2.0%, still giving the Fed room to continue monetary stimulus.

The takeaway for TIPS  holders is … you got a 0.8% boost to your holdings, long overdue after four months of zero inflation. What’s ahead? Gasoline prices have been moderating, and today’s coverage by the Associated Press downplayed inflation fears:

“Aside from the spike in gasoline prices, which is already being reversed, it is hard to find any evidence of major price pressures,” said Paul Dales, senior U.S. economist for Capital Economics.


Posted in Investing in TIPS | Leave a comment

Does the world really need more TIPS mutual funds?

Apparently so. State Street Global Advisors, the world’s second largest asset manager, says in a regulatory filing that it is launching two new ETFs based on Treasury Inflation-Protected Securities:

  • SPDR Barclays 0-5 Year TIPS ETF, which will track the Barclays 0-5 Year Government Inflation-linked Bond Index.
  • SPDR Barclays 1-10 Year TIPS ETF, which will track the Barclays 1-10 Year Government Inflation-linked Bond Index.

The filing does not reveal the ticker symbols or the expected management fees associated with each ETF. Let’s see if State Street can approach the 0.10% expense ratio of the Vanguard Short-Term Inflation-Protected Securities ETF (VTIP), which was launched in October 2012.

State Street currently provides an overall TIPS market ETF, the SPDR Barclays TIPS (IPE), with $740 million in assets and an annual expense ratio of 0.19%. But the giant here is the iShares Barclays TIPS Bond (TIP), with more than $21 billion in assets and an annual expense ratio of 0.20%.

Too many TIPS funds? Maybe not, but the surge in TIPS ETFs mirrors investors’ high interest in inflation protection, as the Fed pours cheap money into the economy, and the U.S. government fails to get deficits under control. ETFs often seem to be a lagging indicator — they rise up well after a sector goes hot.

Here’s a list from Yahoo Finance of currently available funds seeking inflation protection:

  • FlexShares iBoxx 3-Year Target Duration TIPS Index Fund (TDTT)
  • FlexShares iBoxx 5-Year Target Duration TIPS Index Fund Profile (TDTF)
  • Global Advantage Inflation-Linked Bond Exchange-Traded Fund (ILB)
  • iShares Global Inflation-Linked Bond Fund (GTIP)
  • iShares International Inflation-Linked Bond Fund (ITIP)
  • iShares Barclays Treasury Inflation Protected Securities Fund (TIP)
  • iShares Barclays 0-5 Year TIPS Bond Fund (STIP)
  • PIMCO Broad U.S. TIPS Index Exchange-Traded Fund (TIPZ)
  • PIMCO 1-5 Year US TIPS Index Exchange-Traded Fund (STPZ)
  • PIMCO 15 Year US TIPS Index Exchange-Traded Fund (LTPZ)
  • Schwab U.S. TIPS ETF (SCHP)
  • Vanguard Short-Term Infl-Prot Sec Idx ETF (VTIP)

I can understand the desire to go with shorter-term TIPS, because when rates begin rising the longer-term Treasurys are going to be slammed. A rise of just a half percentage point will drop the value of a 30-year TIPS by nearly 15%.

Short-term TIPS, though, lock in a return that will lag inflation by at least 1.6%. So it will take mighty high inflation to get any sort of return. On the other hand, your money market fund will lag inflation by the rate of inflation.

I don’t have a great answer for storing short-term cash. My personal preference is the Vanguard Short-Term Corporate Bond ETF (VCSH), with $5.4 billion in assets and an expense ratio of 0.12%. I can buy and sell this at Vanguard without any trading fees.

It currently yields 1.22%, versus a big question mark for a fund like Vanguard’s short-term VTIP. Vanguard, being super responsible as usual, lists VTIP’s current yield as  -2.13%, but that is before inflation, which is running about 1.7%. This means VTIP has a negative current yield. (On the other hand, VTIP’s net asset value has risen by about 1% more than VCSH’s since the launch in October, and that helps even out total return.)

This again points out the need to shop for the lowest possible expense ratios and trading fees when you invest in short-term bond ETFs.

Posted in Investing in TIPS | 2 Comments

Next up: 10-year TIPS reissue to be auctioned March 21, 2013

The U.S. Treasury will announce Thursday – just a formality – that on March 21 it will auction a reopening of CUSIP 912828UH1, a 10-year Treasury Inflation-Protected Security that was first auctioned on Jan. 24. This creates a 9-year, 10-month TIPS.

This TIPS has a coupon rate of 0.125%, but will end up auctioning with a yield to maturity well below that, probably around -0.526%, where it was trading on the secondary market on Monday. This also means that buyers at the March 21 auction will have to ‘pay up’ to get that 0.125% coupon rate, probably around $106.10 for every $100 of value.

TIPS yields are gently rising, but earning 0.5% less than inflation for 10 years won’t be attractive to a lot of small investors. Buyers who hold to maturity won’t be looking for income, they will be seeking: 1) Capital preservation with a super-safe, conservative investment, and 2) protection against a burst of inflation in the next 10 years. These buyers can ignore the secondary market and just hang on to maturity.

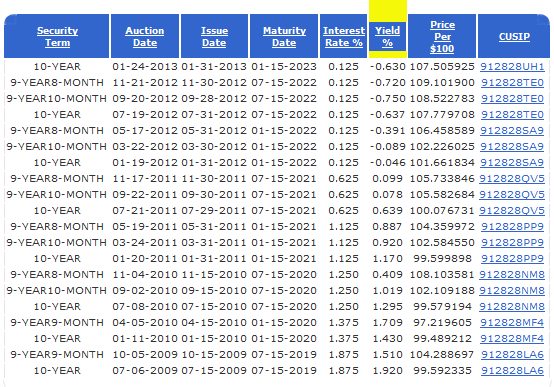
TIPS traders, though, will want to be cautious. Not long ago, every single TIPS ever issued was trading above its original value, as yields to maturity dropped to record low after record low. That trend has now broken, as shown in this chart of recent 10-year TIPS auctions:

10-year TIPS auctions

If the March 21 auction goes off with a yield of -0.52%, it will mark the third consecutive 10-year TIPS auction with a higher (although still negative) yield. Buyers of CUSIP 912828UH1 back in January have already seen its market value decline by about 1%.

The question is always: Where are interest rates headed, and when? Wish I knew the answer.

Breakeven rate. The 10-year Treasury closed Monday at 2.07%, its highest rate for the year. If the TIPS reissue goes off at -0.52%, it sets the 10-year breakeven rate at 2.59%, meaning that buyers are betting that inflation will average higher than 2.59% over the next 10 years. A breakeven rate above 2.5% is considered very high. Keep in mind that inflation in 2012 was only 1.7%.

Posted in Investing in TIPS | Leave a comment

Update on U.S. inflation: Still mild

I was away from my computer last week, and updating a blog with an iPad is pretty much hell on Earth. So, I’m catching up.

On Thursday, the same day as the 30-year TIPS auction, the U.S. announced that ‘headline’ inflation (CPI-U, the one that matters to holders of TIPS and I Bonds) was zero in January. Over the last 12 months ending in January, headline inflation has been running just 1.6%, giving recent buyers of TIPS a double whammy — yields negative to inflation combined with very low inflation.

As this chart shows, holders of TIPS have received zero in inflation adjustment to principal since October:

One-year inflation

Excluding the volatile food and energy categories, core inflation rose 0.3 percent in January. Core prices have risen 1.9 percent in the past year, below the Fed’s inflation target of ‘less than’ 2.5%. This could indicate that the Fed will feel free to continue its aggressive buying of Treasurys. From the Associated Press report:

“As long as inflation readings remain relatively constrained and inflation expectations do not get out of control, the (Fed) has plenty of runway to continue its program,” Dan Greenhaus, chief global strategist at brokerage BTIG, said in a note to clients.

February CPI, however, is likely to tick upward because of sharply rising gas prices.

Posted in Investing in TIPS | 2 Comments

30-year TIPS auctions well above record low

The U.S. Treasury announced today that it auctioned a new 30-year Treasury Inflation-Protected Security, with a coupon rate of 0.625%, and a yield to maturity of 0.639%.  This is CUSIP 912810RA8.

Buyers are getting a yield well above the record low for a 30-year TIPS, 0.479% for a reissue in October 2012. Today’s auction broke a string of five consecutive 30-year TIPS auctions (issues and reissues) that set records lows. I think that is significant.

Here’s the Treasury announcement.

Posted in Investing in TIPS | 9 Comments