Are TIPS expensive? A look back into recent history …

A New York Times article with the headline ‘An Inflation Hedge Carries Its Own Risks‘ spells out why TIPS mutual funds appear to be overpriced, and possibly risky, after substantial gains. Some of its major points:

Investors who placed bets on mutual funds specializing in inflation-protected Treasury securities were among the bond market’s biggest winners over the last two years, even as other Treasury funds struggled. … “TIPS have gone through a period where just about everything has gone right for them,” said Robert Johnson, director of economic analysis at Morningstar. “Now the situation has changed, and they are looking quite expensive.”

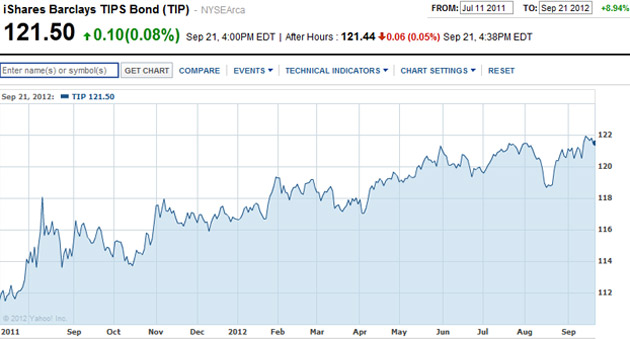
The surprise is that this article was written July 11, 2011, practically to the day that TIPS base yields began moving into negative and TIPS mutual funds started a strong move higher. Here is the chart for the TIP ETF, which has risen about 8.9% since July 11, 2011:

TIP return since July 2011

Obviously, you can’t trust the experts. But …

I will admit that back in July 2011, I agreed with this New York Times article. TIPS seemed pretty expensive. Looking back, boy, were we wrong. Yes, TIPS were expensive relative to history, but not expensive at a time of massive Federal Reserve manipulation in the Treasury market.

Since July 2011, yields have literally turned upside down to what I would call the ‘Real World.’ Now we are living in the ‘Fed World.’

Real World. On July 21, 2011, a 10-year TIPS auctioned with a yield of 0.639%, meaning that buyers would receive 0.639% above inflation over 10 years. That looked expensive at the time, but in retrospect …

Fed World. This week the Treasury reissued a 10-year TIPS with a yield of -0.75%, meaning that buyers were accepting 0.75% less than inflation for the next 10 years. They  were betting big on higher-than-expected inflation.

A yield of -0.75% is expensive, right? Can we finally settle on that? But it was another in a string of record-low yields for TIPS. Until we see that trend turn around, I think we can say the Fed World is still going strong.

Posted in Investing in TIPS | 12 Comments

10-year TIPS auctions at a record low -0.75%

The U.S. Treasury just announced that its reissue of a 10-year TIPS auctioned with a record-low yield to maturity of -0.75%. This is CUSIP 912828TE0, which will mature on July 15, 2022.

The previous record low was for this same Treasury Inflation-Protected Security, when it was first auctioned in July with a yield of -0.637%.

Breakeven rate. The 10-year Treasury closed today with a yield of 1.80%, setting the inflation breakeven rate for this TIPS at 2.55%. This means that inflation will have to average 2.55% for the next 10 years for this TIPS to beat a traditional Treasury. This is a near record-high breakeven rate (I think the record is 2.64%) for a 10-year TIPS, as shown in this chart from Michael Ashton’s E-piphany blog:

TIPS breakeven rate

The higher the breakeven rate, the more expensive the TIPS. Buyers were paying a lot at today’s auction, that is clear. (And I should point out that this same TIPS, when it first auctioned in July, had a much more modest breakeven rate of 2.17%.)

Reaction. The Wall Street Journal cited ‘lukewarm‘ support for this auction, despite the record-low yield. The article notes:

TIPS shield owner from inflation because their payouts increase as the consumer price index rises. But without inflation, buying at a negative yield means the investor will get a smaller amount of money paid back than originally lent out.

Because of newfound inflation concerns, prices on TIPS have soared recently–but perhaps so much so that it made Thursday’s auction a bit too expensive, analysts say.

Posted in Investing in TIPS | 14 Comments

Are TIPS a good investment in 2012?

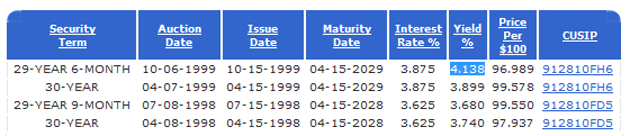
I get that question a lot. My quickest reaction is: ‘No.’ Treasury Inflation-Protected Securities were a really good investment back in 1999, when you could have bought a 30-year TIPS with a yield to maturity of 4.138% – that means 4.138% above the rate of inflation until 2029. That wasn’t just good, it was magnificent. It was auctioned Oct. 6, 1999.

In the 1990s, TIPS were an unknown product and the stock market was booming. No one was really considering TIPS and they were unloved. That resulted in some great buying opportunities:

Early 30-year TIPS auctions

That was then, and now? In 2012, TIPS are very much loved. And buyers are paying for that love. So much so that that the yield to maturity on CUSIP 912810FH6, which I praised above, is now -0.067% on the secondary market. This magnificent creature of 1999 is now a shriveled-up 17-year TIPS with a return that is negative to inflation. It isn’t pretty.

Why are TIPS so loved? TIPS and US Savings I Bonds are the only two investments on Earth that are 1) super safe, and 2) reward the investor for unexpected inflation. When investors feel fear, #1 is appealing. And when investors fear inflation, #2 is appealing. Right now, investors feel both fear and fear of inflation. That has driven TIPS yields to extremely low levels, negative to inflation well up the maturity ladder.

Other investments are super safe: Traditional Treasuries, of course, and Bank CDs with FDIC or NCUA insurance. But they also currently offer returns well below the rate of inflation, which let’s just round up to 2% currently. A 5-year Treasury pays 0.72% today, and a 5-year bank CD pays about 1.7%. A 5-year TIPS pays about -1.691% (plus inflation), which is extraordinarily low.

In rejecting that 5-year CD, a buyer of a 5-year TIPS is betting that inflation will average 3.39% over the next five years. Does that bet make sense at a time of muted inflation and very low economic growth? You’d have to fear something to make that bet.

On the other hand, world banks, huge hedge funds and multibillionaires can’t be investing in insured bank CDs. They are stuck with that 5-year Treasury as a super-safe choice, and then the breakeven inflation rate falls to a more reasonable 2.41%. If I was investing millions, I’d probably want that inflation protection.

So, are TIPS are good investment in 2012? Yes, if you happen to be a world bank, pension fund or hedge fund.

There is logic to the pricing of TIPS. But that logic doesn’t work as well for the small investor in September 2012. (By far, the best super-safe investment for the small investor is the I Bond, which pays the rate of inflation, minus nothing. You can sell it after five years with no penalty. But you can only buy $10,000 per year, per person.)

Who should buy TIPS? In 2012 – at these rates – TIPS are all about capital preservation. There is really no other reason to purchase them. Most likely, the return will be very low. The buyer will get his money back, absolutely. But TIPS and I Bonds are a vehicle for protecting your nest egg from the disaster of inflation.

Capital preservation means you probably have 1) a very large nest egg and 2) are nearing retirement or already retired. If both of those cases are true, I can still see TIPS as a reasonable investment in 2012. Inflation might be your worst enemy, and you should design your portfolio to protect against it.

For you, my suggestion for asset allocation is something like: 1) 25% in super safe investments like TIPS, I Bonds and bank CDS, 2) 25% in low-fee bond funds, 30% in dividend-paying stocks and index funds, and 20% in international stock and bond funds.

(Do I need to remind you that I am a journalist and not a financial adviser? That’s just my suggestion, nothing more.)

But I am young and just starting out investing! Well, the bad news is that TIPS are going to be a lousy investment. Seriously. You have to build wealth before you worry about capital presevation. In 1999, with TIPS paying 4% above the inflation rate, there was an unusual buying opportunity. That does not exist today. TIPS are expensive.

Should I sell my TIPS and TIPS funds?  I am strictly a buy and hold investor in TIPS. I have never sold a single purchase, going back 13 years. That is my style, but it might not be yours. TIPS have had a tremendous run, accelerating in mid 2011, as the Federal Reserve pumped massive amounts of cash into the money supply.

Some people might want to take profits. If you do, ask yourself this: Where will I put this money? Will it be in a similarly safe investment?  Will the money be earning zero percent in a money market fund for two years? Will I be changing my asset allocation?

Of course, parking the money might work, if the TIPS juggernaut somehow loses steam.

Posted in I Bond, Inflation, Investing in TIPS | 15 Comments

‘Headline’ inflation rises a sharp 0.6% in August

As expected, U.S. inflation ticked up sharply in August, rising 0.6% because of higher energy prices. This was the first increase of any kind since March. Higher gas prices accounted for 80 percent of the increase. Food prices rose 0.2 percent.

Read the full August report on inflation

The 0.6% increase in August is the ‘headline’ number (CPI-U) that holders of TIPS and I Bonds care about, because it adjusts the principal balance of TIPS upward and eventually sets the inflation-adjustment interest rate on I Bonds. So, in the crooked logic of TIPS investors, a 0.6% increase is a good thing, given the 0.3% decline in infation from April to July.

Monthly inflationIn the past 12 months, headline inflation has increased 1.7%. That’s down from a peak of 3.9% in September 2011 and below the Fed’s inflation target of 2%.

The Federal Reserve cares about ‘core inflation’ – which strips out the more-volatile energy and food. Core inflation in August was a very muted 0.1%, which should keep the Fed happy. Core consumer prices rose 1.9 percent in the past 12 months, the smallest annual increase in a year.

An Associated Press report notes that food prices have not yet figured into rising inflation:

The modest increase in food prices indicates the drought in the Midwest is not yet pushing up grocery prices. Some economists say that will happen in the comings months.

Posted in Investing in TIPS | 3 Comments

Next up: 10-year TIPS reissue auctions Sept. 20, 2012

10-year TIPS auctionThe U.S. Treasury announced today that it will auction a reissue of CUSIP 912828TE0 on Sept. 20, resulting in a 9-year, 10-month Treasury Inflation-Protected Security investment for buyers.

Read the auction announcement.

This TIPS was originally auctioned July  19, 2012, with a coupon rate of 0.125% and a record-low yield to maturity of -0.637%. Because the principal of a  TIPS investment also grows at the rate of inflation, TIPS buyers back in July were accepting -0.637% less than the rate of inflation over the next 10 years.

What about it? So now, two months later, what can buyers expect? More of the same. This TIPS trades on the open market, and today it closed with a yield to maturity of -0.730%, meaning next Thursday’s auction could set another record low.

You can check the daily yields here. The line you care about looks like this:

current rate

Notice that the accrued principal on this issue stands at 997, when it should be 1000 or more. Why? Because we have seen slight deflation in the last two months, instead of inflation. So July’s buyers got two slaps in the face: 1) negative yield and 2) negative inflation.

But deflation isn’t likely to continue. The August inflation report, due out Friday, could show a monthly rise of as much as 0.6%, which you could speculate indicates an annual rate of 7% or more. Don’t speculate. It won’t be that high. But headline inflation – the number that matters for TIPS buyers – could easily rise back to the 3% to 4% range we saw last year. Reasons? 1) The Fed today again launched a stimulus program with a plan to buy mortgage-backed securities, 2) turmoil in the Mideast threatens a spike in oil prices and 3) drought conditions in much of the country are forcing food prices up.

If  … and it is a HUGE if … inflation were to rise quickly in the next year, this TIPS reissue would end up being a very wise investment. If … on the other hand … the economy continues slogging along (and high oil prices could cause that), and inflation remains muted over the long term, this will be a fairly lousy investment.

I contend that TIPS bought and held to maturity will never be a horrible investment. You will get your money back. You may get a miserable return, but you will get your money back.

Look at the breakeven rate. The Wall Street Journal had an article this week titled ‘Uncle Sam Has an Inflation Deal for You‘ with the very odd premise that because the breakeven rate – comparing a TIPS versus a comparable Treasury – has been rising, TIPS are a good buy.

… the amount that investors have been willing to pay has risen noticeably. Ever since talk heated up that the Federal Reserve will engage in a third round of bond buying, implied bets on inflation have, too. The 10-year break-even rate has risen to 2.376% currently from 2% in late July.

But the article continued:

Perhaps the oddest thing about TIPS, though, is that they aren’t even pricier, whatever the Fed’s immediate plans. Today’s 2.39% break-even rate over 30 years not only is well below the actual average inflation rate of 3.8% since 1950.

OK, but I would still contend that TIPS are most attractive (‘cheap’) when the breakeven rate is around 2%. Where are we today? The 10-year Treasury closed today at 1.75%, well above the rate of 1.54% when this TIPS was auctioned on July 19. So the yield to maturity has declined at the same time traditional Treasuries are paying more.

The result: A breakeven rate, today, of 2.48%. Folks, that is a high breakeven rate. (It was 2.17% back in July, just saying …) When the breakeven rate rises, it means inflation fear is rising. And when inflation fear is rising, TIPS are expensive.

Update: On Friday, the breakeven rate rose even higher. The 10-year Treasury closed the day at 1.88%, while the July 15 2022 TIPS closed at -0.811%, pushing the breakeven rate out to 2.69%. If this trend continues a 10-year Treasury may actually look attractive.

I’d say keep an eye on the market yield of CUSIP 912828TE0 over the next week. Perhaps the breakeven rate will slip. If not, this auction is risky.

Posted in Investing in TIPS | Leave a comment