Details on the April 2011 5-year Treasury Inflation-Protected Security

On Thursday, April 21, the Treasury plans to sell $14 billion in five-year inflation-protected securities. The dated date is April 14, 2011, while the issue date is April 29. The TIPS mature April 15, 2016. Cusip number is 912828QD5.

Noncompetitive tenders must be received by 11:00 a.m. Thursday, and competitive tenders by 11:30 a.m. You can learn more at TreasuryDirect.gov.

Here is a .pdf with full details of the auction.

This is an original issue, not a reissue.

What kind of interest rate will I get? Not much in the base rate, which the Treasury pays you twice a year, but your principal will rise with inflation over the five years. At maturity, you will be paid your original investment plus inflation, except that …

This five-year TIPS will probably go off at a negative yield, somewhere around -0.2%.

Negative interest? It sounds crazy, doesn’t it? But it has been happening for shorter-term TIPS since last fall.

How does that compare with a regular 5-year Treasury note? The regular 5-year note currently pays 2.22%, which is better than a money market fund, but rather pathetic. The Fed’s current 5-year inflation prediction is about 2.1% per year on average, you can insert your chuckles … here. I expect it will be higher, but the key thing is, how much higher?

Why accept negative interest? It only makes sense if you expect inflation over the next five years to be higher than 2.4%, which is the the rate you get by taking the regular 5-year Treasury and adding on the negative 0.2% (or possibly 0.3%, depending on how the auction goes — and I honestly, I am unsure on how to predict what will happen Thursday.)

I did notice this: The University of Michigan’s median 5-year expected inflation rate jumped 0.3% in March to 3.2%, the highest reading since May-June 2008. Source.

If inflation ran at 3.2% over the next five years, this TIPS would be paying nearly 3%, and that is a lot better than the standard 5-year Treasury.

Conclusion … It’s hard to accept the possibility of a negative base interest rate on a 5-year TIPS, when long-time investors are used to base rates closer to 2%. Then again, what rate are you earning on our money-market fund? Or would you be willing to get 2.22% on a five-year Treasury? I wouldn’t.

Hold your nose and buy this 5-year TIPS? I am betting on the side of higher inflation and I say yes — but it will be a minimal investment. It can’t turn out too bad. I will hold to maturity.
Posted in Inflation, Investing in TIPS | Leave a comment

More on the upcoming 5-year Treasury Inflation-Protected Security

Larry Swedroe of Wise Investing posted a good analysis today on CBSMoneyWatch.com, talking about the the risk/rewards of TIPS versus conventional Treasuries.

Read his post.

He makes the case that even though the base yield on the 5-year TIPS is low by historical standards, it still makes sense when measured against a traditional 5-year Treasury. He says:

“The current yield on the five-year nominal Treasury is about 2.2 percent. With the Philadelphia Fed’s five-year inflation forecast at 2.1 percent, the expected real return is 0.1, meaning it’s still about 0.3 percent higher than the comparable TIPS yield. Again, given the relatively small risk premium, TIPS are still the preferred choice.”

Of course, there is a lot of other ways to invest your money, outside of Treasuries. But if you are looking for safety without inflation risk, buying this upcoming 5-year TIPS and holding it to maturity looks like a solid – if very boring – investment.


Posted in Investing in TIPS | Leave a comment

More on risk … TIPS mutual fund versus Total Bond Market

As I have noted, my bias is to buy TIPS through Treasury Direct and to hold them to maturity. If you can find a way to buy them through your broker and place them in a tax-deferred account, all the better. (And let me know how that worked.)

I also think that TIPS mutual funds are fairly risky right now, not super risky, but enough to keep in mind if you plan to dump a major investment into a TIPS fund right now.

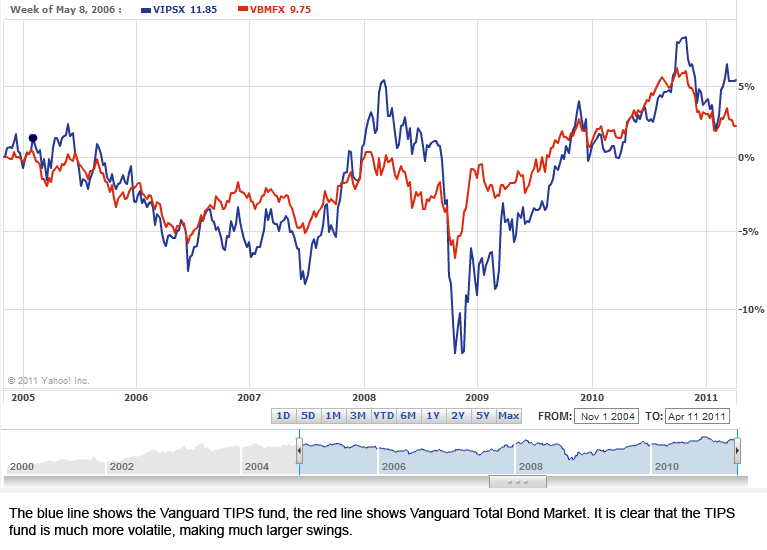
This chart helps make my point:

TIPS fund versus Total Bond Market
I have owned the Vanguard TIPS fund (blue line in chart) in the past — bought it in that nasty dip at the end of 2008 and then sold it in Sept. 2009 after a 9.1% capital gain (tax-free account, of course). I switched into Vanguard Total Bond Market, which is shown in red in the chart above.

VBMFX (Total Bond) is a pretty boring fund, and unloved. Right now, it has a yield of 3.33%. Its duration is 5. Its credit quality averages AA.

VIPSX (Vanguard TIPS) is pretty hot, the ‘inflation-fighter.’ Its duration is 5.33 and its credit quality is AAA, naturally. It yields 2.52%.

So the TIPS fund has higher duration and lower yield than the boring total bond market.

But the swings in yield of TIPS are obviously pretty dramatic, if you look at the chart above. If the TIPS base yield rises back to 2% or 2.5%, fairly normal levels, the owners of TIPS mutual funds are going to be in for a wild ride.

Posted in Investing in TIPS | Leave a comment

Upcoming 5-year TIPS auction

Update: This 5-year TIPS was auctioned April 21 with a base yield of -0.18%.

———————————————————

Announcement date: April 14, 2011

Security term: 5- year

CUSIP Number: 912828QD5

Auction Date: April 21, 2011

Issue Date: April 29, 2011

If you are interested in purchasing this security, go to TreasuryDirect.gov for more information.

Should you buy it? The last 5-year TIPS issue was in November 2010, and it went out at a yield of 1.33% above inflation. No way this April 2011 issue will have a yield that high. In fact, this TIPS could have a negative base rate of around -0.2% to -0.3%.

If you are holding to maturity:

Yes, if you have money parked in a money-market fund earning near zero. If inflation runs at 3.0% over the next five years, you would earn 2.8% on this TIPS, better than you can get with a bank CD.

Or, maybe you want to take some stock market profits off the table.

Another benefit is that you can roll this over in 5 years.

No, if you think the base rate on TIPS will be moving soon to near its historic normal rate around 2%. Then I think it would make sense to keep the money parked and wait for a better rate.

Personally, I plan to buy a modest share of this TIPS.

Update:

Yes or no on the 5-year Treasury Inflation-Protected Security?

Posted in Investing in TIPS | 2 Comments

Are TIPS mutual funds a risky investment?

The answer is a resounding yes – there is risk. And I think that the TIPS mutual funds and ETFs are especially risky right now, even though they are very popular. You see them recommended as ‘inflation fighters’ in magazines every month.

(I recommend holding TIPS directly to maturity, no risk in that investment, unless you worry that the Treasury is going to default. You may lose out on some potential interest, but you won’t lose your money.)

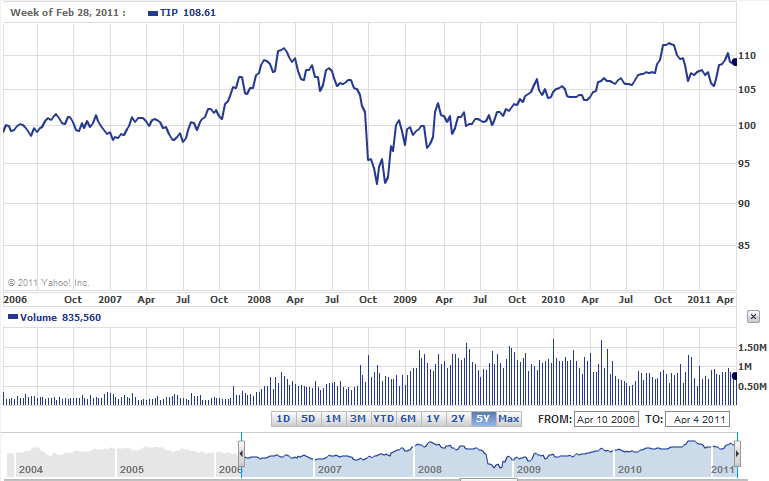
Look at this five-year chart of the TIP ETF:

1) We are sitting very close to a 5-year high for this ETF.

2) The base-rate paid on 10-year TIPS is very low, based on history. When that base rate starts rising, TIPS mutual funds will lose value.

3) A more normal value for this fund appears to be around 100, instead of the current 108.61.

This part of the chart is the most interesting:

During the financial crisis of 2008, there was a sudden fear of deflation, meaning negative returns on TIPS. So bond buyers began demanding a premium on the base rate, which was driven from less than 2% before the crisis to about 3.5% at the peak of the crisis.

This peak of fear was a excellent time to buy TIPS and TIPS mutual funds. I bought into Vanguard’s TIPS fund on Dec. 1, 2008 at $11.14. It is now $13.21, a capital return of 18.5%, on top of the interest payments.

You can’t expect returns like that from a TIPS fund — I actually switched out in September 2009 at 12.44, into the Total Bond Fund, which looked a little less risky.

(How did I do on that? Pretty much a wash. Vanguard TIPS (VIPSX) returned 6.17% in 2010, while Total Bond (VBMFX) returned 6.42%.)

The point is … if a TIPS fund can give you capital return of 18% in two years, it can also give you an equal loss. There is risk, and since the base rate is so low right now, I think these TIPS funds are risky.

Posted in Investing in TIPS | 1 Comment