New I Bond variable rate will rise to 1.54% on Nov. 1, 2015

The September inflation numbers are in, and this is a big number for I Bond investors. The number closes out the March to September period the Treasury uses to set the variable (inflation-adjusted) rate on I Bonds on Nov. 1. The new rate will be 1.54%, annualized, for I Bonds purchased from Nov. 1, 2015, to April 30, 2016.

Here is the full set of numbers, which I keep updated on my Tracking Inflation and I Bonds page:

I bond

I Bonds pay a composite interest rate comprised of two interest rates – the permanent fixed rate (currently 0.0%) and the variable inflation rate (currently -1.60% annualized). On Nov. 1, the variable rate will rise to 1.54%, but we won’t know the new fixed rate until the Treasury announcement – probably on Nov. 2 since Nov. 1 falls on a Sunday.

Eventually, this new 1.54% variable rate will activate for all holders of I Bonds, the starting date depends on when the month you first bought the I Bond. Holders of older I Bonds with fixed rates above 1.60% will appreciate the new rate, because it is essentially 3.14% higher than you were getting the last six months. Read this for more information.

On Nov. 1, it’s possible the Treasury could slightly increase the I Bond fixed rate, but I’d say that still remains unlikely. If the rate rises, I Bonds become a screaming buy in November and then again in January – since you can only buy $10,000 per person per year.

Even if the fixed rate doesn’t rise, I Bonds remain a super-safe and reasonable investment, especially since you can sell them after one year with a minor (three month) interest penalty. But there was no reason to buy them from May to November, when the composite rate was locked at 0.0%. After Nov. 1, the attractiveness returns.

The September inflation numbers

The Consumer Price Index for All Urban Consumers (CPI-U) decreased 0.2% in September on a seasonally adjusted basis, the U.S. Bureau of Labor Statistics reported today. Over the last 12 months, inflation was flat – 0.0%.

It was no surprise that energy prices were the primary cause of the deflationary number. Gasoline prices fell a massive 9.0% in the month and are down 29.6% over the last 12 months. Apparel prices also dropped, down 0.3%. Food prices, however, were up a rather sharp 0.4% and have risen 1.6% over the last year.

Holders of TIPS and I Bonds are also interested in non-seasonally adjusted inflation, which is used to adjust the principal balances on Treasury Inflation-Protected Securities and to set future interest rates on I Bonds. In September, the inflation index stood at 237.945, down 0.16% from August’s number, which was also down 0.14%.

This means that principal balances on TIPS will continue to decline through November 2015. It’s also interesting to note that the CPI-U inflation index stood at
238.031 in September 2014. While the BLS says inflation was ‘flat’ over the last 12 months, it actually declined 0.036%, which rounds to 0.0%.

Here is the inflation trend over the last 12 months:

inflate

Posted in I Bond, Inflation | 2 Comments

Up next: 30-year TIPS reopens at auction Oct. 22, 2015

The Treasury will announce this tomorrow at 10 a.m., but we all know this will be the reopening of CUSIP 912810RL4, creating a 29-year, 4-month Treasury Inflation Protected Security. Because it has a established coupon rate of 0.75%, it is going to auction at a substantial discount. Here is the history of this TIPS:

  • First auctioned Feb. 19, 2015, with a real yield of 0.842%. That set up the coupon rate of 0.750% – the coupon is always set at the 1/8% notch below the yield set at auction. And so it sold at a price of about $97.93 for $100 of value. (This shows how even a minor interest rate adjustment causes a big swing in price for a 30-year Treasury.)
  • It was reopened June 18, 2015, with a real yield of 1.142%, 30 basis points higher. That resulted in an adjusted price of $90.59 for about $100.47 of value (figuring in accrued inflation). The unadjusted price was $90.17, meaning this TIPS lost almost 8% of its value in four months.

Where does it stand today? Because this TIPS trades on the secondary market, we can get a good estimate of its current value, one week ahead of the auction.

  • Bloomberg’s Current Yields page shows that this TIPS is trading with a real yield of 1.17%, not too far off that June number. The price is quoted at $89.34 for $100 of value.
  • The Wall Street Journal’s Closing Prices page shows this TIPS – which matures 2045 Feb 15 – closed today with a yield of 1.174% and an asked priced of about $89.50.
  • The Treasury’s Real Yields Curve page estimates that a full-term 30-year TIPS closed today with a real yield to maturity of 1.19%. This is in line with the other numbers, since a full-term TIPS should yield higher than one maturing 8 months earlier.

The inflation adjustment. Keep in mind that this TIPS will have an inflation index of 1.01213% on Oct. 30, the settlement date. That means investors will be buying an extra 1.2% of inflation adjustment, and that will raise the cost. The auctioned yield remains the same, you will just buy a little extra principal.

Prospects. I recommend buying TIPS and holding them to maturity, so if a 30-year TIPS fits into your expected lifespan, this TIPS could be interesting. The coupon rate of 0.750% will mean you won’t be collecting much in cash payments, however. This TIPS is probably best suited to a tax-deferred account.

If you are buying as a trader, you can see that a 30-year TIPS is a very volatile investment. Do you think long-term interest rates are peaking? Then this is a buy. If you think they will rise higher, hold off and look at the next 30-year auction, in February 2016.

Here is the history of all 29- to 30-year TIPS auctions:

30-year TIPS

Posted in Investing in TIPS | 2 Comments

10-year TIPS reopening auctions with a real yield of 0.60%

The Treasury jumped the gun – it never does that – and posted results of today’s auction of a 10-year TIPS reopening three minutes early! It’s Friday, folks, and the Treasury people are ready to go home.

The reopening auction of CUSIP 912828XL9 – creating a 9-year, 10-month Treasury Inflation Protected Security – resulted in a real yield to maturity (after inflation) of 0.60%.

Because this TIPS has a coupon rate of 0.375%, buyers are getting it at a discount. The unadjusted price was $97.86 for $100 of par value. But because this TIPS will have an inflation index of 1.00637 at the settlement date of Sept. 30, the adjusted price rises to about $98.49 for $100.64 of value.

The yield of 0.60% is the highest for any 9- to 10- year TIPS since an auction in September 2014, but it is about 15 basis points below the market rate on Thursday, the originally-scheduled date of the auction. The Treasury delayed the auction by one day because of the imminent interest-rate announcement by the Federal Reserve.

The Treasury did well by delaying. The Thursday price would have been about $96.69, about 1.2% less than the Friday result.

Inflation breakeven rate. A nominal 10-year Treasury is trading right now with a yield of 2.16%, setting up an inflation breakeven rate of 1.56% for this TIPS. It will outperform a traditional Treasury as long as inflation averages more than 1.56% over the next 10 years. This puts this TIPS solidly in the ‘cheap’ range – a good buy versus a traditional Treasury.

Posted in Investing in TIPS | Leave a comment

Checking in on today’s 10-year TIPS reopening

Like I always say .. a lot can happen in a week. Or even days. What was shaping up to be a very attractive auction today – creating a 9-year, 10-month Treasury Inflation-Protected Security – has turned a bit sour.

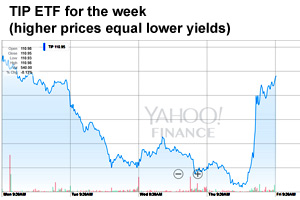
four days of TIPOn Wednesday, the August inflation report became a deflation report, with prices dipping 0.1% for the month. Deflation isn’t a good thing in the TIPS market, and that sent the TIP ETF dipping below my long-watched $110 level. The yield on a 10-year TIPS hit 0.73%, highest of the year.

But  the deflation news bolstered spirits for the Federal Reserve’s interest rate ‘doves.’ On Thursday, the Federal Reserve put off raising short-term interest rates, which have been set at near-zero for nearly seven years. And the TIPS market cheered. The yield on a 10-year TIPS dropped 10 basis points, to 0.63%.

And now it’s Friday, auction day. Let’s see where we stand at 9:45 a.m.:

  • Today’s auction is a reopening of CUSIP 912828XL9, with a coupon rate of 0.375%. Bloomberg’s Current Yields page shows it is trading this morning with real yield to maturity of 0.58% and a price of about $98 for $100 of value.
  • The Wall Street Journal’s Closing Prices page shows this TIPS ended Thursday with yield of 0.604% and a price around $97.50.
  • The TIP ETF opened up this morning — it is up more than 1% in two days. That means lower yields.

That one day delay – costly for investors, great for the Treasury.

If this TIPS had been auctioned at its normal time, closing at 1 p.m. Thursday, it would have generated a real yield of about 0.75% – the highest number in more than four years of 9- to 10-year TIPS auctions.

Instead, it will now go off somewhere around 0.58% — 18 basis points lower. It will cost investors more than 1% more than it would have 24 hours ago. This TIPS closed Wednesday with a price of about $96.69. Today’s price could be right around $98.

Amazing.

Although I already have a small investment in CUSIP 912828XL9, I’ll be skipping this auction. This TIPS will be reopened one more time – in November.

Posted in Investing in TIPS | Leave a comment

And the Federal Reserve said: ‘No way’

The least surprising news of the week beeped on my telephone as I waited in line to check out at Costco Thursday afternoon. News alert: ‘Fed stands pat on interest rates.’

A better headline would have been: ‘Fed thumbs its nose again at savers.’ And so we will continue for a few months more, at least, of very-close-to-zero interest rates on our savings. Predictable, because the Fed clearly doesn’t have the courage to lift its ‘extraordinary measures’ that have continued nearly seven years.

Here was the USA Today headline on Dec. 17, 2008: ‘Fed cuts interest rates to near zero to combat economic recession‘. It’s an interesting story to look back on, because at the time it seemed to be a remarkable move. Here are some quotes:

The dramatic move sent stocks soaring as the Dow Jones industrial average surged 4.2% and broader indexes jumped more than 5% …

“The Federal Reserve will employ all available tools to promote the resumption of sustainable economic growth and to preserve price stability,” the Fed said. “In particular, the committee anticipates that weak economic conditions are likely to warrant exceptionally low levels of the federal funds rate for some time.”

The Dow rose 359.61 to 8,924.14 … “All in all, it’s good news for stocks,” said Jack Ablin, chief investment officer at Harris Private Bank. “It gave the market a little bit more than they expected.”

It worked, right? In the ensuing seven years, the stock market has doubled, the unemployment rate has dropped from 10.1% in October 2009 to 5.1% today. Economic growth – measured by GDP – has risen from -0.92%  in December 2008 to 3.91% as of March 2015.

All these things indicate a pretty ordinary – possibly even healthy – economy. And yet the extraordinary measures continue.

The one factor in the Fed’s favor is overall inflation, which has dropped to 0.2% over the last 12 months as gas prices have fallen dramatically. But when you strip out gas and food, inflation has been running at 1.8%, still mild but close to an acceptable target.

“Inflation is anticipated to remain near its recent low level in the near term but the Committee expects inflation to rise gradually toward 2 percent over the medium term,” the Fed said in its minutes released today.

And then the Fed placed thumb to nose and wagged: “To support continued progress toward maximum employment and price stability, the Committee today reaffirmed its view that the current 0 to 1/4 percent target range for the federal funds rate remains appropriate.”

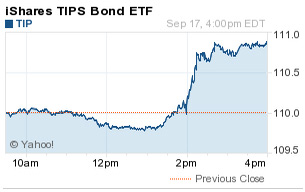
tip etfThe TIPS market reacted with glee, driving the TIP ETF up 0.78% for the day, closing at $110.87, one day after dipping below the magic $110 number. The Treasury’s estimate of the real yield for a 10-year TIPS dropped 10 basis points, from 0.73% on Wednesday to 0.63% today.

All of this comes on the eve of a delayed auction for the reopening of a 10-year TIPS. The Treasury is going to save a lot of money because of that one-day delay.

Sigh.

Posted in Investing in TIPS | 4 Comments