The Treasury will announce this tomorrow, but I can give you the scoop on next week’s auction: A new-issue 10-year Treasury Inflation-Protected Security. This will be CUSIP 912828UH1. (Update: Here is the Treasury’s announcement.)
The coupon rate? That will be set at auction, but … come on … it will end up being 0.125%, the lowest coupon rate the Treasury will set on a 10-year TIPS.
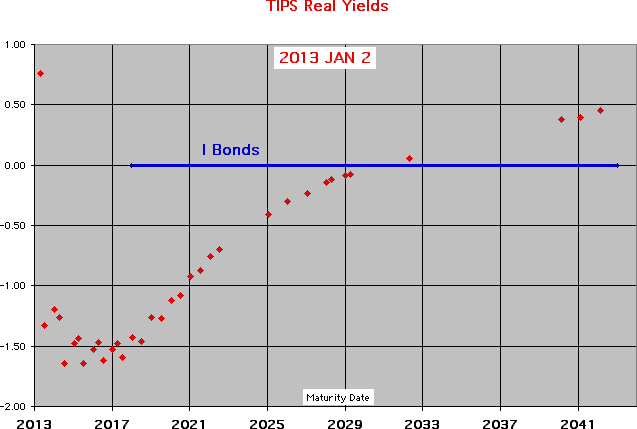
Yield to maturity? This is much harder to predict with super accuracy. The closest existing issue now trading on the secondary market matures 2022 Jul 15 and it has a yield to maturity of -0.738%, meaning buyers are accepting a rate of return 0.738% below inflation for 10 years. In theory, this TIPS with a maturity six months longer, ought to have a slightly better rate. So maybe around -0.69%? Just a guess.
Will it set a record low for yield? Good question. It is going to be close. The record low yield for any 9- to 10-year TIPS at auction is -0.750%, for a reissue last year in September. Unless we see a lot of turmoil in the stock market in the next seven days, that record looks pretty safe. In fact, this new issue will probably rise above the -0.720% for a 9-year, 8-month reissue in November 2012.
TIPS failing to set record lows is a nice trend, in my opinion.
Here are the recent auction results for 9- to 10-year TIPS:
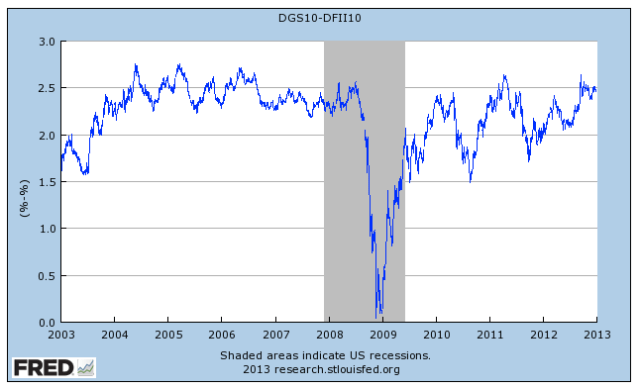
 Please note …. Just two years ago, on Jan. 20, 2011, a 10-year TIPS auctioned with a yield to maturity of 1.17%. That is 1.17% above inflation, instead of today’s 0.7% below inflation. Two years ago, the Treasury market was ‘normal.’ Today it is ‘abnormal.’ And that means this 10-year TIPS should probably be ignored.
Unless … you really, really believe massive inflation is coming around the corner.
Uh .. about that lurking inflation. Today the Bureau of Labor Statistics announced that headline inflation (CPI-U – the one that matters to TIPS buyers) was unchanged in December. For the year, consumer prices rose only 1.7%, down from 3% in 2011.
That sort of presents a double whammy for recent TIPS buyers, who are seeing very low inflation, but earning a yield well below inflation. Ouch. (When you take a yield below inflation, you tend to cheer for higher inflation, as morbid as that sounds.)
Core inflation, which the Fed wants to keep under 2.5%, rose only 0.1% in December and 1.9% for year year. Here are the monthly increases for headline inflation:




Thank you! I was not aware that the bid/ask spreads were different when the market is open vs closed.