Recapping 2012: The year in TIPS

It’s been a sorry year for buy-and-hold investors in Treasury Inflation-Protected Securities, with yields plummeting to ever-lower all-time records. That means TIPS – like all Treasuries – are very expensive and produce little income. There are currently 35 TIPS issues trading on the secondary market, and 32 of those have negative-to-inflation yields. You have to go all the way out to an issue maturing in February 2040 to get a positive yield, 0.256% plus inflation.

TIP ETF

The TIP ETF saw some volatility in prices but still had a 4.7% gain for the year. Click on image for larger view

On the other hand, TIPS traders and mutual fund holders have had a decent year. Even though the TIP ETF took a dip after the Federal Reserve announced QE4 this month, its net asset value is up about 4.7% for the year.

Just like last year, TIPS buyers found their best purchases early in the year, as TIPS yields declined steadily. Here’s a recap of the year’s auctions:

10 year TIPS, CUSIP 912828SA9

First auctioned: Jan. 19, 2012, with a yield-to-maturity of -0.046%. This was the first 10-year TIPS in history to auction with a negative yield, but the rate was expected to be lower just before the auction. So this one ended up being the best buy of the year.

Reissued: March 22, 2012, with a yield to maturity of -0.089%. Today, this still looks attractive.

Reissued: May 17, 2012, with a yield to maturity of -0.391%.

Hard to believe this issue currently trades at -0.841%, meaning the January buyers are sitting on a gain of more than 8%.

3o-year TIPS, CUSIP 912810QV3

First auctioned: Feb. 16, 2012, with a yield to maturity of 0.770%. I viewed this issue positively back in February, despite the long-term commitment. It actually went off at a discount to its 0.75% coupon rate (that’s a rarity in TIPS auctions these days).

Reissued: June 21, 2012, with a yield to maturity of 0.520%.

Reissued: October 18, 2012, with a yield to maturity of 0.479%. Each of these auctions set a record low for a 30-year TIPS.

Today this issue trades on a secondary market at 0.335%, meaning the original buyers are sitting on a capital gain of more than 10% for an issue they bought at a discount.

5-year TIPS, CUSIP 912828SQ4

First auctioned: April 14, 2012, with a yield to maturity of -1.080%. Although I have tried to warm up to short-term TIPS, I just can’t accept a yield more than 1% below inflation. Back in April, I issued a call to buy I Bonds instead, which was probably my wisest advice of the year.

Reissued: Aug. 23, 2012, with a yield to maturity of -1.286%.

Reissued: Dec. 20, 2012, with a yield to maturity of -1.496%. Each of these auctions set a record low for a 5-year TIPS.

This issue currently trades on the secondary market at -1.485%, about where it auctioned 10 days ago.

10-year TIPS, CUSIP 912828TE0

First auctioned: July 31, 2012, with a yield to maturity of -0.637%. By mid-year, TIPS yields were nearly hitting rock bottom. It’s significant that they have been pretty much holding at these very low levels for six months — despite the ‘fiscal cliff’ scare and the Fed’s commitment to QE4.

Reissued: Sept, 20, 2012, with a yield to maturity of -0.750%.

Reissued: Nov. 21, 2012, with a yield to maturity of -0.720%. This auction was a milestone because the TIPS yield didn’t set a record low — it’s been many months since that happened.

This issue currently trades on the secondary market at -0.787%, a bit lower but still pretty close to the original auction price.

Posted in Investing in TIPS | 7 Comments

4-year, 4-month TIPS auctions at a record-low -1.496%

Yes, I knew there was a TIPS auction today, and actually thought about it around noon. But then I pretty much erased it from my mind. I mean, who really cares? Who is actually buying this thing?

Well, today’s auction for CUSIP 912828SQ4, effectively a 4-year, 4-month Treasury Inflation-Protected Security, resulted in a yield to maturity of -1.496%, meaning that today’s buyers are accepting a return 1.496% below the rate of inflation for the next five years.

Need I point out that inflation for the last 12 months is currently running at 1.8%? Indicating a current return for this TIPS of about 0.304%?

How … exciting … Well we did set another record low yield for any 4- to 5-year TIPS at auction. The previous low was -1.286% for this same TIPS when it was reissued in August.

But really, this was a very unattractive issue, because even if inflation perks up in the future, it will probably miss most of this 4-year, 4-month term. The current breakeven rate for a 5-year TIPS is 1.91%, with the 5-year nominal Treasury yielding 0.77%.

Yes, inflation will probably average more than 1.91% over the next five years, so this TIPS beats a nominal Treasury. But if you look at a super-safe insured 5-year bank CD, you can get 1.8% right now, pushing the breakeven inflation rate up to a much-more-iffy 3.3%.

Why would anyone buy this TIPS?

Posted in Investing in TIPS | 1 Comment

Inflation turns to deflation in November

The U.S. Labor Department reported today that the ‘headline’ consumer price index fell 0.3% in November, primarily because of a big drop in gasoline prices. In the past year, consumer prices have risen 1.8 percent.

You can read the full report here

This headline number – technically called the Consumer Price Index for All Urban Consumers (CPI-U) –  is the one watched by holders of inflation-adjusted TIPS and I Bonds. The decline in November means a 0.3% decrease in the principal balance of a TIPS, and will cause a lower future interest rate for I Bonds.

The Federal Reserve watches the ‘core’ inflation rate, minus food and energy. This index rose 0.1% in November, which continues a trend of mild inflation.

This fall’s decline in gas prices has offset a late-summer bump in inflation, as shown in this chart generated by the Labor Department:

November inflation

From the Associated Press report:

“In simplest terms, inflation is not a problem,” Jim Baird, chief investment strategist at Plante Moran Financial Advisors, said. Lower inflation “is a real positive that should provide modest relief for households dealing with limited income growth.”

High unemployment and slow wage growth have made businesses reluctant to raise prices. Many worry higher prices could drive away customers. That’s helped keep inflation tame.

Posted in Investing in TIPS | 1 Comment

Fidelity’s outlook for TIPS: Clear skies, but threat of fog?

Somehow I own a fractional share of the Fidelity Inflation-Protected Bond Fund (FINPX) and so I get its annual and semi-annual reports. As I’ve noted before, the managers of this fund – William Irving and Franco Castagliuolo – are unusually frank in their ‘managers overview’ in each report. So their opinions perk my interest.

You can read the Sept. 30, 2012, report here.

TIPS have been an incredible investment over the last two years, combining safety with decent capital returns. This Fidelity fund, FINPX, has seen a year-to-date increase of 7.15% in net asset value. That nicely tops Vanguard’s Total Bond Market gain of 4.26% in net asset value. (Uh … I own the Total Bond Market, not FINPX, a decision I made at the perfectly wrong time of spring 2011.)

Below are some excerpts from their report, which I think lays out pretty well the positives and potential negatives of TIPS (fund) investing. On the one hand, we know that the Federal Reserve is committed to keeping interest rates very low in the near- and even mid-term future. And then there is the impending fiscal cliff, which in a worst-case scenario could cause deflationary pressures. Although the Fidelity managers don’t mention this, serious deflation would boost traditional Treasuries, but could ravage TIPS, which are an inflation-protection investment.

The one thing TIPS investors – especially those investing in funds like FINPX – might lose sleep over is a ‘miracle’ resolution of these problems, causing a stock market boom, employment growth, economic expansion. In those conditions, almost certainly, TIPS yields will rise, along with the overall Treasury market.

TIPS yields are sensationally low. Wildly low. Bubbly low. On the other hand the Federal Reserve presents a nice bodyguard for TIPS investors: Keeping rates ultra low by manipulating the Treasury market, while at the same time prompting inflationary fears, which in turn increases the attractiveness of TIPS.

question one

…

    Question 2


Posted in Investing in TIPS | 1 Comment

Next up: 5-year TIPS reissue auctioning Dec. 20, 2012

The Treasury on Thursday will announce its last 2012 auction of a Treasury Inflation-Protected Security, mostly likely a reopening of CUSIP 912828SQ4 which matures on April 15, 2017.

UPDATE 12/13/12: The Treasury confirmed today that the auction is a reissue of CUSIP 912828SQ4 … read the announcement.

This creates a 4-year, 4-month TIPS – the shortest maturity TIPS you can buy directly from the Treasury. It carries a coupon rate of 0.125%, but the yield to maturity is likely to around -1.551%, where this issue was trading Friday on the secondary market. Buyers will be paying about a 7% premium upfront to get that 0.125% coupon rate.

Attractive? No. This TIPS has only one thing going for it – it matures in 4 years, 4 months. Otherwise, it guarantees a return of 1.55% below inflation during a time of relatively mild inflation. The return is likely to end up being about 1%. You can do better with a 5-year bank CD — some are offering 1.8% today on a 5-year CD.

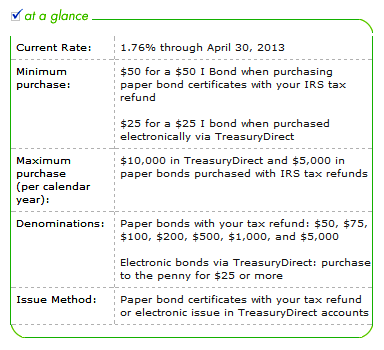
If you are a big hedge fund looking to park money safely, or a foreign national bank stashing reserves, this TIPS makes sense. Otherwise, there is one very important alternative you should consider:I Bonds at glance

  • Have you made your I Bond purchase for 2012? If not, this is an investment you need to make before Dec. 31. An I Bond will pay the rate of inflation over the next five years, when you can sell it without penalty. This investment is a no-brainer versus a 5-year TIPS — inflation rate versus inflation rate minus 1.55%.
  • I Bonds carry a base interest rate, which is currently zero, plus an inflation-adjustment interest rate that changes every May and November. The current rate through April 30 is 1.76%. An I Bond you buy before Dec. 31 will pay an annual rate of 1.76% over the next six months.
  • There are also key tax advantages to I Bonds, since the federal income tax is deferred until the bond is sold. You can hold an I Bond 30 years without paying any tax. With a TIPS, all income is taxable in the current year, even the inflation adjustment to principal, which you don’t receive until the TIPS matures.
  • Why is Dec. 31 important? The problem with I Bonds is each person is limited to a $10,000 purchase each calendar year (plus an option to get paper I Bonds instead of an income tax refund.) If you buy $10,000 today, you can buy another $10,000 in January.

I suspect that most people reading this blog have already bought I Bonds up to the limit in 2012. But if you haven’t, I suggest going to TreasuryDirect.gov to start the process today. There is no fee, no commission. Your money is 100% invested with the U.S. government.

Posted in I Bond, Investing in TIPS, Savings Bond | 3 Comments