Federal Reserve: Let’s keep interest rates low until 2014

Because I am a saver, not a borrower, I am not a big fan of our current super-low interest rates, especially in safe investments like Treasuries, money market accounts and bank CDs. So I have been hoping to see some end to this low-rate tunnel, which in theory was going to come in mid 2012.

But no … as you can see from this Associated Press report today:

The Federal Reserve went further than ever Wednesday to assure consumers and businesses that they’ll be able to borrow cheaply well into the future.

The Fed pushed back the date for any likely increase in its benchmark interest rate by at least a year and a half, until late 2014 at the earliest.

What this means. Obviously, the Fed is very worried about the world economy, especially with warnings this week from the IMF about Europe’s dismal condition. So the Fed is promising (practically) that it will hold short-term rates near zero for 2+ more years. The stock market, in the short term, is going to like this, because when investors have no other options for inflation-beating returns, the stock market looks very attractive. And right now Treasuries – including Treasury Inflation Protected Securities up to 10 years – aren’t offering inflation-beating returns. And we saw the stock market rise today after the Fed announcement.

For TIPS you already own. Your past investments look rock solid. I’m still not a fan of over-bought TIPS ETFs and mutual funds, but you can see the Fed gave owners a nice present today:
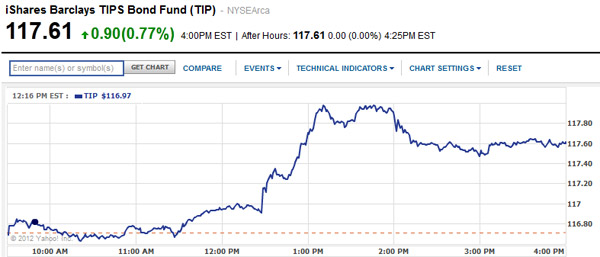
One day TIP performance

For TIPS buyers in the near future: The news is not so good. We can expect these super-low rates to continue. When a TIPS is paying a real return below zero or near zero, TIPS are not an attractive long-term investment, in my opinion. We possibly face many more months of these sub-par, and unattractive, returns.

The Fed is trying to force you to look to the stock market, especially dividend-paying stocks. That might be a good option, but there is risk. And the stock market has had a very nice run.

Joe Bel Bruno of the Los Angeles Times summed this up nicely today: Savers are getting screwed. Those are my words. not his. Here is his succinct summary:

The Fed’s latest maneuvering to resuscitate the ailing economy has already sent yields on government bonds — already hovering at generational lows — even lower. The yield on the benchmark 10-year sank to a measly 1.96% on Wednesday. Meanwhile, the amount of money you’re making on money markets or savings accounts continues to be microscopic. The average one-year CD yields is just 0.67% — down from 2.4% four years ago and 3.75% in 2007.

Forget the old adage about a penny saved being a penny earned. Borrowers win and savers lose in this environment.

And inflation in the future?  I will refer you to one of my favorite bloggers, Michael Ashton (The Inflation Trader) and his post today:

Despite the obvious train wreck, investors are not fleeing into deflation insurance. Quite the contrary: since September, both spot and especially 5-year forward inflation expectations have been rising sharply. I think these investors have it right: … policymakers clearly will attempt to err on the side of higher prices rather than lower prices.

TIPS buy-and-holders – probably the most conservative investors on Earth – are left with this sad conclusion: Stomach horrible yields and hope for higher inflation.

Yech.
Posted in Investing in TIPS | 4 Comments

10-year TIPS auctions at -0.046%, a record low

The Treasury today announced that its new issue 10-year Treasury Inflation-Protected Security, CUSIP 912828SA9, auctioned at a yield to maturity of -0.046%, the lowest rate ever for a 10-year TIPS and the first-ever negative yield for a 10-year TIPS.

As expected the TIPS has a coupon rate of 0.125%, meaning that buyers of this new issue will need to ‘pay up’ — about $101.66 for each $100 to produce the effective yield of -0.046%. This TIPS matures Jan. 15, 2022.

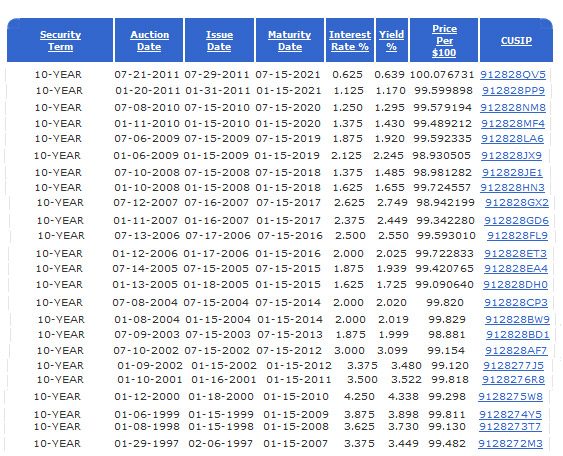
The previous record low for a 10-year TIPS new issue was 0.639% for the security auctioned  July 21, 2011. That is the only other new issue that has ever gone below 1% yield to maturity.

(The principal balance of a TIPS issue continues to grow with inflation until maturity. In effect, buyers of today’s new issue were accepting the rate of inflation minus 0.046% for 10 years. Keep in mind that a traditional 10-year Treasury is paying 2.01% today, meaning that inflation would have to run just 2.056% over the next 10 years to make this TIPS attractive versus the traditional 10-year. It’s a reasonable conclusion.)

Reaction to the auction, reported by Bloomberg:

“You’re losing purchasing power for the privilege of lending to the U.S. government,” said Eric Van Nostrand, an interest-rate strategist in New York at primary dealer Credit Suisse Group AG. “The success of this auction suggests demand for TIPS remains strong.”

Posted in Investing in TIPS | 5 Comments

Reader question: Is there a right time to sell an I Bond?

Good question on I Bonds today from reader Dan:

From what I read here and elsewhere, that base rate of 0% holds for the full 30 years and the variable part changes each 6 months. Is it ever the case that after a year one would want to cash out the I-bond and repurchase at some higher rate? Say the base rate went up to 1%. Would you sell your 0% i-bond and repurchase? Or does this never pay off to do that?

Dan, one of the big advantages of an I Bond is that you can sell out after one year (with a three-month interest penalty) and after 5 years with no penalty, but you can also continue to hold that I Bond for 30 years. That is a great deal of flexibility. After one year, you can re-evaluate the market and make a choice.

I view the current I Bond with a base rate of 0% as a short-term investment, possibly one year and possibly longer if TIPS continue running at zero to negative base interest, before inflation.

(Traditionally TIPS have paid up to a 1 percentage-point premium over I Bonds because I Bonds have the advantage of tax-deferred interest and better deflation protection. That premium has now been reversed – TIPS under 10 years now carry a negative base rate – giving I Bonds a clear advantage.)

If, in a year, I Bonds were paying a base rate of interest of 1% versus the 0% today, it would be a no-brainer to sell the current I Bond and buy the new one. You would want to lock in that 1% interest rate premium, possibly for 30 years.

But interest rates would have to change drastically for I Bonds to pay 1%. A more likely scenario would be that I Bonds continue to pay a zero base rate but a 10-year TIPS base rate rises to 1%. In that case, you’d have an interesting choice.

Another possibility is that inflation would turn to deflation. In that case, a year from now, the current I Bond might be paying zero total interest – zero base plus zero inflation. (This happened from May to October 2009 when the six-month inflation rate was running at -2.78%, but the I Bond base rate was then 0.1%)

If that happened again, you might consider selling the I Bond and buying another investment (possibly a bank CD) with some positive interest. Or you could ride out the six months with no interest.

Here is a chart from ForBestAdvice.com that shows how the base and inflation-adjusted interest rates have changed for I Bonds:

I-Bond Rate History
Period 6- Month Semiannual
inflation rate
Base Rate 6- month
Earnings Rate
November 1, 2011 – April 30, 2012 +1.53%
0.00%
3.06%
May 1, 2011 – October 31, 2011               +2.30%
0.00%
4.60%
November 1, 2010 – April 30, 2011 +0.37%
0.00%
0.74%
May 1, 2010 – October 31, 2010              +1.54%
0.20%
1.74%
November 1, 2009 – April 30, 2010
             +1.53%
0.30%
3.36%
May 1, 2009 – October 31, 2009              -2.78%
0.10%
0.00%
November 3, 2008 – April 30, 2009            +2.46%
0.70%
5.64%
May 1, 2008 – October 31, 2008           +2.42%
1.40%
4.84%
November 1, 2007 – April 30, 2008           +1.53% 1.20% 4.28%

People who bought I Bonds  up to April 2009 certainly made out very well, even with six months of no interest from May to October 2009. In the periods before and after, they got an excellent return.

Posted in I Bond | 3 Comments

10-year TIPS auction: The announcement

The U.S. Treasury today, as expected, announced its Jan. 19 auction of a new 10-year Treasury Inflation-Protected Security.

Here it is if you want to view it (.pdf)

But that pdf won’t tell you much. It is a 10-year TIPS, yes. It is CUSIP 912828SA9. The auction date is January 19, 2012. OK, we knew that.

What is the coupon rate, the actual base rate this TIPS will pay over the next 10 years? Well, that’s not mentioned. (For new issues, both the price and the coupon interest rate will be determined by the auction.) Let’s assume the coupon rate will be the lowest  the Treasury offers, and that is 0.125%.

That means buyers might have to ‘pay up’ for this TIPS, because the current secondary market for a 10-year TIPS is about -0.166%.

Things can change in the next week, so it’s worth watching this site to see what the market is paying for the TIPS that matures 2021 Jul 15, which is the closest comparable you can get to a 10-year new issue.

But I will warn you that TIPS auctions, especially new issues, can be very hard to predict. I readily admit that I am no expert, and I’m often surprised at the auction result.

Read more about this Jan. 19 10-year TIPS auction

Posted in Investing in TIPS | 3 Comments

Next auction: 10-year TIPS on Jan. 19, 2012

The official announcement will come Jan. 12, but we know the Treasury will auction a new 10-year TIPS, CUSIP 912828SA9, on Thursday, Jan. 19. The question is: Should we consider buying this Treasury Inflation-Protected Security?

Normally, for me, a new 10-year TIPS would be an automatic purchase, because I’ve long considered the 1o-year to be the ‘sweet spot’ for building a buy-and-hold TIPS ladder. You get a better yield over inflation than with shorter-term issues, and the 10-year holding period is about right for people nearing retirement or newly retired.

This one ought to be doubly automatic for me, since I have a 10-year TIPS, CUSIP 9128277J5, maturing Jan. 15. It you also bought this one in January 2002, you know Jan. 15 is sort of a sad graduation day. This TIPS was issued with a coupon rate of 3.375% and it auctioned with a yield to maturity of 3.48%.

In other words, this 10-year gem has paid original buyers 3.48% every year on a principal balance that has risen 27.4% with inflation over the last 10 years.  That was a mighty good investment any way you look at it, especially in a dire 10 years of stock market returns.

OK, but what about CUSIP 912828SA9? The new 10-year TIPS to be auctioned Jan. 19 certainly doesn’t qualify for gem status. It might be more of a lump of coal, but that’s for you to decide.

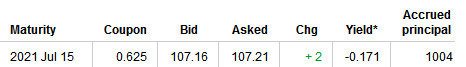
We don’t yet know the coupon rate, but it should be well below the 0.625% of the last new release of a 10-year TIPS, in July 2011. In the secondary market, that July TIPS is currently yielding -0.171%, as of Friday:

10 year TIPSAlthough you can’t make a direct comparison, it’s apparent that the new 10-year TIPS may auction with a negative yield, meaning that buyers will be accepting a rate of return less than the rate of inflation over the next 10 years. That has never happened in the 15-year history of 10-year TIPS auctions. Not only has it never happened, no yield has ever been close to negative for a 10-year TIPS new issue.

Here are all the 10-year new issues:

10 year TIPS historyThe 10-year TIPS auction of Jan. 19 will be interesting to watch. Will it make history with a first-ever negative yield for a 10-year TIPS? And is that still attractive to buyers?

Lump of coal? We are certainly entering uncharted waters for Treasury yields. Uncharted waters ought to make you uneasy. A negative real return over the next 10 years ought to make you uneasy. But there are no super-safe alternatives, and TIPS protect you against an unexpected rise in inflation. You can’t get that protection with a nominal 10-year Treasury (currently yielding 1.98%) or a bank CD (about 1.8% for the highest yielding 5-year CDs). That inflation protection is the key reason for buying TIPS.

One alternative, and that is … I Bonds. For my TIPS maturing Jan. 15, my first reinvestment will be in I Bonds, which also protect you against inflation, are super safe and can be used as a short-term investment. You can buy up to $10,000 per Social Security number in I Bonds at TreasuryDirect.gov.

(Thanks to commenter Jay for updating me on the new $10,000 limit for I Bonds, which was announced Jan. 4. That announcement is worth celebrating. Even if you hate Treasury Direct – which I don’t – you should consider I Bonds as an investment this year.)

The current I Bond interest rate – 3.06% – guarantees that you will receive a 1-year return of 1.53%, but probably higher, even if you sell after one year and pay a three-month interest rate penalty. If you sell after 5 years, there is no penalty.

The $20,000 limit per couple for I Bonds points them toward the small investor, but I still think they are the superior super-safe investment in January 2012, clearly superior to a 10-year TIPS paying a negative real return.

Posted in I Bond, Investing in TIPS | 6 Comments