Treasury Inflation-Protected Securities: 2011 in review

It’s certainly been an ‘interesting’ year for TIPS, with yields at somewhat attractive levels through the first half of the year and then plummeting to record lows in the second half. Here’s a look at the month-by-month auctions in 2011. Are there some lessons for investors here?

CUSIP 912828PP9

Jan. 20, 2011: A new 10-year TIPS issue is auctioned with a coupon rate of 1.125% and a yield to maturity of 1.170%. At the time, this looked like a mediocre yield, but still somewhat appealing. Today, it looks like a steal.

March 24, 2011: CUSIP 912828PP9 is reissued as a 9-year, 10-month TIPS and auctions at a yield to maturity of 0.920%.

May 19, 2011: It is again reissued as a 9-year, 8-month TIPS and auctions at a yield of 0.887%.

Looking back, all three of these auctions were winners for buyers.

CUSIP 912810QP6

Feb. 17, 2011: A new 30-year TIPS issue is auctioned with a coupon rate of 2.125% and a yield to maturity of 2.190%. This ends up being the most attractive issue of 2011.

June 23, 2011: CUSIP 912810QP6 is reissued as a 29-year, 8-month TIPS and auctions with a yield to maturity of 1.744%. Still very attractive, in our new low-rate world.

Oct. 20, 2011: This same TIPS is reissued with a 29-year, 4-month term and auctions at 0.999%. Not so attractive.

In seven months, the 30-year TIPS yield dropped from 2.19% to 0.999%. Amazing.

CUSIP 912828QD5

April 21, 2011: This new 5-year TIPS is auctioned with a coupon rate of 0.125% and a yield to maturity of -0.180%. At the time, this auction made headlines: BUYERS ACCEPT NEGATIVE INTEREST ON TIPS! Several financial columnists derided buyers as fools. I was a buyer, and I didn’t feel foolish.

August 18, 2011: CUSIP 912828QD5 is reissued as a 4-year, 9-month TIPS and auctions at a yield to maturity of -0.825%. That rate is seriously negative, and buyers seem to be signalling either 1) Armageddon or 2) high inflation is coming.

December 12, 2011: The last reissue of the year is a 4-year, 4-month TIPS that auctions at a yield of -0.877%. Again, seriously negative and very unattractive when compared with I Bonds for the small investor.

CUSIP 912828QV5

July 21, 2011: The last new issue of the year is a 10-year TIPS with a coupon rate of 0.625% and it auctions with a yield of 0.639%. Not so bad for buyers, especially since it looked like this issue might go off around 0.47% a few days earlier.

Sept. 22, 2011: CUSIP 912828QV5 is reissued as a 9-year, 10-month TIPS and it auctions with a yield of 0.078% — getting very close to a real yield of zero.

Nov. 17, 2011: It is again reissued as a 9-year, 8-month TIPS and auctions with a yield of 0.099%, still very close to zero but above the September auction.

Conclusions

If you were a TIPS trader – which I am not – those early-year purchases would have been profit machines. The lesson is that rates went down sharply in the second half of the year. Next year, could we see the reverse, with rates very low in the first half of the year and then rising in the second half?

It is possible. Keep that in mind.

As a buy-and-hold TIPS investor, and a net buyer of TIPS (buying more than mature each year) I would love to see higher rates. The current trend, though, is down and may stay down until the overall interest rates begin rising or the economy shows dramatic improvement.
Posted in Investing in TIPS | 2 Comments

Last pitch for buying I Bonds in 2011

The Treasury will auction a 5-year TIPS on Dec. 15, probably a reissue of CUSIP 912828QD5 that currently carries a yield-to-maturity of -0.980%. Yes, that is a negative, and it means buyers of this TIPS are willing to accept a rate of return nearly 1% lower than the rate of inflation for the next five years.

Why would they do that?

1) This TIPS is a super-safe investment, 2) world markets are still in turmoil and super-safe investments look attractive, 3) the Federal Reserve won’t budge on raising interest rates anytime soon, and 4) there aren’t many super-safe alternatives.

  • A 5-year nominal Treasury is paying 0.92%. That means the TIPS buyer needs inflation to run at 1.9% or more over the next 5 years to win over a nominal Treasury. Not a bad bet, plus the buyer gets protection from higher inflation.
  • The best 5-year CD is paying 1.84% (Ally Bank, as of Friday). That one actually competes pretty well with the 5-year TIPS, pushing the break-even inflation rate up to 2.82%. Before you buy that 5-year TIPS, look hard at this CD. But you would give up protection against higher-than-expected inflation.
  • On the other hand, the average 5-year bank CD is paying 1.17%, not very attractive versus the TIPS.

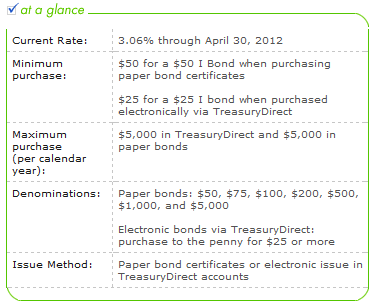
I Bonds, still the better investment. If you didn’t buy I Bonds before the Oct. 31 interest-rate change, go ahead, kick yourself. The six-month rate fell from 4.6% to 3.06% for the six months ending in April 2012. (Buyers get the current rate for six months after the purchase, so you could have guaranteed yourself a 2.3% 1-year return, or better.)

I Bond Nov. to April 2012Forget that 4.6% rate. If you haven’t bought I Bonds in 2011, you should still ponder this investment before Dec. 31. Here’s why: The Treasury puts yearly limits on I Bond purchases. You can buy $5,000 in Treasury Direct and $5,000 in paper bonds each year. A couple can buy twice that. Paper bonds will no longer be issued after Dec. 31, except as a tax refund.

So you could still load up on this I Bond in 2011 (paper and electronic) and then again in 2012 (just Treasury Direct purchases and your tax refund).

I Bonds currently carry a base interest rate of 0%, plus an inflation-matching interest rate that changes every six months. That makes them much more attractive than a 5-year TIPs with a return that is is 0.98% below the inflation rate. Zero is good. Negative 0.98 is bad.

The current I Bond interest rate – 3.06% – guarantees that you will receive a 1-year return of 1.53%, but probably higher, even if you sell after one year and pay a three-month interest rate penalty. If you sell after 5 years, there is no penalty.

While you could consider a 5-year CD if you can find an attractive rate, there really is no contest between this I Bond purchase and the 5-year TIPS reissue of Dec. 15. I Bonds are still the clear winner, even at a lower interest rate.

And if you have purchased I Bonds up to the limit in 2011, you can hold that investment for one month and buy them again in January 2012.

Posted in I Bond, Investing in TIPS, Savings Bond | 3 Comments

Thursday’s TIPS auction … a little strange

The Treasury on Thursday auctioned a reissue of a 10-year TIPS and it went off at a higher-than-expected yield of  0.099%, in addition to the inflation adjustment. This was nice news for the new buyers of this TIPS, since it had recently been trading in the secondary market with a negative real yield. On Wednesday, experts had predicted a yield of 0.06%.

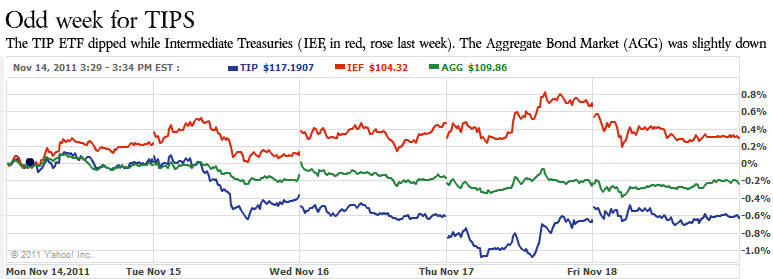
So the TIPS auction generated a higher yield, while at the same time, yields on nominal Treasuries were declining. This chart paints the picture:

5 week pattern for TIPIt’s remarkable that intermediate Treasuries were peaking around noon Thursday, the time of this week’s auction, and at that same time the TIP ETF was hitting its low, down about 1% for the week.

Like I said, this is good news for the buyers at Thursday’s auction. The yield of 0.099%, while paltry by historical standards, seemed pretty generous in today’s market.

Consider this: On Thursday, the rate on a nominal 10-year Treasury dipped to 1.96%, the lowest yield for any day this month. And that shows why a 10-year TIPS, paying a near-zero real return, is so much more attractive than a 10-year Treasury.

10-year Treasury: Worst it can do = 1.96%. Best it can do = 1.96%.

10-year TIPS: Worst it can do = 0%, assuming 10 years of deflation. Best it can do = unlimited, matching the inflation rate plus 0.099%

The TIPS buyer does better over 10 years if inflation averages more than 1.861%. I can’t predict the future, but I suspect inflation will be higher than 1.861% over the next 10 years, possibly much higher.

From a Bloomberg report on the auction:

“It wasn’t a great auction,” said Michael Pond, co-head of interest-rate strategy in New York at primary dealer Barclays Plc. “There has been a flight to liquidity into nominal Treasuries, and when that happens these auctions can go much worse.”

It’s good to be reminded that TIPS and Treasuries don’t always track together. When nominal Treasury yields decline because of fears of deflation, TIPS can take a hit.

Posted in Investing in TIPS | Leave a comment

10-year TIPS reissue auctions at 0.099%

The U.S. Treasury just posted the result of today’s auction of CUSIP 912828QV5, a 9-year, 8-month TIPS that auctioned at a yield to matury of 0.099%, close to but not quite the lowest rate in the history of 9- or 10-year TIPS auctions.

This TIPS has a coupon rate of 0.625%, so buyers paid a premium ($105.73 for each $100 of this issue).

The positive rate is a plus for TIPS buyers. Until very recently this TIPS was trading with a negative yield to maturity. The all-time low for a 9- or 10-year TIPS was for this same TIPS, 0.078% when it was reissued on Sept. 30.


Posted in Investing in TIPS | 1 Comment

Consumer Price Index falls 0.1% in October

Investors in Treasury Inflation-Protected Securities and I Bonds have been enjoying decent returns for the last year, thanks to higher-than-expected inflation.

But that trend turned in October, with the Consumer Price Index falling 0.1% because of lower prices on gas, cars and computers. The index for all items less food and energy (the ‘core inflation rate’) rose 0.1% in October, the same increase as in September.

This October number isn’t great news for holders of TIPS, who will see their principal balances fall slightly. But over the last 12 months, CPI has increased 3.5%, still providing a return that make TIPS attractive over nominal Treasuries.

It’s also interesting that the stock market is shaky today because the price of oil is rising above $100 a barrel. If this continues. it’s likely that the recent fall in gas prices would be reversed.

Update on Nov. 17 reissue of 10-year TIPS

The market rate of the Jul 2021 TIPS that will be reissued Thursday has risen into positive territory, and the overall TIPS market has weakened slightly today. That may mean the reissue will carry a positive yield (in addition to inflation adjustment to principal).

No 9- to 10-year TIPS has ever auctioned with a negative yield, and that trend might continue. We will learn the result at 1 p.m. Thursday.

Here’s my post from last week with more information on CUSIP 912828QV5.

Posted in Investing in TIPS | Leave a comment