
The U.S. Treasury will auction a reissue of a 30-year Treasury Inflation-Protected Security, CUSIP 912810QP6, on Oct. 20. Although the announcement was to come next week, it is already posted in the official list of upcoming auctions.
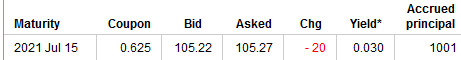
Reissues are always interesting, because this 30-year TIPS already trades on the open market, and you can get an idea – but only an idea – of the likely yield to maturity of this auction. Here is the current status (as of Friday) of this TIPS, which matures 2041 Feb 15:
 So at this point, it looks like buyers will be getting about 0.925% yield to maturity for the next 29 years. In addition, the principal of this TIPS continues to grow with the rate of inflation until it matures.
Is that a good rate? Well, sort of. If you look at the full maturity ladder of TIPS, you can see that the base rate to maturity is negative, all the way up to 2020 Jan 15, almost 10 years out. So buyers of any TIPS less than 10 years are willing to accept a return less than the rate of inflation. In that context, a payout of 0.9% above the rate of inflation looks pretty good.
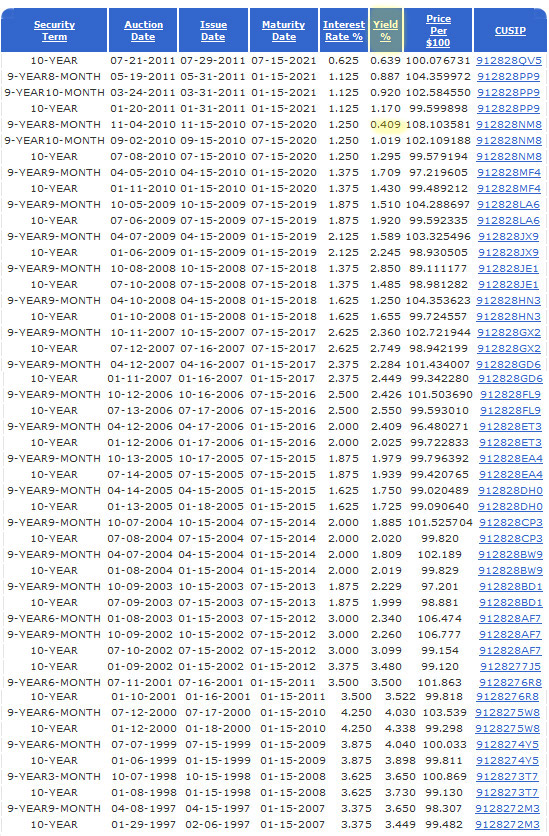
On the other hand … a rate of 0.9% would set a record low – in a massive way – for any 30-year TIPS ever auctioned. Here is a chart of all the previous auctions:
 As you can see, the current record low of 1.744% was set in the last reissue of CUSIP 912810QP6 (I was a buyer of that one, by the way, in June.) And this issue was first auctioned on Feb. 17, 2011 (this year!) at 2.190%.
I’m not a big fan of 30-year TIPS, because I am a buy-and-hold investor and I might not be around in 30 years. But I am a fan of 1.744% above inflation, and so I was a buyer in June on the first reissue.
This time, I will probably sit it out.
Reminder on I Bonds – act before Oct. 31.
One investment still stands out for the small investor: I Bonds. If you haven’t bought I Bonds this year, you can still buy $5,000 in Treasury Direct and $5,000 in paper bonds. A couple can buy twice that. (Paper bonds will no longer be issued after Dec. 31, except as a tax refund.)
- I Bonds currently pay a base rate of zero percent, plus a second rate based on inflation. The current inflation-adjusted rate is 4.6% for half a year, which guarantees that an investor will earn 2.3% (probably more) for the required 1-year holding period. (That 4.6% rate will change on Oct. 31, and probably fall a bit. If you buy before Oct. 31, you will get the 4.6% for six months.)
- I Bonds can be sold after one year with a three-month interest penalty, and after five years with no penalty.
- Interest payments on I Bonds are not taxed until the bond is redeemed, which can be 30 years from when they are purchased. That is a huge advantage over TIPS.
- Because of that tax advantage, I Bonds traditionally offer a base interest rate about 1% lower than a 10-year TIPS. But since I Bonds cannot go below a zero interest rate, the advantage shifts powerfully to I Bonds when TIPS are paying near zero.
- I Bonds are a much easier investment to keep track of. There are no yearly taxes due, and you can track your investments with the Savings Bond Wizard.


What has been published in other places is that once you notify TD, they will lock the deceased's account. Using…