Bond bubble? Jeremy Siegel takes a shot at TIPS

Jeremy Siegel, author of ‘Stocks for the Long Run’ and co-author Jeremy Schwartz took some punches at Treasury Inflation-Protected Securities today in an opinion piece in the Wall Street Journal. They contend that Treasuries – including TIPS -are in a price bubble with yields falling to historic lows.

They specifically call out TIPS for ridicule:

One market that now makes no sense to us is the popular Treasury Inflation Protected Securities (TIPS), where recent yields should be enshrined in Ripley’s “Believe It or Not!” The yield on the benchmark 10-year TIPS turned negative for the first time in history, meaning investors are now lending money to the government with the hope of receiving a sum 10 years from now that is worth less in purchasing power than the dollars they fork over today.

But it is worth pointing out that TIPS buyers – when faced with the option of 10-year Treasuries earning 2.1% – are actually showing logic in preferring TIPS, which have a principal base that grows with inflation. The yield to maturity (before inflation) for a 10-year TIPS is currently -0.002%, meaning that inflation would have to average just 2.102% over 10 years for the TIPS buyer to come out ahead over a 10-year Treasury. Not a bad bet at all.

Still, I personally would not be a buyer of 10-year TIPS at these rates, and I agree with the Jermys that there might be better yield plays out there, at this time of incredibly low Treasury rates. They suggest dividend-paying stocks, and I agree.

However, TIPS play a special role in many portfolios – the rock-solid safe ballast that is protected against inflation. Stocks play a different role in a portfolio, they are more risky and nothing is guaranteed. So it is hard for me to say sell TIPS and buy dividend-paying stocks. I wouldn’t do it.

The Jeremys say:

Some investors who avoid dividend-paying stocks point to the 2007-09 debacle, when the high-dividend financial stocks crashed. But a close look at the data indicates that was a unique event that we see having very little chance of repeating.

They are probably right. But they would have made the same statement before the 2008-09 debacle. Two extra-credit points:

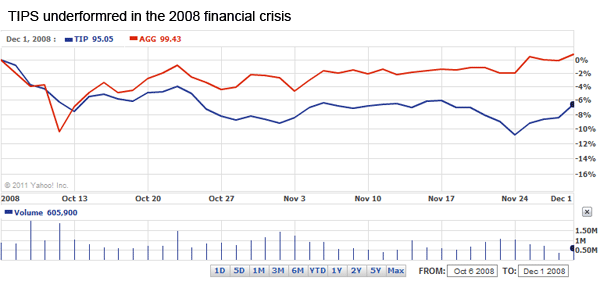
  • The authors could have noted that TIPS were also slapped hard during the 2008 financial crisis, losing almost 14% of their value from early October to late November. But they rebounded fairly quickly.
  • Jeremy Siegel is a senior adviser for WisdomTree,  a company that offers stock-based ETFs, and Jeremy Schwartz is is the director of research at WisdomTree. So their interest is in promoting stocks, obviously, but I don’t doubt their sincerity.

TIPS equal safety. If you holding a portfolio of TIPS to maturity, I say ignore the noise. Continue holding them.You should not be 100% invested in TIPS or any one asset. You should have an allocation in mind, say 25% to 50% in super-safe, boring investments like TIPS.

TIPS in a bubble? I have a hard time thinking ‘bubble’ for something so boring. But if you are holding a TIPS mutual fund, you probably do have downside risk of 10%, at least. Not quite like the tech blowup in 2000, but there is some risk from the recent surge in prices.
Posted in Investing in TIPS | Leave a comment

5-year TIPS auctions at negative 0.825%

The Treasury has posted the auction results for today’s reissue of a 5-year TIPS.

This yield to maturity of -0.825% was right in line with what most experts were predicting. The 4-year, 8-month issue will mature on April 15, 2016.

Four months ago, this same issue was auctioned at -0.18%, which demonstrates the dramatic fall in Treasury interest rates in the last four months. This is a record-low yield for a 4- or 5-year TIPS auction, well below the previous record of negative 0.555% in October 2010.

A negative yield to maturity does not mean TIPS buyers are accepting negative returns. TIPS have a fixed coupon rate (this issue pays 0.125% on the principal total) and the principal continues to rise to match the overall Consumer Price Index. The yield to maturity is set at the auction, and in this case that is -0.825%, meaning that TIPS buyers today had to pay more than $1 for each $1 they bought.

Since year-over-year inflation is running about 3.5% right now, buyers will be getting an overall return of about 2.65% right now, which is far better than the current rate on a 5-year Treasury, running at 0.90%.

So there is some logic in buying negative-yield TIPS, but mainly that is because 1) the inflation rate could be temporarily high and 2) the Treasury nominal rates are extraordinarily low, which also could be temporary.

So there is logic in skipping this TIPS, too. I skipped it.

‘Decent’ demand. That is the verdict from Cynthia Lin of Dow Jones, who writes:

The Treasury Department’s sale of 5-year Treasury Inflation-Protected Securities, or TIPs, offered a negative yield, but was still met with a record amount of direct bidders.

The group scooped up 17.1% of the $12 billion sale, compared to a average of 2.26% in the history of the auction. Indirect bidders, a pool of buyers that include foreign central banks, also bought an above-average portion of 47.2%. An overall measure of demand as seen in the bid-to-cover ratio came in at 2.49–on par with the average.

Posted in Investing in TIPS | Leave a comment

Stocks are plummeting: Interesting day for a TIPS auction

Update: This 5-year TIPS reissue auctioned at negative 0.825%.

Stocks looking punk. The Dow Jones Industrial Average is down 430+ points this morning, on the day that the Treasury is auctioning a reissue of a 5-year TIPS, CUSIP 912828QD5. That reissue was already likely to generate a record low for a 4- or 5-year TIPS. This TIPS, which matures in April 2016, was going for a yield to maturity of negative 0.856% yesterday. (The record low was negative 0.555% in October 2010.)

A decline in the stock market doesn’t necessarily mean lower TIPS yields, but in recent days of volatility, a lower stock stock market has triggered lower TIPS yields as investors move to safe havens.

Mixed news on inflation. Also out today is a bump in overall consumer inflation, but a dip in core inflation:

The Labor Department says the Consumer Price Index rose 0.5 percent in July, following a drop of 0.2 percent in June. Gas prices accounted for much of the swing. They increased by a seasonally adjusted 4.7 percent after dropping sharply in June. The core index, which excludes volatile food and energy, rose 0.2 percent. That’s below the 0.3 percent rise in each of the previous two months.

Thursday’s report showed that on an annual basis, consumer prices were up by 3.6% in July, above the Fed’s target. But stripping out energy and food, inflation was only 1.8% higher over a 12-month span.

Could this TIPS go for negative 1%? One thing I know: I can’t predict a TIPS auction. But I would guess against negative 1%. Let’s see how bad things get today.

Inflation Trader blogger Michael Ashton weighed in on the auction last night:

With the Fed pinning the 5-year nominal Treasury at 0.90% at the moment, consider that even with the real yield of the 5y TIPS bond at -0.85%, all you need to be indifferent is for inflation to average about 1.75% over the next 5 years. … You would be hard-pressed to underperform 5-year nominal Treasuries over the next five years.

The auction results will come at 1 p.m.

Posted in Investing in TIPS | Leave a comment

Coming Thursday, Aug. 18: Reissue of a 5-year Treasury Inflation-Protected Security

We knew this was coming, of course, and today we got the official announcement by the U.S. Treasury. On Thursday, the Treasury will auction a reissue of CUSIP 912828QD5, which was originally issued on April 15, 2011 and matures on April 15, 2016. It has a coupon rate of 0.125% but the real yield to maturity will be set at the auction, 1 p.m. Thursday.

Since it is a reissue, it’s easy to check on the current real yield for 912828QD5 in the open market. As of Friday, it had a real yield of negative 1.096%. Yes, that is a negative real yield, and yes, it is a full percentage point below the rate of inflation for the next five years.

Should you buy it? I always point out that I am a lowly journalist (some call that the lowest life form on Earth), and not a financial adviser. But I still have my opinion.

My opinion is NO, you should not buy it.

That’s based on Friday’s rate of negative 1.096%. Things could change before Thursday, and in fact I think they will change. I suspect this 5-year will end up auctioning at better  than negative 1%, but you never know.

(Update: Tuesday’s rate had risen to negative 0.861%, a bit of an improvement.)

Here are some of my thoughts:

Relive the glory days of April 2011. We can almost get nostalgic. I was a buyer of this 5-year TIPS when it was originally issued, and I did recommend it. I said at the time:

The regular five-year Treasury is paying 2.09%, also not a great deal, with no inflation protection. In fact, I think that rate is insanely low.

The best rate out there for a 5-year CD is from Aurora Bank at 2.43%. I would buy that CD before I bought a regular five-year Treasury. But this has no inflation protection.

The 5-year TIPS ended up auctioning at negative 0.18%, slightly better than I expected. ‘Buy it and forget it’ is my philosophy for TIPS, since I hold them to maturity. So, I did well on that one.

Zoom to four months later. Now the 5-year Treasury is yielding 0.99% and the best rate you can find on an insured 5-year CD, still Aurora Bank, is 2.31%.

Hey, wait a second, 2.31%?

These numbers spell out the problem:

Security                             April              Aug                  Difference

5-year TIPS                      -0.18%         -1.00%                -0.82%

5-year Treasury               2.09%            0.99%                 -1.10%

5-year CD                          2.43%            2.31%                 -0.12%

Back in April, the 5-year TIPS had the advantage over a 5-year CD because of its inflation protection. But now, you are betting on an average inflation rate of 3.31% over the next five years, just to break even with an insured CD. That could happen, sure, but does it seem likely during a time of very slow economic growth?

Negative 1% on a 5-year TIPS? Outrageous. I have been saving this chart for the perfect moment, so I guess its time has come:

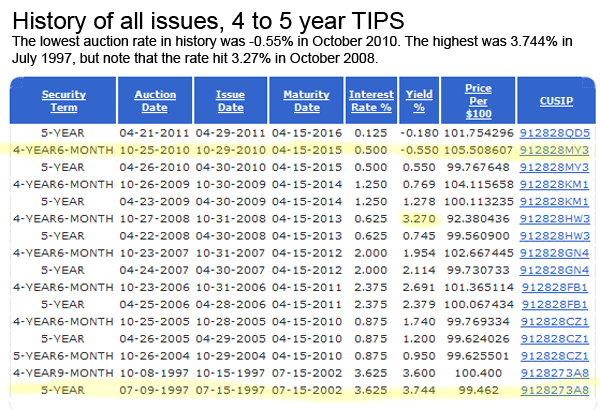
HIstory of 5-year TIPS issuesObviously, Thursday’s auction is going to set a record low for a 4- to 5-year TIPS, the only question is by how much. It could be nearly double the record low of negative 0.550% in October 2010. This chart also shows that the TIPS yield can swing sharply, rising from 0.745% in April 2008 to 3.270% in October 2008 at ground zero of the financial crisis.

Please, don’t forget I Bonds. If you haven’t bought U.S. Savings I Bonds this year, you need to do that first, before you buy a 5-year TIPS. This is a no-brainer, easiest decision you’ll ever make. Although I Bonds and TIPS differ, they both basically pay you the rate of inflation, with a federal guarantee and no state income taxes.

I Bonds issued right now will pay a base rate of zero percent, plus an inflation adjustment that changes every six months. (Right now, that adjusted rate is 4.6% for six months, but don’t get too caught up in that. It is the rate of inflation, minus nothing.) This 5-year TIPS will pay you the rate of inflation minus 1.0%. So this is simple. With an I Bond you get the rate of inflation. With this 5-year TIPS you will get the rate of inflation minus 1.0% (or so).

I Bonds also have huge tax advantages and can be sold after one year with a minimal penalty.

I Bonds are clearly superior.

You can buy $5,000 worth of I Bonds at TreasuryDirect.gov and $5,000 in paper I Bonds at your local bank. That is $10,000 per Social Security number. After Jan. 1, the paper option will be gone so you will have only half the buying power.

If you buy I Bonds before Oct. 31, you will get that 4.6% rate for six months, and then the rate will adjust, probably lower. So you should do this before Oct. 31.

Posted in I Bond, Inflation, Investing in TIPS | Leave a comment

Wall Street Journal: Good analysis of pluses, minuses of TIPS

Min Zeng wrote a good analysis last week on the rising asset values of Treasury Inflation-Protected Securities — at the same time inflation risk seems to be lessening. As Zeng points out, economic turmoil often leads to higher base yields on TIPS (and lower asset prices), because economic distress usually means lower inflation in the short term and also raises the specter of deflation.

Normally, when fears about the economy flare up, investors flee Treasury inflation-protected securities because their need to hedge inflation risk lessens. That was reflected in the selloff in TIPS that occurred in 2008, when the collapse of the Lehman Brothers Holdings Inc. fueled a deflation scare.

Yet prices of TIPS have surged in recent days, pushing down the 10-year benchmark TIPS yield below zero for the first time since the Department of the Treasury started selling this type of bond in 1997.

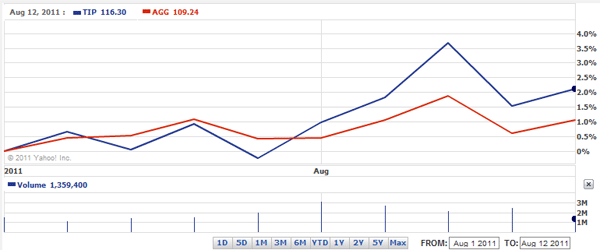
The price swings for TIPS have been rather amazing in the last 10 days, given that this is one of the world’s most ‘boring’ investments. For most investors, TIPS are the super-safe ballast in their portfolio. This chart shows that the TIP ETF (in blue) has been outperforming the AGG (aggregate bond market, red) since Aug. 1, and also shows that TIPS prices soared about 3.6% in about 8 days before coming back down a bit:

This is the opposite of what happened in the 2008 financial crisis, set off by Lehman Brothers’ collapse, as this chart shows:

The TIP ETF was down almost 10% during the fall of 2008, while the overall bond market stayed close to zero. When people ask me about the risks of TIPS mutual funds, I speculate: The downside risk is probably about 10% — bad, but not a portfolio crusher.

TIPS are at very lofty levels right now, with negative real yields climbing way up the maturity chart, to right about 10 years. Next week’s reissue of a 5-year TIPS could draw a real yield of as low as negative 0.9%. That is shocking because this same TIPS was first auctioned in April 2011 with a real yield of negative 0.18%. That is a huge swing in four months.

Zeng points to the underlying risk of inflation, even amid this turmoil.

Michael Pond, head of inflation bonds strategy at Barclays Capital Inc. in New York, the world’s biggest dealer on TIPS, said the U.S. consumer price index, stripping out of food and energy, has been running at an annualized rate of 2.5% over the past six months and 2.9% over the past three. Some analysts and economists predict they could tick up further in coming months. …

I think another factor is the Fed’s recent guarantee of ultra-low interest rates for the next two years. TIPS investors know they will have almost no super-safe, higher-yielding options in the next two years (except for I Bonds, which are limited to $10,000 per Social Security number this year, $5,000 next year.) As we face across-the-board low rates, TIPS at least have the advantage of inflation protection, a plus in these uncertain times.

One highly discussed factor is completely missing from this equation: The downgrade of U.S. debt by Standard & Poors. Treasury markets have soared since the downgrade, with the 5-year Treasury falling from 1.32% on Aug. 1 to 0.96% on Aug. 12.

Can a TIPS investment go wrong in this environment? Definitely. Zeng also adds this, quoting Mihir Worah of PIMCO:

TIPs may suffer a selloff should the debt-crisis deteriorate continues, feeding into fears about recession, he said, adding that deflation worries could re-emerge.

Posted in Investing in TIPS | Leave a comment