
Excellent timing on a question today from reader Slizzle:
With TIPS yields getting more and more negative, the rates on I-bonds are looking more and more superior every day (since they do not drop below zero). Is anyone else speculating that the government might change their I-bond policy because of this? I could speculate on some possibilities: 1) Paper bonds will not be offered in 2012; perhaps they won’t raise the $5,000 purchase cap on electronic bonds, 2) Perhaps they will allow the fixed rate to go negative like TIPS, 3) perhaps they will change the CPI to make inflation look smaller, and 4) perhaps they will phase out I-bonds altogether. I’m not one for conspiracy theories but it seems I-bonds yields are way above market at this point, and something has to give doesn’t it?
I have already purchased $10,000 of I-bonds for myself this year but I could still purchase another $10,000 in my spouse’s name. I was going to hold off until next year for the convenience of having them all in one TreasuryDirect account, but the huge drop in TIPS yields makes me wonder if it might be smart to buy these sooner rather than later. Thoughts?
I must mention that I am a lowly journalist and not a financial expert, and I don’t even play a financial adviser on TV. Given that, my response:
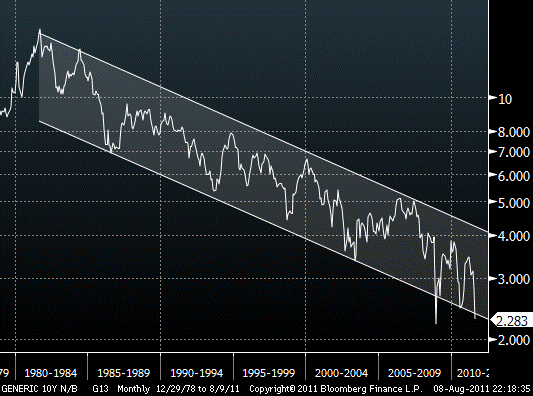
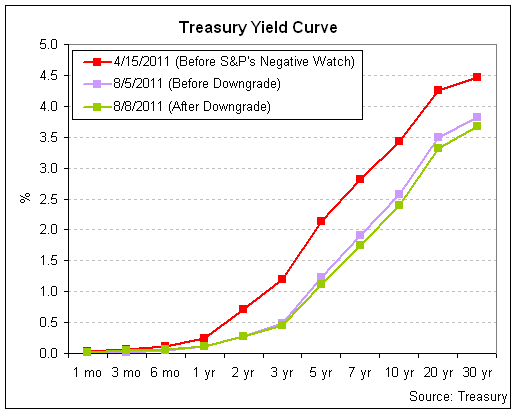
Slizzle, the government is way ahead of you, unfortunately. The Treasury announced earlier this year that it won’t issue paper I Bonds after Dec. 31, and there is no indication that it will budge the $5,000 electronic limit up an inch. So our buying power in I Bonds falls by half after Jan. 1. That news was rather nasty for savers, but you can understand why the government found this attractive: TIPS real yields are dropping into negative way up the yield curve.
And yes, at any time the Treasury could change the I Bond rules. Different CPI? Could be in the works. Eliminate I Bonds? Possibly. But drop the rate base below zero? That I doubt, since it might involve adjusting the amount you pay up front, like a TIPS transaction. Too complicated for a Savings Bond.
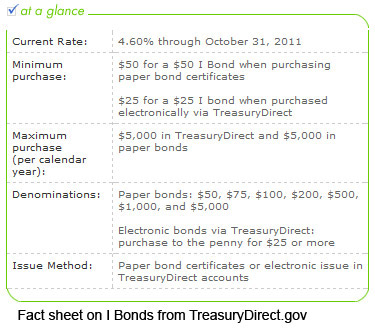 So, you get the BEST ADVICE OF THE MONTH: Buy those paper I Bonds right now. If you buy before Oct. 31, you will be guaranteed an interest rate of 4.6% for six months, and you will be required to hold the I Bond for a year.
After those six months, the inflation-adjusted rate could well be near zero (but not below zero), so you are guaranteed a return of 2.3% over the next year.
If you sell after a year, you would face a 3 month interest rate penalty, but 3×0 = 0. There would be no penalty or it will likely be minimal.
Buying I Bonds up to the limit, right now, is an absolute no-brainer. The best one-year bank CD on the market right now pays 1.19%. I Bonds will nearly double that, guaranteed.
If you wait after Oct. 31, your interest rate could well be zero for the first six months, and that means after Oct. 31, I Bonds will go back on the shelf as an interesting investment no one will buy. (The variable rate was 0.74% before the May 1 adjustment up to 4.6%.)
I Bonds are an unusually attractive option right now. This is easy advice for the super-safe part of your portfolio: Buy I Bonds to the limit before Oct. 31, when that 4.6% rate is going to drop dramatically, possibly to zero. If you buy before Oct. 31, you will get the full six months of 4.6%.
I am not saying you should sell after one year, though. I Bonds purchased now will give you that nice first year, and will match the inflation rate after that, more or less. A 5-year TIPS, which will be auctioned next week, could end up with a real yield of negative 0.6%, maybe much worse.
I Bonds are more attractive than TIPS for 1 year and 5 years, and their tax advantages make them more attractive than a low-yielding 10-year TIPS.
Can’t beat that.


Looked at the Seeking Alpha you mentioned about buying. Checked the Calamos web page. They have a chart that looks…