ITIP ETF: How risky is it?

I have been following the new iShares International Inflation ETF (ITIP) for a few weeks now, looking for a possible opportunity to buy in. I had arbitrarily set a price of $49.50, and it hasn’t hit that price yet. This would be a small investment.

I wrote about ITIP when it was introduced in late May, and I noted then that the fund was appealing because it invests in government inflation-linked bonds, excluding the U.S. So it would complement my holdings in U.S. Treasury Inflation-Protected Securities. (I don’t own any TIPS mutual funds or ETFs at the moment.)

I noted at the time two risks 1) among ITIP holdings are Italian, Greek and Turkish bonds, more risky than U.S. holdings, and 2) this is a lightly traded ETF.

How lightly traded? Here’s the rather amazing ITIP chart for last week, June 20-24:
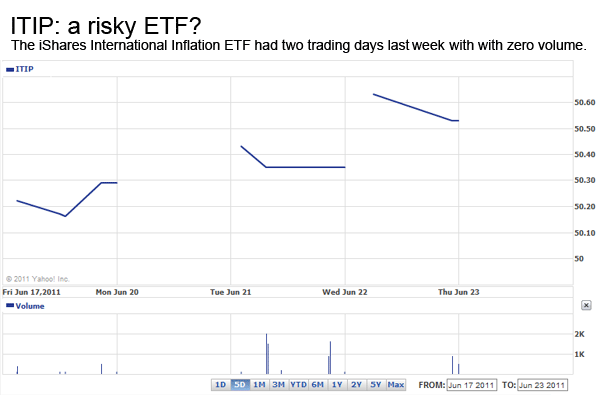
zero volumeSo in the midst of a screaming Greek debt crisis, this ETF, which includes Greek bonds, trades at zero volume? The Greek bonds, by the way, make up 2.78% of the funds holdings and are rated Caa1 / CCC.

Also, on Friday it was priced at $49.91 (it didn’t trade), 1.2% above its net asset value of $49.29. I think a better buying point will be below $49.

Here are the fund’s core holdings:

BRAZIL, FEDERATIVE R 7.15% — 5/15/2013 Baa2 /NR
FRANCE (GOVERNMENT) 5.78% — 7/25/2022 Aaa /NR
ITALY, REPUBLIC OF ( 5.67% — 9/15/2016 NR /NR
FRANCE (GOVERNMENT) 4.33% — 7/25/2016 Aaa /NR
UNITED KINGDOM OF GR 4.30% — 7/22/2030 Aaa /AAA
GERMANY (GOVERNMENT 3.92% — 4/15/2016 Aaa /AAA
AUSTRALIA, COMMONWEA 3.22% — 8/20/2020 Aaa /NR
TURKEY, REPUBLIC OF 3.11% — 10/1/2014 NR /NR
UNITED KINGDOM OF GR 3.08% — 3/22/2040 Aaa /AAA
CANADA (GOVERNMENT) 3.06% — 12/1/2026 TSY /TSY
Total 43.62%
Posted in International bonds, Investing in TIPS | Leave a comment

30-year TIPS auctions at just 1.744% … disappointing?

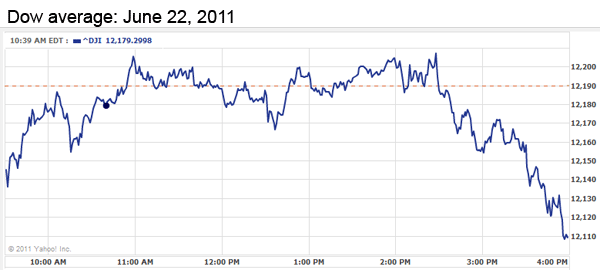
Fed Chairman Ben Bernanke saved the U.S. Treasury a lot of money with his speech on Wednesday, saying the economy remains weak and the Fed has no plan for a major stimulus program. The stock market took an immediate dive, and that continues today, with the Dow Jones Industrial Average down about 1.25% as of 1 p.m. today.

Against that woeful backdrop, the TIP ETF is up 0.5% today.

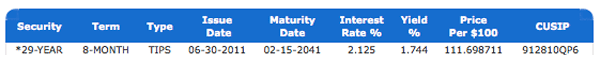
And so the Treasury’s reissue of a 30-year TIPS, Cusip 912810QP6, went off without a hitch — for the Treasury, that is. The resulting yield was 1.744%, solidly lower than the 1.85% that looked likely yesterday.

And yes, that is a record low for any 30-year TIPS auction. (A similar reissue last Aug. 23 generated a yield of  1.768%, the previous low.)

Didn’t see that coming …

From the Dow Jones report:

“This represents … the demand for long maturity TIPS, or rather the desire to get out of short maturity TIPS,” said Richard Gilhooly, director of interest rate strategy at TD Securities. “Short TIPS outperformed massively in recent months due to surging oil … now oil is plunging and the exodus from short TIPS is not yet over.”

And Dow Jones on the sharp drop in Treasury yields on Thursday:

Investors’ seemingly insatiable hunger for financial safe havens Thursday dragged two-year Treasury yields near an all-time low and briefly pushed yields on shorter-term bills into negative territory–suggesting buyers were even willing to pay the government to lend it money….

Near the end of the U.S. trading day, two-year yields touched 0.334%–the lowest level this year and close to the all-time low of 0.316%, booked on Nov. 4. …

Thursday afternoon, The Treasury Department sold $7 billion in re-opened 30-year Treasury Inflation Protected Securities at 1.744% amid the strongest demand, a bid-to-cover ratio of 3.02, in the history of 30-year TIPS sales.


Posted in Investing in TIPS | 2 Comments

Fed chairman Bernanke: Inflation is not ‘imminent’

Even though current inflation is running at 3.6% annually, it’s probably true that inflation is going to be held down near-term by a very weak U.S. economy. Here is the Reuters report on the ‘transient’ inflation issue:

http://www.reuters.com/resources_v2/flash/video_embed.swf?videoId=216213419

Slower economic growth. Quoting the Boston Globe:

The Fed said the economy was expanding less quickly than it had predicted. It now projects a growth rate of 2.7 percent to 2.9 percent in 2011, and 3.3 percent to 3.7 percent in 2012. Both estimates are markedly below its previous forecast in April.

End of quantitative easing. Even though recovery is slower than everyone wants, Bernanke did not announce any new Fed plans to boost the economy. No QE3 looks likely, quoting Dow Jones:

Federal Reserve Chairman Ben Bernanke Wednesday quashed speculation about another round of stimulative bond purchases, boosting the dollar. … The market took Bernanke’s comments as a sign of “deep reluctance to go down the road of QE3,” said Paresh Upadhyaya, director of G10 FX Strategy at Bank of America-Merrill Lynch in New York.

This is important for investors in TIPS, because the Fed purchases  have helped lower TIPS yields to historic lows.

Jobs picture won’t improve quickly. From ABC News:

Bernanke said it’s “very frustrating” that the U.S. is still some years away from full employment.  “At some point, if growth picks up as we anticipate, job numbers will start getting better. We’re still some years away from full employment in the sense of 5 1/2 percent, say.

U.S. inflation is not likely to get overheated without job growth and wage increases, which would also … trust me … result in an immediate rebound in the U.S. housing market. None of this is in our near-term future.

Stock market = not pleased. Stocks dropped sharply after the Federal Reserve cut its forecasts for U.S. economic growth this year and next, without hinting at further plans for stimulus.

TIPS market = slight indigestion. Normally, U.S. Treasuries perform well during times when the stock market is suffering and the economy looks weak. TIPS are a little more complex, though, because TIPS perform well when there is a higher fear of inflation.

Bernanke was doing his best today to shut down the fear of inflation.

The iShares TIP ETF was down 0.23% today. That isn’t significant. But if inflation fears really do subside, the TIP ETF could suffer.

Posted in Inflation, Investing in TIPS | Leave a comment

Making the call: Yes or no on 30-year TIPS reissue of June 23?

Even if you want to accumulate a portfolio of Treasury Inflation-Protected Securities, there is one big issue when it comes to this 30-year TIPS, Cusip 912810QP6:

Is 30 years too long?

My philosophy is simple: Buy TIPS at TreasuryDirect.gov (or in a retirement account) and hold them to maturity. In my view, putting 25% of your money into TIPS and I Bonds – not mutual funds, the real thing – is an ultra-safe, sensible investment. The rest of that portfolio can be diversified into dividend-paying stocks, stock mutual funds, other bonds, TIPS mutual funds, real estate, etc.

TIPS and I Bonds play two important roles: 1) They are the unshakable ballast of your portfolio. They will not go down. They will pay off at maturity. They will provide a real gain until then. And, 2) they are insurance against future inflation.

But 30 years?

PROS AND CONS OF THE 30-YEAR REISSUE

Pros

1) The auction yield should be around 1.8%, probably a bit higher. This is 110 basis points higher than the going rate on a 10-year TIPS, and a whopping 230 basis points higher than a 5-year TIPS. You will get that yield for 30 years, on a principal base that is constantly increasing with inflation.

The one good thing about 1.8% is that it will give your overall portfolio of TIPS a bit higher yield, balancing out some recent purchases, like the 5-year TIPS at negative 0.18%.

2) Inflation might not be a near-term threat, but it could be a threat – even a severe threat – in the next 30 years. This is a hedge against that threat. Can your bank CD promise the same?

3) Safety is high, when measured against other investments, at least.

Cons

1) That yield is not great. In fact, this TIPS was first issued four months ago with a base rate of 2.19%. It is likely that the TIPS rates will begin – eventually – moving more toward ‘normal’ levels, and for a 30-year that would be nearly 3%. However, I have been saying that for quite awhile, and I have been wrong.

This 30-year TIPS will be reissued again on Oct. 20, so you could park your money and wait it out, hoping for a higher yield in October.

There are two reasons that people buy 5-year TIPS at negative real yields: 1) They expect inflation to be higher than expected, and 2) It’s only five years.

This one is 30 years. You will be looking at it a long time in your portfolio.

On the other hand, if recent trends continue, we may someday look at 1.8% as an attractive rate. Unlikely.

2) Safety could reasonably become an issue in the next 30 years, as we are watching happen in Greece this week. The safety of U.S. Treasuries cannot be questioned, until you really start thinking about it. I don’t like going there.

3) 30 Years. It’s a long time.

CONCLUSION

Yes, I will invest in this TIPS, but I will reserve some funds for the upcoming 10-year and 30-year auctions of 2011. In other words, don’t bet the house on this one.

Posted in Investing in TIPS | Leave a comment

30-year TIPS auction: Lowest rate in history?

6/23 update: This 30-year TIPS was auctioned at a rate of 1.744%, which was indeed a record low for a 30-year issue.

—

The U.S. Treasury on June 23, 2011, will offer a 29-year, 8-month Treasury Inflation-Protected Security in a reopening of Cusip 912810QP6, which was first issued in February 2011. This same TIPS auctioned four months ago with a yield of 2.190%.

(The TIPS yield is a base number. In addition, for the life of the issue, your principal increases by the the rate of consumer inflation. So over time, both the principal and the interest you receive will increase, as long as the CPI rises.)

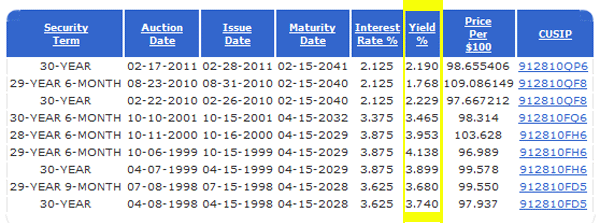
Right now, a week from the auction, it looks like this TIPS will auction off with a base yield of around 1.75%, (see updates below) which could end up being the lowest rate in history for a 30-year TIPS. (However, I need to point out that the Treasury stopped offering 30-year TIPS from Oct. 15, 2001 – when the base rate was 3.465% – until Feb. 15, 2010 – when the base rate had fallen to 2.229%.)

Pretty crafty work by the Treasury, to be locking up these much lower rates for 30 years.

I thought it would be interesting to look back at the rate of past 30-year TIPS auctions:

Go ahead, look longingly at those rates around 4% from 10 years ago. They are history. Will this June 23 auction bring a record-low base rate? Possibly not, since a similar reissue last Aug. 23 generated a yield of only 1.768%.

I ‘feel’ like this auction rate will end up being slightly higher. We will know more next week.

6/17 update: The market rate on this 30-year TIPS rose slightly on Thursday to 1.766%, still slightly below the lowest auction ever.

6/18 update: On Friday, the yield rose nicely to 1.815%. This issue is starting to look more attractive heading into next week’s auction.

6/21 update: On Monday, the yield rose again to 1.831%.

6/22 update: On Tuesday, the yield fell to 1.804%.

6/23 update: On Wednesday, the yield rose to 1.828%. My thinking is that should indicate an auction rate Thursday of 1.85% or higher, unless there is a shakeup in the markets.

If you are interested in buying this issue, check out the details on TreasuryDirect.gov. Noncompetitive bids will be accepted until noon, June 23.

Posted in Investing in TIPS | 2 Comments