Yield on 30-year TIPS? Ouch.

Note: I have posted updates on the 30-year TIPS’ likely yield

Next week, on June 23, the U.S. Treasury will auction a reissue of 30-year Treasury Inflation-Protected Securities. The formal announcement came today: It is a 29-year, 8-month issue, meaning it is Cusip 912810QP6, which was first issued in February 2011.

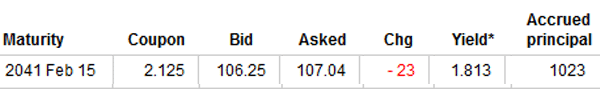
February 2011 … so long ago … you might not remember that this TIPS auctioned four months ago with a real yield of 2.130%. It has a coupon rate of 2.125%.

In only four months … The real yield on TIPS has declined sharply, mainly for this reason: A rising fear of inflation. When inflation fears rise, investors are willing to pay more for TIPS, and accept a lower real yield, because TIPS investors ‘benefit’ from higher-than-expected inflation. The other contributing factor is turmoil in Europe over the potential for a Greek default. That pushes investors toward the safety of U.S. Treasuries.

On Wednesday, we got a double whammy: The May CPI number came in higher than expected, and fears spiraled that Greece will default on its debt.

And this was the result at Wednesday’s end:

The likely yield on the 30-year TIPS to be issued June 23 declined sharply – now sitting around 1.757% – reversing a positive trend in yield that was making next week’s auction more appealing.

Here was the yield at the end of Tuesday:

So in one day, the yield dropped 0.056%. Like I said … ouch.

Keep in mind that four long months ago, you could have bought this 30-year TIPS with a real yield of 2.13%, with any future inflation building your principal over 30 years.

Makes you sort of nostalgic for the long-lost days of February.

At this point … I still would not rule out investing in this 30-year TIPS reissue, but I think it’s important to keep an eye on the potential yield. If it rises back toward 2%, this TIPS is a lot more attractive.
Posted in Investing in TIPS | 2 Comments

Provocative post: Is it time to short TIPS?

Personally, I am not going there. I don’t short, that’s not my style, and I definitely don’t feel I could accurately predict the future trend of TIPS mutual funds and ETFs, although I don’t own any at the moment and have repeatedly pointed out that mutual funds investing in TIPS are riding near 5-year highs.

So along comes The Inflation Trader blog on SeekingAlpha.com with a post titled, ‘Don’t count Bill Gross out just yet.’ (Not that I would ever count Bill Gross out. … Come on.)

Inflation Trader, I will just call him IT, points out that bonds had a big selloff on Tuesday, and that also affected TIPS, by the way. Since I am following the 30-year TIPS to be auctioned next week, I was interested in this development Tuesday:

That 30-year yield took a very nice leap upward on Tuesday, and anything getting it closer to 2% would make next week’s 30-year TIPS auction a lot more appealing. But the point is, Tuesday was not kind to Treasuries. (Wednesday was another matter, and I will write about that tomorrow.)

Back to IT, who writes:

Maybe bond guys just realize that if all of this bad news is in place, and not many folks are expecting a cheerful resolution from the Greek crisis, there are few reasons for Treasuries to rally further. … I also wonder if it is time to be short TIPS.

IT wrote this before Wednesday’s inflation numbers, which were a little worse than expected, so that counters (somewhat) the rest of his argument, which includes:

A small miss lower on CPI will not change the fact that the overall trend is upward, but it would serve to reduce the fear premium currently embedded in TIPS. A miss higher would keep that fear premium stable or even increase it a little bit, but that would probably be in the context of rapidly rising rates overall.

My point is that there is an anti-TIPS sentiment brewing, versus the overwhelming  pro-TIPS sentiment of the last several months. This is a lot more important for people who invest in TIPS mutual funds and ETFs. It is less important for people – like me – who invest in TIPS and hold them to maturity.

But what about that 30-year TIPS auction next week? Time to ponder.

Posted in Investing in TIPS | 1 Comment

U.S. inflation is heating up, right?

You might wonder based on conflicting news reports today (June 15),  when the U.S. released its monthly data on consumer prices.

From FT.com:

Core US consumer prices rose at their fastest rate for five years in May, making it almost impossible for the Federal Reserve to ponder further monetary easing.

But then there was this odd report from Associated Press:

Falling energy prices cooled overall inflation in May, offering some relief to consumers who have been coping for months with high gas prices.

But the AP story goes on to say:

Consumer prices rose 3.6 percent from June 2010 through May 2011, the biggest one-year gain since October 2008. The yearly gain in the index was only 1.1 percent as recently as November.

Reuters spun the story this way:

U.S. core consumer inflation rose more than expected in May to post its largest increase in nearly three years, lifted by steep rises in motor vehicle and apparel prices. … In the 12 months to May, consumer prices rose 3.6 percent, the biggest jump since October 2008, and well above expectations for a 3.4 percent increase.

What it means: May’s 3.6% annual rate, versus the expected 3.4% rate, was a bit of a shock to the stock market, contributing to a fall of 174 points, or nearly 1.5%, in the Dow Jones Industrial Average.

What it means for TIPS: When inflation expectations rise, TIPS mutual funds tend to do well. The TIP ETF was up 0.52% Wednesday.

Posted in Inflation, Investing in TIPS | 4 Comments

When will the 10-year TIPS yield rise to 2%?

The Financial Times Alphaville blog has an interesting post today speculating on the U.S economy and interest rates. The blog points out that Credit Suisse’s Andrew Garthwaite is over-weighting equities again, because Credit Suisse sees the stock market’s recent slump as a correction, not the beginning of a longer-term bear market. And it does not believe the U.S. economy is heading into recession.

At least for now.

The post gets  interesting when it points out Credit Suisse’s thinking on U.S. fiscal policy, and when the U.S. government will be forced to pare back its massive deficit.

So, the question becomes: when will the 10-year TIPS yield rise to 2% (for at that level, on our calculation, the fiscal tightening needed to stabilise government debt-to-GDP would rise to 7% of GDP, a level that would threaten the macro outlook and would also be politically hard to deliver forcing the US debt into a vicious circle of rising rates leading to a greater loss of fiscal credibility). Our answer is simple: it happens when either US banks are overweight government securities (when they have 20% of their assets in government securities, compared with 13% currently) or there is a sharp acceleration in private sector loan growth (forcing banks to lend to the private sector, not the government).

The point is … when the base yield rises to 2%, the federal government is going to have a difficult time paying ever-rising interest rates. “We think both events are unlikely to happen until late 2012,”  Credit Suisse says in the blog.

For longer-term investors in TIPS, a 2% base yield (or higher) was the norm for many years through the last decade. Right now that yield is about 0.72%, well below the norm.

Posted in Investing in TIPS | Leave a comment

TIPS mutual funds: Overrated as a ‘safe harbor’?

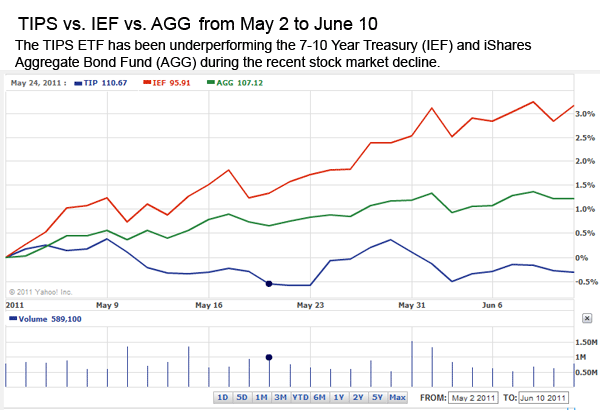
Most bond funds, and especially Treasury funds, are considered a safe harbor during a time of stock market decline. But mutual funds and ETFs that hold Treasury Inflation-Protected Securities don’t always follow that pattern. The market value of TIPS is also influenced by inflation expectations, which puts a complex spin on their pricing.

If the stock market is going down because of economic fears – as it has been over the last month – then TIPS may underperform other bond funds. The reason: The fear of inflation is dwindling.

This chart shows how the TIPS ETF has fallen behind other benchmark bond funds:

The real safe harbor? I contend that buying Treasury Inflation-Protected Securities directly through TreasuryDirect.gov, or through your broker in a retirement account, is a true safe harbor. This investment will produce a real return over inflation, and it is super safe.

TIPS mutual funds are a bit of a gamble. They have been an excellent investment over the last few years. But the market price of TIPS will go down if the base yield rises, and the base yield is at a historically low rate.

Posted in Investing in TIPS | 3 Comments