Next Treasury Inflation-Protected Securities auction: Reissue of 30-year TIPS on June 23

According to the Treasury’s tentative calendar, the U.S. government will auction a  30-year TIPS at 1 p.m. on June 23. The announcement will come June 16 and the auction will settle on June 30. It will be a reissue, so the term will be close to 30 years, but not quite.

30 years. Is this a good idea? My first reaction is: “I won’t be alive in 30 years, why would I buy this?” OK, I would be 88 in 2041, so maybe I might be alive, but that is an awfully long term. I advocate buying and holding TIPS to maturity at TreasuryDirect.gov, and I don’t consider TIPS a trading investment.

Another reason 30 years is troublesome is that TIPS are paying a historically low base rate right now, in addition to the inflation adjustment to principal. My reason for liking a 5-year TIPS at the moment, even with a slightly negative base yield, is that it lasts for only 5 years. After 5 years, I might be able to reinvest to get a better rate on a 10- or 30-year TIPS.

On the other hand …. You will get a much better yield with a 30-year TIPS than you will get with a 5- or 10-year right now.

Here are current yields on TIPS in the 30-year range:
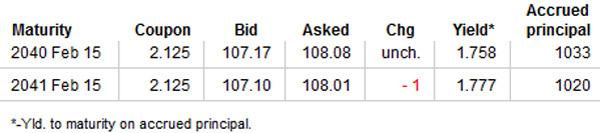
The 30-year TIPS coming June 23 is likely to pay a base yield of around 1.75%, along with the inflation adjustment to principal. That compares with negative 0.39% for a 5-year TIPS and 0.73% for a 10-year TIPS.

The last 30-year TIPS auction was closed Feb. 28, 2011, with a median yield of 2.19%.

A 30-year issue in February 2009, during the heart of the financial crisis, had a yield of 3.415%. (This was during a time when deflation was a much greater fear than inflation.) It was also a tremendous buying opportunity for TIPS and TIPS mutual funds. Imagine getting 3.4% above inflation on investment for the next 30 years.

So the trend has been a steady downward trend on TIPS yields, even for these ultra-long-term issues. That might continue, might not.

Finally, a story. In 1999 I invested a moderate amount in a 29-year, 6-month reissue TIPS, the only time I have bought a 30-year. I was uneasy about that long term. The yield was 4.069% above inflation — which was normal during the stock market bubble.

In the 12 years since I bought that TIPS, it has steadily paid 4%+ on ever-increasing principal. The accrued principal currently totals $1,359 for each $1,000 invested.

Wish I would have invested more.

Posted in Inflation, Investing in TIPS | 2 Comments

New ETF entries … International TIPS funds

IShares this month launched two new international bond funds with inflation protection: IShares Global Inflation-Linked Bond Fund (GTIP) and iShares International Inflation-Linked Bond Fund (ITIP). Both funds track indexes of government-issued bonds; the main difference is that GTIP includes U.S. Treasuries in the mix while ITIP excludes U.S. bonds.

The more intriguing investment is ITIP, since there are easy ways to buy and hold U.S. Treasury Inflation Protected Securities to maturity. Also, in my opinion, mutual funds and ETFs that track the U.S. TIPS market are near five-year highs and thus somewhat risky.

ITIP’s makeup looks like this (see all holdings):

Holding
% of Fund
Coupon Maturity Moody’s/S&P Rating
UNITED KINGDOM OF GR 9.90% 4.12 7/22/2030 Aaa /AAA
BRAZIL, FEDERATIVE R 6.94% 6.00 5/15/2013 Baa3 /NR
ITALY, REPUBLIC OF ( 5.82% 2.10 9/15/2016 NR /NR
FRANCE (GOVERNMENT) 5.77% 1.10 7/25/2022 Aaa /NR
GERMANY (GOVERNMENT 4.39% 1.50 4/15/2016 Aaa /AAA
FRANCE (GOVERNMENT) 4.32% 0.45 7/25/2016 Aaa /NR
AUSTRALIA, COMMONWEA 3.24% 4.00 8/20/2020 Aaa /NR
TURKEY, REPUBLIC OF 3.12% 3.73 10/1/2014 NR /NR
CANADA GOVT 3.07% 4.25 12/1/2026 TSY /TSY
UNITED KINGDOM OF GR 3.04% 2.50 7/26/2016 Aaa /AAA
Total 49.63%

Risk. This fund is definitely more risky than U.S Treasuries, with Italian, Greek and Turkish bonds in the mix. But the risk is lessened by the diversification.

Fees. The management fee for ITIP is 0.4%, which is double the fee of iShares TIPS ETF tracking the U.S. TIPS market.

Duration. The duration of ITIP is 8.51, versus 4.5 for the TIP, so there is more interest-rate risk. (About 68% of the holdings in TIP are 10 years or less, while for ITIP that number is 56%.)

Yield. Determining yield on a TIPS fund is impossible, since inflation will determine the future results. IShares says this for the ‘real yield,’ which ignores the inflation adjustment:

ITIP = Average Real Yield to Maturity 2.20%

TIP = Average Real Yield to Maturity 0.28%

Volume. If you are interesting in investing in ITIP, heed this warning: Place a limit order. The volume on this ETF is extremely light, since it just launched and has no track record. The average daily volume so far is only 1,650 shares a day. There are only 100,000 shares outstanding, versus 184,900,000 for the TIP ETF. That is a red flag for an ETF investor.

Price. In addition, ITIP was trading above its NAV last week ($50.16 versus $49.77), which can happen with a lightly-traded ETF.

Positives of ITIP = Better yield, diversification, international investment.

Negatives of ITIP = Riskier, light volume, foreign currency risk.

Conclusion. ITIP looks like an interesting ETF for diversifying your inflation-protected bond holdings. It has no track record, however, and is lightly traded. This is appropriate only for small investments.

Posted in Inflation, International bonds, Investing in TIPS | 1 Comment

10-year TIPS auctions at 0.887%

Thursday’s auction of 10-year Treasury Inflation Protected Securites was greeted with tepid demand — the resulting yield was 0.887 percent, higher than the rate that looked likely a week ago.

Inflation fears have diminished in the last few days, because the economy isn’t showing any signs of heating up.

The dated date of the 10-year TIPS is Jan. 15, 2011. The issue date is May 31, 2011. The TIPS mature Jan. 15, 2021.

The CUSIP number is 912828PP9.

Posted in Investing in TIPS | 2 Comments

S&P launches new index tracking TIPS

From the announcement press release:

The S&P/BGCantor U.S. Treasury Inflation Protected Security Index is a broad, comprehensive, market value-weighted index that seeks to measure the performance of the U.S. Treasury Inflation-Protected Securities (TIPS) market.

You can track the index here, but since it just launched on Tuesday, there is very little to see except for the current numbers.

Posted in Investing in TIPS | Leave a comment

Why I am exiting Fidelity Inflation Protect Bond (FINPX)

I bought into FINPX on Dec. 8, 2008, when the price per share was $10.25. I am selling today when the price is $12.16. This is a tax-free account. That is a capital gain of 18.6% over three years, above and beyond the regular interest distributions.

Honestly, I did expect some capital gain in this fund, because I was buying in the heart of the U.S. financial crisis. But in reality, the capital gain is the reason I am selling. My feeling is that TIPS yields are well below the historical norm, and eventually the trend will return to normal. This is the case with all Treasury issues, not just TIPS. This is the last TIPS mutual fund I own. I don’t own a TIPS ETF.

(As I have noted before, I do advocate buying and holding TIPS to maturity, either through TreasuryDirect.gov or in a tax-free retirement account. I am not dismissing TIPS as an investment, quite the contrary, I still a large portion of my portfolio in TIPS and I Bonds. But I feel TIPS mutual funds and ETFs are reaching a risky point.)

So, where did I reinvest this money? In another ‘boring’ investment, Fidelity Total Bond Market (FTBFX). The other fund I considered was Fidelity Intermediate Bond (FTHRX), which tracks very close to the Total Bond Market.

Here is a chart of the performance of these three funds over the last two years:

fidelity bond fundsAmazingly, all three funds have a very similar capital return (and a very nice return) over the last two years. But the FINPX TIPS fund shows much stronger swings, and is on a very strong upswing right now. That is why I am exiting.

TIPS on a roll

I prefer the boredom of the Total Bond Fund. Boring is good.

The TIPS fund is booming with the current surge in Treasury securities. I think that will pass. When it does pass, and TIPS yields return to a more historical level, I would be fine with returning to FINPX.

Posted in Investing in TIPS | 9 Comments