Treasury Inflation Protected Securities get trashed (again)

Brett Arends of MarketWatch.com wrote an ROI column this week sharply criticizing TIPS and the ‘suckers’ who buy them. Great headline: ‘Holding TIPS will make you poorer.’

Would you buy an investment that was absolutely guaranteed to lose money? No ifs, ands or buts: This sucker will make you poorer! How’s that sound? You might think this is a crazy question. You’re probably thinking, who would choose to own an investment that is guaranteed to lose money?

Arends argues that buying a 10-year TIPS with a base interest rate of less than 1% – or a 5-year with a base yield dipping into the negative – is ‘crazy, totally nuts.’ He also points out that the Consumer Price Index is a lousy way to measure inflation.

I agree with and understand his points.

My criticism: Arends doesn’t offer an investment alternative for the super-safe portion of your portfolio. And that is the problem.

Would you rather buy a 5-year CD at the local bank, now paying about 2.4%, or have a Treasury instrument (no state income taxes) that pays the rate of inflation minus 0.18% (the rate of the last 5-year auction)? At the least, it is a tossup, since the TIPS has inflation protection and the CD doesn’t.

Would you rather buy a conventional 5-year Treasury today, now paying an absurd 1.78%? That is an easy choice: I would go with the TIPS in this case. The inflation protection is a lot more valuable than getting 1.78% on your money, which is highly likely to produce a real return well below the -0.18% of the April 5-year TIPS.

(I contend that for a small investor, the U.S. I Bond is a better investment for your first $5,000 invested, since its base yield is locked at zero and it offers the same inflation protection. Zero is better than negative.)

The reason TIPS yields have gone negative is because the conventional Treasury yields have dipped to extreme lows, well below the likely rate of inflation over the next 5 years. So there is some logic to buying TIPS, to capture the rate of inflation (even at a slight penalty).

But I agree: Buying TIPS and holding them to maturity is not a ‘fabulous’ investment right now. It is OK. It is safe. It is a do-it-and-forget-it investment. (But I definitely would not dump a major portion of a portfolio into TIPS at the moment.)

And TIPS mutual funds are risky. Eventually the base rate on TIPS is going to climb back toward the historical yield of 2%, and TIPS mutual funds will get clobbered.
Posted in Investing in TIPS | 3 Comments

TIPS vs. I Bonds: Best move for small investor?

I Savings Bonds used to be a great investment, especially during the stock market bubble of the late 1990s, when they were paying 3.6% interest, plus the inflation rate. And back then, you could buy $60,000 of them a year and … use a credit card to buy them! (Great way to rack up frequent flier miles.)

I Bonds haven’t been so attractive in recent years, they rarely get mentioned anymore. I Bonds typically pay a base interest rate that is lower than a Treasury Inflation Protected Security. They both get the inflation adjustment to principal, so that typically makes a TIPS a more attractive investment. (With I Bonds, the inflation adjustment is added to the base interest rate, which changes every six months.)

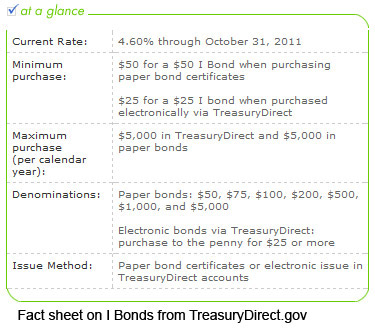
Nowadays, you can only buy $10,000 a year of I Bonds ($5,000 paper, $5,000 at Treasury Direct – per Social Security number – so a couple could buy $20,000 in one year). And of course that credit card deal was long ago phased out. Everyone’s conclusion: I Bonds just aren’t worth considering.

And that conclusion is wrong.

Here’s why: For a small investor looking for inflation protection over the next five years, I Bonds make sense for the first $10,000 (or $20,000 for a couple) that you are investing.

I Bonds currently have a base interest rate of 0.0%, plus the rate of inflation until you cash them out. The inflation ‘add-on’  interest rate is adjusted twice a year (May 1 and November 1). You need to hold them one year, and if you sell them before five years you face a three-month interest penalty.

Versus a 5-year TIPS? We just had a 5-year TIPS auction that went out at an effective interest rate of -0.18%, plus the inflation adjustment. So at this point, getting 0.0% with an I Bond is better than -0.18% for a TIPS, assuming you cash out after five years.

In addition, TIPS offer better protection against deflation, when compared to TIPS.

Current interest rate? Because of the odd way the Treasury adjusts the I Bond’s interest rate twice a year based on inflation, the I Bond is currently paying 4.60% through October 31, 2011. (That rate will likely fall dramatically in October when inflation balances out. We’ve had a short-term run of gas and food inflation.)

People seeing a rate of 4.6% might lured back into I Bonds. That rate is misleading, but the fact is I Bonds are a better investment (and have some tax advantages, too) than TIPS for  the first $5,000 you invest for the next five years.

Posted in I Bond, Inflation, Investing in TIPS, Savings Bond | 5 Comments

Next TIPS auction: 10-year on May 19, 2011

Although we don’t yet have full details, we know the Treasury will announce on Thursday, May 12, 2011, an auction of a 10-year Treasury Inflation-Protected Security. The auction date will be May 19 and the settlement date May 31.

The last comparable TIPS auction was a 9-year, 10-month reissue on March 31 that carried a coupon rate of 1.125% and a base yield set by the auction at 0.92%. (That is the yield the buyer receives until maturity, with the principal rising with inflation over the 10 years.)

The May 19 auction also is a reissue. The base yield is likely to be set by the auction around 0.68%, based on where rates were Tuesday, May 4.

My favorite quote from a Reuters story about the March 2011 auction:

“If there’s anything that’s unpredictable, it’s a TIPS auction,” said Tom Simons, money market economist at Jefferies & Co in New York.

Posted in Investing in TIPS | Leave a comment

Inflated yield on TIPS mutual funds?

Jason Zweig makes an excellent observations in his April 30 Intelligent Investor column in the Wall Street Journal: Don’t trust the yield quotes you see for some (not all) TIPS mutual funds.

Among the 173 TIPS mutual funds tracked by Morningstar, the reported “SEC yields” as of March 31 ranged from minus-0.77% to 5.58%, with 12 funds yielding at least 5%. Four of the seven exchange-traded funds that specialize in TIPS displayed yields greater than 5%, with Pimco 15+ Year U.S. TIPS Index leading the pack at 6.07%.

Yet no TIPS yield more than 1.75%. How could anyone but an alchemist generate 5% or more out of 1.75% or less?

The answer lies hidden in the term “SEC yield.”

In theory, since inflation can jump in a single month, as is did recently to 0.5%, you could annualize that rate to look like inflation is running at 6%, which it isn’t.

Take a look at the iShares TIP ETF, which can demonstrate the issue. On the fund’s data page, the 30-day SEC yield is listed as 5.59% — accurate but misleading. On the other hand, iShares also lists the Average Real Yield to maturity as 0.2% and the 12-month yield as 2.76%.

The data page for the Vanguard Inflation-Protected Securities Fund Investor Shares (VIPSX) intentionally underestimates its annualized yield, which is a ‘miserable’ -0.09%. But on Vanguard’s Website a box also pops up when you mouse over that rate:

The yield quoted is the real yield, or the yield before adjusting for inflation. The actual yield of Vanguard Inflation-Protected Securities Fund will be a combination of the real yield and an inflation adjustment. A complete estimate of the fund’s yield requires that an estimate of future inflation be added to the real yield. Because inflation fluctuates, it cannot be projected into the future precisely enough to be included in the yield quote. The inflation adjustment is based on changes to the Consumer Price Index (CPI) and can be either positive or negative, based on the change to the CPI. Investors interested in maintaining the purchasing power of their investment should invest their dividend distributions.

Vanguard is doing this right.

Posted in Investing in TIPS | 1 Comment

5-year TIPS auctions with base yield of negative 0.18%

The results are in for the 5-year Treasury Inflation-Protected Security auctioned April 21, 2011. The CUSIP is 912828QD5.

As expected, the 5-year TIPS carries a coupon rate of 0.125%. But because of high demand, bidders are paying $101.75 for $100 of this security. That results in a yield of negative 0.18%. (However, in addition to the base yield, investors in TIPS see their principal grow at the rate of inflation until maturity. This one matures April 15, 2016.)

That yield of -0.18% was a little better than I expected. Since I was a buyer of this TIPS, I wanted that negative yield as close to zero as possible. A few days ago it looked like -0.2% to -0.3% might be possible.

This works out well if …

Right now the regular 5-year Treasury is paying 2.13%. The 5-year TIPS auctioned today will do better than that if inflation averages more than 2.31% over the next five years.

So 2.31% is the breakeven rate. Since the TIPS offers protection against inflation, my opinion is that it is a better investment than the 5-year Treasury, or any five-year CD you can find out there. Not great, just a little better.

Posted in Investing in TIPS | 4 Comments