New 10-year TIPS auctions with a real yield of 0.725%, highest in nearly 5 years

The Treasury’s reporting tools were down at 1 p.m., but reader Ron came through with a link to the auction report. And now the tools are back up! Anyway …

A new 10-year Treasury Inflation-Protected Security – CUSIP 912828N71 – auctioned today with a real yield (after inflation) to maturity of 0.725%, the highest yield for any 9- to 10-year TIPS auction since May 2011.

The coupon rate was set at 0.625%, meaning investors are getting this TIPS at a discount, an adjusted price of about $98.95 for $100 of par value. Part of that adjustment was due to the fact that this TIPS will have an inflation index of 0.99905 on the Jan. 29 closing date. In other words, a buyer of $10,000 will have $9,905 on the settlement date.

Inflation breakeven rate. With a nominal 10-year Treasury trading right now at 2.03%, this TIPS gets an inflation breakeven rate of an ultra-low 1.30%. That means if inflation averages more than 1.3% over the next 10 years, this TIPS will outperform a nominal Treasury. That’s astounding, and indicates 1) the market is pricing in extremely low inflation over the long term, or 2) the market is adjusting to the idea of a near-term recession. Here are breakeven rates over the last six years:
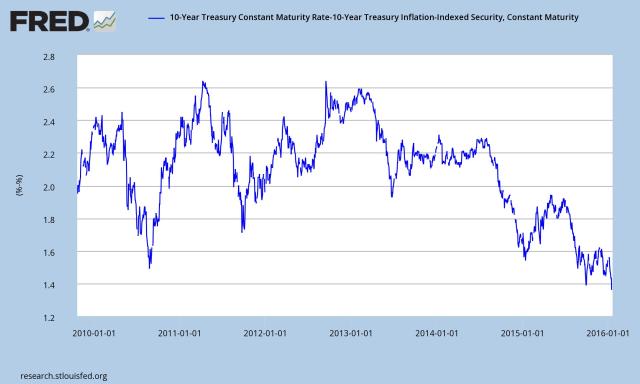
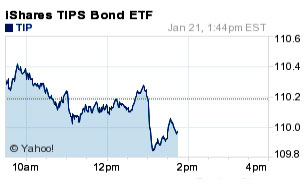
10-year inflation breakevenTIP ETFReaction to the auction. Today’s yield was much higher than I expected, by at least 8 basis points, based on market data from earlier Thursday. That thinking is backed up by the market’s reaction immediately after the auction: The TIP ETF fell sharply, indicating higher yields.

From the Reuters report:

U.S. Treasuries prices extended their earlier drop on Thursday after weak investor demand at a $15 billion auction of 10-year Treasury Inflation Protected Securities resulted in their highest yield since May 2011.

After watching TIPS auctions for 5 years, I can say ‘always be ready for surprises.’ Today I got a pleasant one.

Posted in Investing in TIPS | 3 Comments

A TIPS auction closes and the Treasury’s reporting system goes BOOM!

The Treasury closed its auction of a new 10-year Treasury Inflation-Protected Security at 1 p.m. today, but the reporting tools on the TreasuryDirect.gov site are completely down. There is no way to locate any auction announcements, past or present.

So far, no other news media have reported the results. (I am usually the first.) I’m looking and I’ll post what I find, when I find it.

Posted in Investing in TIPS | 2 Comments

Checking in on today’s 10-year TIPS auction

The Treasury will be creating CUSIP 912828N71 – a new 10-year Treasury Inflation-Protected Security – at an auction that closes at noon for non-competitive bids and 1 p.m. for competitive bids.

Here’s where we stand at 9:45 a.m. Thursday:

    • I am going to use yesterday’s Real Yields Curve estimate from the US Treasury as my baseline for this issue. It closed Wednesday at a real yield of 0.69% – exactly where it started the year. This is an estimate of the yield of a full-term 10-year TIPS.
    • However, Bloomberg’s Current Yields page – which gives real-time quotes – shows a 9-year, 6-month TIPS currently yielding 0.62%, which is pretty wide spread from the Treasury number.
    • The Wall Street Journal’s Closing Prices page shows that TIPS – which matures in July 2025 – closed yesterday with a yield of 0.643%.
    • The TIP ETF just opened higher at $110.32 and has since risen to $110.42 This indicates that TIPS yields are on the decline. Keep an eye on this number if you are investing in this TIPS.
    • The stock market has opened slightly lower – not a major move.

Tough call on where this yield will land. I’d guess at this point it will be below yesterday’s estimate of 0.69% and above the real-time yield of 0.62% on a shorter-term TIPS. Splitting the difference gives you a yield around 0.65% or 0.66%, which would be about where a 9-year, 8-month TIPS reopened at auction last November.

Hard to figure the demand on this issue. If the stock market decline is signalling a recession, that might mean lower interest rates and possible deflation in the future. Would a traditional Treasury be more attractive? But it is yielding only about 2.01% right now – 23 basis points lower than the beginning of the year. That is creating an ultra-low inflation breakeven rate of around 1.36% for this TIPS.

The market is betting on very low inflation over the next 10 years. I’d say this TIPS appears to be a screaming buy versus a traditional Treasury. However, if you believe extended deflation is looming, the traditional Treasury is the way to go.

At this point I think today’s auction is worth a small investment.

I’ll be posting results after the close at 1 p.m.


Posted in Investing in TIPS | Leave a comment

US inflation fell into deflation in December, down 0.1%; what does this mean for I Bonds and TIPS?

The Consumer Price Index for All Urban Consumers (CPI-U) declined 0.1% in December on a seasonally adjusted basis, the U.S. Bureau of Labor Statistics reported today. Over the last 12 months – the year 2015 – the all items index increased 0.7%.

Inflation over the last six months, ending in December, was 0.0%. The primary cause: Falling gasoline prices, which were down 4.0% in December and a whopping 19.7% for the year. Fuel oil costs were down an even stronger 7.8% in December and 31.4% for the year.

Those are amazing numbers, but it doesn’t stop there. In December food prices fell 0.1%, and are up just 0.8% for the year. New vehicle prices also fell 0.1% in December, along with apparel prices, down 0.2%. On the up side were shelter costs, up 0.2%, and medical care services, up 0.1%.

So even when you strip out food and energy and look at ‘core inflation,’ inflation rose only 0.1% in December. However, for the year 2015 it rose 2.1%, its highest 12-month change since the period ending July 2012.

Holders of TIPS and I Bonds are also interested in non-seasonally adjusted inflation, which is used to determine principal adjustments on TIPS and set future interest rates for I Bonds. In December, the inflation index was set at 236.525, down 0.34% from November.

What this means for TIPS. This was the inflation index’s fifth consecutive deflationary month, and will mean that principal balances on TIPS will fall another 0.34% through February. In July 2015, the inflation index stood at 238.654. In December, it was 236.525, down 0.89% for those five months.

There’s a TIPS auction on Thursday, and today’s inflation number does mean that the new issue will see falling principal through February. But that fact should be reflected in the auction price.

What this means for I Bonds. The next reset of the I Bond’s inflation-adjusted interest rate is coming May 1, based on inflation from September 2015 to March 2016. In the first three months of that period, inflation has declined 0.59%. If that trend continues, I Bonds will end up with a negative inflation-adjusted rate, which will will wipe out any smaller fixed rate and mean I Bonds will pay 0.0% for six months. This happened in 2015 and could happen again in 2016. But we have three months to go. I have updated my ‘Tracking Inflation and I Bonds‘ page with these new numbers.

decAdvice: Hold off on buying your allocation of I Bonds in 2016 until you see if I Bonds will be paying 0.0% for six months. If that is true, wait until the Nov. 1 reset.

More advice: Don’t let these numbers scare you into selling older I Bonds with fixed rates of 0.7% or higher. Those I Bonds – issued before May 1, 2009 – are a valuable asset. You should hold them to maturity or until you absolutely need the cash. If you decide to sell I Bonds, choose newer issues with fixed rates of 0.0%.

Here is the non-seasonally adjusted inflation trend for the year of 2015:

2015-inflation


Posted in I Bond, Inflation, Investing in TIPS | 2 Comments

Up next: A new 10-year TIPS will auction Jan. 21, 2016

This is CUSIP 912828N71 and you can read the Treasury announcement here. It’s a new 10-year Treasury Inflation-Protected Security, and that means the both the yield to maturity (after inflation) and the coupon rate will be set by the auction.

With the stock market in turmoil so far in January, the yield on this TIPS offering is likely to be volatile. TIPS usually benefit from a flight to safety during a stock market downdraft, but that hasn’t been happening so far in 2016. Over the last five trading days, the TIP ETF has slightly lost value, while intermediate Treasuries (IEI, shown in red on the graph below) has gained 0.76%.

TIP vs. IEIIt’s hard to predict if this trend will continue. Here is what we know at the close of markets on Friday, Jan. 15:

  • The best yield predictor for a new-issue TIPS is the Treasury’s Real Yield Curve Rates page, which estimates yields for full-term TIPS. At the close Friday, the Treasury estimated a 10-year TIPS would yield 0.67%, down just 2 basis points from where it opened the year.
  • Bloomberg’s Current Yields page shows real-time numbers for the longest-term 10-year TIPS currently trading on the secondary market. Right now its yield stands at 0.64% – but this TIPS matures in July 2025, six months earlier than next week’s new issue. So its yield should be slightly lower.
  • You can also look at the Wall Street Journal’s Closing Prices page and see that the TIPS maturing in July 2025 closed unchanged today with a yield of 0.628%.

So if the auction had been held today, this new 10-year TIPS probably would have yielded about 0.670%, generating a coupon rate of 0.625%. That would have been the highest yield – but just slightly – for any 9- to 10-year TIPS since July 2011.

I am especially interested in this auction because I have a TIPS – 912828ET3 – maturing Jan. 15. This was a sweetie, with a coupon rate of 2.0% and a yield of 2.025% after inflation. Inflation was a tame 19.7% over the last 10 years, but I still got about 4% annualized on that investment. (However, a nominal 10-year Treasury was yielding about 4.35% in January 2006, so it would have been the better investment.)

I have other TIPS maturing in April and July this year. At least interest rates appear to be heading higher, if haltingly. A big stock market decline could put an end to that, however.

Conclusion. I would be likely to buy this new TIPS if the yield appears to be climbing above 0.70%.

Here’s a chart of all 9- to 10-year TIPS auctions since January 2009, showing the wide variations in yield, from a high of 2.245% in January 2009 to a low of -0.750% in September 2012. It’s been an amazing seven years.

10-year TIPS auctions

Posted in Investing in TIPS | 10 Comments