And the Federal Reserve said: ‘No way’

The least surprising news of the week beeped on my telephone as I waited in line to check out at Costco Thursday afternoon. News alert: ‘Fed stands pat on interest rates.’

A better headline would have been: ‘Fed thumbs its nose again at savers.’ And so we will continue for a few months more, at least, of very-close-to-zero interest rates on our savings. Predictable, because the Fed clearly doesn’t have the courage to lift its ‘extraordinary measures’ that have continued nearly seven years.

Here was the USA Today headline on Dec. 17, 2008: ‘Fed cuts interest rates to near zero to combat economic recession‘. It’s an interesting story to look back on, because at the time it seemed to be a remarkable move. Here are some quotes:

The dramatic move sent stocks soaring as the Dow Jones industrial average surged 4.2% and broader indexes jumped more than 5% …

“The Federal Reserve will employ all available tools to promote the resumption of sustainable economic growth and to preserve price stability,” the Fed said. “In particular, the committee anticipates that weak economic conditions are likely to warrant exceptionally low levels of the federal funds rate for some time.”

The Dow rose 359.61 to 8,924.14 … “All in all, it’s good news for stocks,” said Jack Ablin, chief investment officer at Harris Private Bank. “It gave the market a little bit more than they expected.”

It worked, right? In the ensuing seven years, the stock market has doubled, the unemployment rate has dropped from 10.1% in October 2009 to 5.1% today. Economic growth – measured by GDP – has risen from -0.92%  in December 2008 to 3.91% as of March 2015.

All these things indicate a pretty ordinary – possibly even healthy – economy. And yet the extraordinary measures continue.

The one factor in the Fed’s favor is overall inflation, which has dropped to 0.2% over the last 12 months as gas prices have fallen dramatically. But when you strip out gas and food, inflation has been running at 1.8%, still mild but close to an acceptable target.

“Inflation is anticipated to remain near its recent low level in the near term but the Committee expects inflation to rise gradually toward 2 percent over the medium term,” the Fed said in its minutes released today.

And then the Fed placed thumb to nose and wagged: “To support continued progress toward maximum employment and price stability, the Committee today reaffirmed its view that the current 0 to 1/4 percent target range for the federal funds rate remains appropriate.”
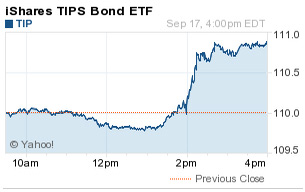
tip etfThe TIPS market reacted with glee, driving the TIP ETF up 0.78% for the day, closing at $110.87, one day after dipping below the magic $110 number. The Treasury’s estimate of the real yield for a 10-year TIPS dropped 10 basis points, from 0.73% on Wednesday to 0.63% today.

All of this comes on the eve of a delayed auction for the reopening of a 10-year TIPS. The Treasury is going to save a lot of money because of that one-day delay.

Sigh.

Posted in Investing in TIPS | 4 Comments

U.S. inflation drops back to deflation in August, down 0.1%

The Consumer Price Index for All Urban Consumers (CPI-U) decreased 0.1% in August on a seasonally adjusted basis, the U.S. Bureau of Labor Statistics reported today. Over the last 12 months, the all-items index rose 0.2%.

This wasn’t unexpected, although the consensus according to Barrons was a 0.0% number. Lower gasoline prices (down 4.1% in the month) and fuel oil (down 8.1%) were the cause of August’s decline. The overall energy index is down 15.1% over the last 12 months.

Other items showed price increases: Food was up 0.2% in the month; apparel, 0.3%; and medical care commodities, up 0.3%.

Core inflation, which strips out food and energy, increased 0.1% in August and is up 1.8% over the last 12 months. While core inflation remains mild, it is approaching the Federal Reserve’s target of 2.0% annual inflation.

Holders of TIPS and I Bonds are also interested in non-seasonally adjusted inflation, which is used to set future interest rates on I Bonds and to adjust the principal balance on TIPS. In August, the CPI-U inflation index was set at 238.316, down 0.14% for the month and up 2.0% over the last 12 months.

For holders of I Bonds, these numbers are significant. With one month remaining in the March to September adjustment period, inflation is up 0.93%, which would result in a new inflation-adjusted rate of 1.86% (annualized) on Nov. 1. That would be up from the current number of -1.60%. It’s possible we could also see the fixed rate rise above 0.0% on Nov. 1.

Keep  some cash available, just in case. To view the long-term trends, visit my Tracking Inflation and I Bonds page.

inflation

Posted in Investing in TIPS | Leave a comment

Next up: 10-year TIPS reopens at auction Sept. 18, 2015

Wisconsin

Wisconsin

I was vacationing in peaceful Wisconsin last week and the Treasury’s awfully early and rather strange auction announcement slipped right past me. These usually come around the 15th of the month, but not this time. No, the Treasury wants to pile a TIPS auction right after the Federal Reserve meeting this week – a meeting where the Fed could decide to raise short-term interest rates (very gently, I am sure, if at all).

Note the weirdness. The Fed decision will come Thursday afternoon. Normally, TIPS auctions close at 1 p.m. on Thursdays, but not this time. This auction will be Friday, Sept. 18, and will close at noon. Non-competitive bids must be placed by 11 a.m. Friday.

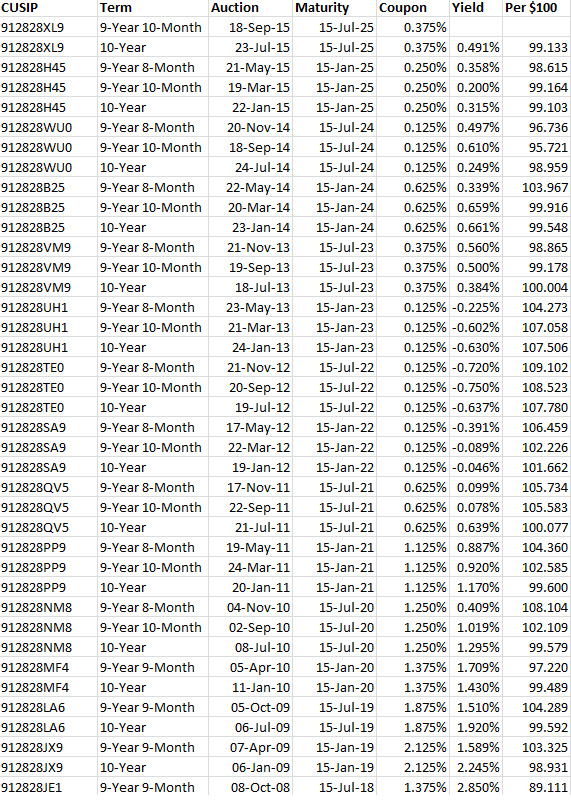
This is CUSIP 912828XL9, which originally auctioned on July 23 with a coupon rate of 0.375% and a real yield to maturity of 0.491%. Friday’s auction will create a 9-year, 10-month Treasury Inflation-Protected Security.

Friday’s auction is going to be very interesting. This TIPS is going to go off at a discount, but how much? Things are going to be volatile. We are going to get an August inflation report on Wednesday (the consensus is for 0.0%) and then a Fed decision Thursday.

Here is where things stand right now:

  • Because this TIPS trades on the secondary market, you can check real-time quotes at Bloomberg’s Current Yields page. At 5 p.m. Tuesday, Bloomberg is showing a real yield to maturity of 0.70% and a price of about $96.87 for $100 of par value.
  • The Wall Street Journal’s Closing Prices page shows that this TIPS closed Tuesday with a yield of 0.693% and a bid price of about $96.69 for $100 of value.
  • The Treasury’s Real Yields Curve page estimates a full-term 10-year TIPS would have closed Tuesday with a yield to maturity of 0.72%, very close to the Bloomberg number.

If this TIPS auctions with a real yield above 0.70%, it would be the first 9- to 10-year TIPS auction to close that high since May 2011. There have been 25 auctions since then!

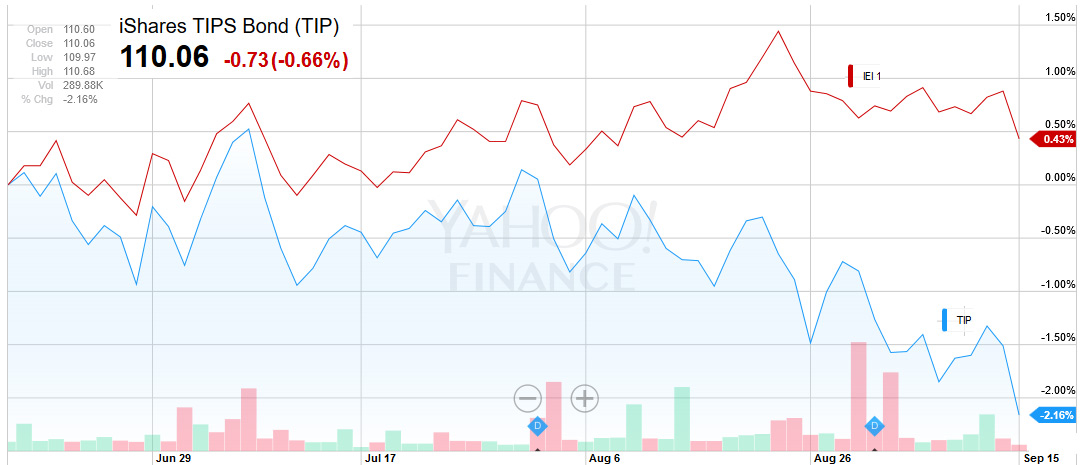
TIPS yields have been rising steadily in the last few weeks, and the TIP ETF has been feeling the pain (prices drop when yields rise). It closed today at $110.06, down 0.6% for the day and about 2.2% in the last 90 days. Demand for TIPS appears weak as we head toward Friday’s auction. You can see the trend in this three-month chart, which compares the TIP ETF in blue, versus the IEI (intermediate Treasury ETF) in red. TIPS have suffered while intermediate Treasurys have barely budged:

tip

TIPS versus nominal Treasurys. With a nominal 10-year Treasury closing today at
2.28% and a 10-year TIPS at 0.72%, you get an inflation breakeven rate of 1.56%, which I consider very attractive. In this chart, you can see breakeven rates hitting lows for the last five years:

breakeven

Conclusion. Amid all this chaos, a very attractive TIPS auction could be setting up for Friday. If yields hold above 0.7%, demand might return to the TIPS market. People who follow this blog know that I have said many times that the TIP ETF dropping to below $110 would mark a possible ‘buy’ for TIPS and TIPS mutual funds. We are getting very close.

Until then, study this chart of all 9- to 10-year TIPS auctions. I’ll be posting on Friday with a pre-auction update and then after noon, the auction results.

10year

Posted in Investing in TIPS | Leave a comment

A TIPS surprise: No bounce from market turmoil

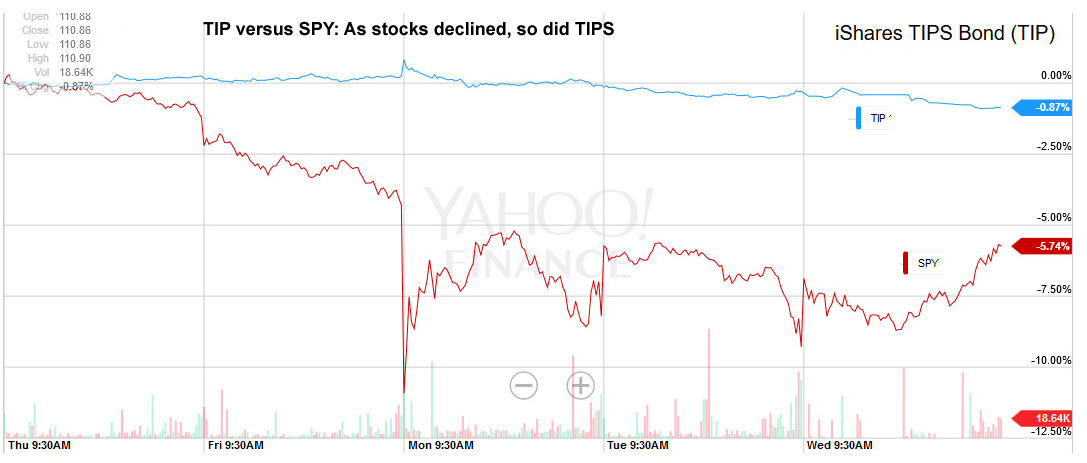
As stock markets wavered violently over the last week, the market for Treasury Inflation-Protected Securities has been remarkably sedate, and surprisingly, there is no apparent demand for TIPS as a ‘safe harbor.’

This chart shows the 5-day market results for TIPS, represented by the TIP ETF in blue, versus the overall stock market, represented by the SPY ETF in red:

TIP versus SPY

This is surprising because TIPS for years have been the safe harbor investment of choice: 1) for safety, and 2) for inflation protection against possible monetary moves to stimulate the markets.

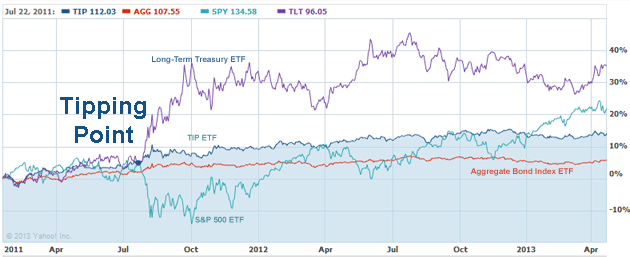
Remember the last correction? It had been more than four years since the stock market suffered a decline of more than 10%. In fact, the last stock market correction – which began in July 2011 – was the starting point for an explosion in the value of TIPS, pushing yields negative to inflation for years. I wrote about this in my April 25, 2103, article titled, ‘The TIPS earthquake: When did it happen, and why?’

That article included this chart, showing the huge move up for Treasurys and TIPS which began at the exact moment the stock market plummeted (oddly enough, in reaction to Standard & Poors downgrading US Treasurys):

Splitting point

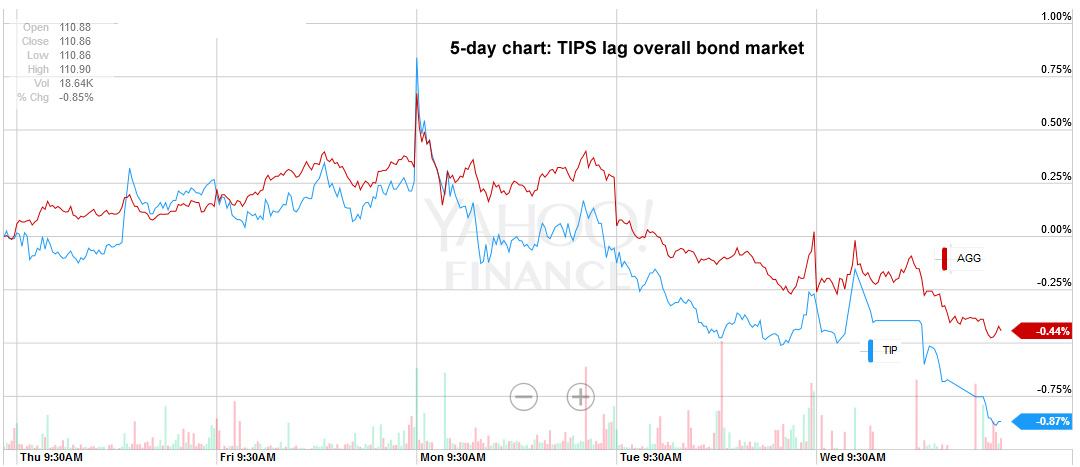
You can see in that chart that TIPS greatly outperformed the overall bond market for the remainder of 2011 (represented by the AGG ETF in red). But this time – the 2015 correction – that isn’t happening. As the stock market plummeted this week, TIPS values actually declined. And this chart shows that TIPS aren’t out-performing the overall bond market:

TIP versus AGG

A final thing to note: TIPS have also been lagging the overall Treasury market, meaning that inflation breakeven rates have been falling over the last week. That happens when TIPS yields rise more than Treasury yields. Here are the numbers:

5-year TIPS 5-year Treasury Breakeven
Aug. 19 0.33 1.50 1.17
Aug. 26 0.36 1.49 1.13
10-year TIPS 10-year Treasury Breakeven
Aug. 19 0.55 2.12 1.57
Aug. 26 0.65 2.18 1.53
30-year TIPS 30-year Treasury Breakeven
Aug. 19 1.06 2.81 1.75
Aug. 26 1.22 2.94 1.72

Conclusion. What can we take from this? 1) That the market does not fear inflation and does not expect the Federal Reserve to rush in with economic stimulus, 2) That the market is viewing the current stock market volatility as a correction and not the beginning of a major bear market, and 3) that the market still believes higher interest rates are coming, if not in 2015, then early in 2016.

TIPS are not going to be the ‘safe harbor’ investment in 2015. If yields continue to climb, we could see buying opportunities.

Posted in Investing in TIPS | 8 Comments

Auction result: 5-year TIPS reopens with a yield of 0.305%

The US Treasury just announced that its reopening of CUSIP 912828K33 resulted in a real yield to maturity (after inflation) of 0.305%. This creates a 4-year, 8-month Treasury Inflation-Protected Security.

Because this TIPS has an already-established coupon rate of 0.125%, investors today got it at a discount – an adjusted price of $99.17 per $100 of par value. However, because this TIPS carries about 1.9% of inflation appreciation since April, its adjusted price rises to $101.05 for about $101.90 of adjusted value.

The real yield of 0.305% was a huge jump – 64 basis points – over the April 23 original auction for this TIPS, which resulted in a yield of -0.335%. Today’s result was the second-highest yield in the last 14 4- to 5-year TIPS auctions, dating back to October 2010.

Short-term interest rates have been rising recently as the market adjusts to expected short-term rate increases from the Federal Reserve. It’s interesting to note that a 10-year TIPS is trading around 0.50% today, less than 20 basis points higher than a 5-year.

Inflation breakeven rate. With the nominal 5-year Treasury trading today at 1.47%, this sets up a ‘5-year’ inflation breakeven rate of 1.16%. That is remarkably low and indicates that the market expects continued very weak inflation. It also makes this TIPS very cheap against a nominal Treasury. Here is the trend for the 5-year breakeven over the last five years:

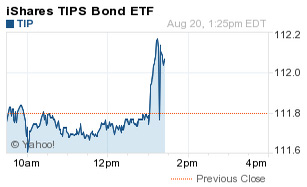
5-year breakevenreactionReaction to the auction. The TIP ETF had been trading down (slightly) all morning but took a very large move up after the auction closed, indicating declining yields. In fact, Bloomberg’s Current Yields page is showing this same TIPS currently trading at 0.27%, lower than the auction yield.

That’s a pretty strong statement in reaction to the auction, but what’s the message? Not sure, but I would say this auction was quite friendly to today’s buyers.

Reuters’ Richard Leong noted very strong demand for this 5-year TIPS reopening, which set a record high of 76.36% sales to indirect bidders, such as fund managers and foreign central banks.

TD Securities interest rate strategist Gennadiy Goldberg assigned an “A+” grade to the TIPS auction in a note, “suggesting that the recent selloff managed to attract some end-user demand.”

Posted in Investing in TIPS | Leave a comment