U.S. inflation rose a mild 0.1% in February

U.S. inflation increased 0.1% on a seasonally adjusted basis in February, the Bureau of Labor Statistics reported today, continuing a trend of very mild inflation for more than a year. Over the last 12 months, the Consumer Price Index for All Urban Consumers – (CPI-U), also called ‘headline inflation’ – increased just 1.1%.

An increase in the food index accounted for more than half of the increase in February. The food index rose 0.4% in February, but the overall energy index dropped 0.5%, with gasoline prices falling 1.7% in the month and 8.1% over the last 12 months. Apparel prices also fell 0.3% in the month.

Holders of Treasury Inflation-Protected Securities and I Bonds are also interested in the non-seasonally adjusted CPI-U, which is used to set the inflation adjustment to principal of TIPS and establish the future inflation-adjusted interest rate for U.S. Savings I Bonds.

In February, non-seasonally adjusted inflation rose 0.4%, but the 12-month rise was the same 1.1%. At the end of February the CPI-U index stood at 234.781, a 0.2% increase over where it stood at the end of September. One more month remains to determine the new six-month inflation-adjusted interest rate for I Bonds.

At this point the I Bond inflation rate will be set to an annualized rate of 0.4%, down substantially from the current six-month rate of 1.38%. At least it may not drop to 0.0%, which seemed possible last month.

Core inflation – which strips out more-volative food and energy – also increased 0.1% in February and 1.6% over the last 12 months.

Inflation continues to run well below the Federal Reserve’s goal of 2.0% a year and ‘danger’ level of 2.5%. But the Fed doesn’t seem concerned that its tapering of bond-buying stimulus could slow prices even further. Some of February’s softness could be weather-related; not much the Fed can do about that.

Posted in I Bond, Inflation, Investing in TIPS | 3 Comments

Up next: 10-year TIPS reopening will auction March 20, 2014

Later today, the U.S. Treasury will formally announce it will reopen CUSIP 912828B25, a 10-year Treasury Inflation-Protected Security, in an auction on Thursday, March 20. This TIPS originally auctioned Jan. 23, 2014, with  a coupon rate of 0.625% and a yield to maturity of 0.661%, plus inflation.

Update: Here’s the announcement.

So, what can we expect from this 9-year, 10-month TIPS?  If the auction were today, the yield to maturity might be around 0.55%, a drop of 7 basis points since the January auction. That means buyers would have to pay up a little to snag this TIPS, around $100.30 for  $100 of value.

But a lot can happen in a week. Here are some data sources to check before the auction:

  • The Treasury’s Daily Real Yield Curve Rates, which right now are indicating a yield of 0.54% for a 10-year TIPS.
  • Bloomberg’s Current Yields, which reflects current trading but can be a little misleading. At this moment, it shows CUSIP 912828B25 trading at 0.55%.
  • The Wall Street Journal’s closing price list for TIPS, which shows that the TIPS maturing 2024 Jan 15 closed Wednesday at 0.523%.
  • I’d also recommend using the Treasury’s Yield Curve site to track the yield of the nominal 10-year Treasury, which is currently at 2.73%. The TIPS yield is likely to rise and fall with that number over the next week.

If next Thursday’s auction yield fails to exceed 0.661%, it will break a string of eight consecutive 9- or 10-year TIPS auctions that have resulted in a higher yield. Here is a history of 10-year TIPS auctions going back to 2009:

10 year TIPS

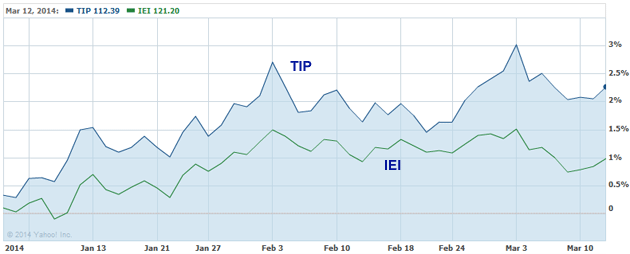
Although bond yields were expected to rise in 2014, the opposite has happened, thanks to some shakiness in the stock market and worries over Russia’s incursion into Crimea. All Treasurys, including TIPS, benefit with the ‘flight to safety’ that inevitably follows stock-market hiccups. The TIP ETF is up almost 2% since Jan. 1, even as inflation remains tame.

It’s also significant that TIPS have been out-performing Treasuries of similar terms. Take a look at this year-to-date chart for the TIP ETF versus IEI, an ETF holding intermediate-term Treasuries and having a similar duration:

compareWhen you see this happen, it means the inflation breakeven rate is climbing, and TIPS are getting more expensive versus traditional Treasuries.

If next Thursday’s auction goes off at 0.55%, it would create an inflation breakeven rate of 2.18%, versus 2.12% when the TIPS first auctioned in January. Still on the relatively cheap side, but keep an eye on the 10-year Treasury over the next week.

Posted in Investing in TIPS | 7 Comments

A troubling report on family net worth from the Federal Reserve

money bags

Look who’s happy.

The Wall Street Journal headline today seems like great news: ‘U.S. Household Net Worth Hits Record High.‘ It is good news for those sharing in the prosperity. But the article’s sub-headline sheds light on the complexity: ‘Surging Stock Market and Rising Home Values Deliver Benefits, Especially for Affluent.‘

The Federal Reserve issued a report Thursday noting that the net worth of U.S. households  rose 14% last year, to $80.7 trillion, the highest on record. Even adjusted for inflation, U.S. household net worth – the value of homes, stocks and other assets minus debts and other liabilities – hit a record.

Great news, right? Here’s the dark side, from the Journal report:

But the rebound, while powerful, has been tilted in a way that limits the upside for the broader U.S. economy and is increasingly leaving behind many middle- and lower-income Americans.

“Wealth inequality…has increased over time,” said William Emmons, an economist at the Federal Reserve Bank of St. Louis. “So, there seems to be a disconnect: There are big wealth gains, but not much follow-through on consumer spending.” …

Younger families in particular continue to lag behind in the wealth recovery. The average young family—led by someone under 40—has recovered only about a third of the wealth it lost during the crisis and recession ….  By contrast, the average wealth of middle-aged and older families has recovered to roughly precrisis levels.

I write a blog about Treasury Inflation-Protected Securities and I Bonds, two investments that focus on capital preservation, and therefore are targeted at upper middle-class and wealthy investors. You won’t get rich investing in TIPS and I Bonds, but a lot of rich people invest in them. Why? Because they are already rich.

I won’t admit to being rich (nobody does, right?) but I do know that what wealth I have came because I had the good fortune to be born in 1953, at a time of great economic expansion in the United States. I was able to finish college without debt. I was able to get a good job, right away. My wife and I were able to save money during the greatest bull market in U.S. history.  We were able to buy an affordable house and watch its value climb. We were able to accumulate enough assets to be more conservatively invested during the dual market crashes of the 2000s.

Yes, we saved diligently, but mostly … we were lucky.

Young families – people younger than 40 – face a much different picture today.  Many are burdened with heavy college debt. Many have had trouble finding jobs matching their skills. Their jobs no longer offer pensions, and their pay raises barely match inflation. They pay more for health care. Their investments have been hit by at least one major market crash, maybe two.

These families don’t have large stock market assets – how could they? – and many don’t own homes. So their net worth is not rising along with older Americans’. They can’t join the party.

The Federal Reserve of St. Louis took a look at these numbers and wrote a report titled,  ‘Housing Crash Continues to Overshadow Young Families’ Balance Sheets.‘  It includes this chart showing how younger families are not gaining ground:

Net WorthThe Federal Reserve study noted:

The main reason young families’ balance-sheet recovery lags is the recent housing crash and its lingering effects. The homeownership rate among younger families has plunged. … The house-price gains that have helped mainly older families to rebuild homeowners’ equity have been overshadowed among younger families by the ongoing retreat from homeownership.

This ‘two Americas’ theme isn’t new, but it is interesting to see it framed as young vs. old. As these young families age, will they be able to accumulate assets to build significant net worth?

I worry about that.

Posted in Investing in TIPS | 11 Comments

What would ‘normal’ TIPS yields look like?

You might ask: ‘How are you going to define ‘normal’? Good point. In the financial world, the going price for anything might be called the ‘normal’ price, set by free markets. But in the case of Treasury Inflation-Protected Securities, normal is very hard to define.

So, for today only, I am going to define ‘normal’ to mean ‘acceptable.’ In other words, attractive to buyers, a sensible investment, and in line with historical trends. Today, with a 10-year TIPS yielding about 0.52% above inflation, I don’t think we are there yet.

I have tried in the past to project a ‘sensible’ yield for a 10-year TIPS, and I came up with a yield of about 1.76%, plus inflation. We won’t be seeing that anytime soon, but read my analysis to see why TIPS yields will eventually return to that level, and probably higher.

So for today, I decided to declare the first auctions of 2011 – for 5-, 10-, and 30-year TIPS, to be about as ‘normal’ as we can expect to see in the next two years.

Why early 2011? The TIPS and Treasury markets dramatically changed in mid-2011, a fact I detailed in this post: The TIPS earthquake: When did it happen, and why? It’s strange, but the factor that triggered this upheaval was the crushing failure of Congress to address runaway government spending and spiraling deficits. Eventually, Standard & Poors downgraded U.S. debt – and the result was that U.S. debt skyrocketed in value. As weird as that seems, that’s the way it happened.

(True, it wasn’t the S&P downgrade of U.S debt that directly resulted in soaring Treasurys. But the fiscal crisis and resulting downgrade caused the stock market to plummet and suddenly the U.S. economy looked extremely dire. The Federal Reserve responded with an aggressive bond-buying stimulus program. That raised fears of inflation and that directly caused TIPS to soar, along with the stock market.)

I started this blog in April 2011 and at the time TIPS were as boring and conservative an investment as exists on Earth. Within a few weeks, I read a commentary that said: “The only reason to buy TIPS is for the capital gain.” I was horrified! No, TIPS are conservative! Not for trading! But the commentator was totally correct. TIPS were about to launch into massively lower yields and higher prices.

So let’s look back to the first auctions of 2011, before this turmoil began, in search of something ‘normal.’

  • Jan. 20, 2011. A new 10-year TIPS, CUSIP 912828PP9, auctioned with a yield to maturity of 1.17% and a coupon rate of 1.125%. Since that date, no 9-to 10-year TIPS auction has generated a yield above 1%. The highest yield since then was 0.92% for the reopening of this same TIPS on March 24, 2011.
  • Feb. 17, 2011. A new 30-year TIPS, CUSIP 912810QP6, auctioned with a yield to maturity of 2.19% and a coupon rate of 2.125%. The highest yield since that date for any 29- to 30-year TIPS was 1.42% in June 2013 for a reopening of CUSIP 912810RA8.
  • April 21, 2011. A new 5-year TIPS, CUSIP 912828QD5, auctioned with a yield to maturity of -0.18% and a coupon rate of 0.125%. At the time, this auction made headlines: BUYERS ACCEPT NEGATIVE INTEREST ON TIPS! Several financial columnists derided buyers as fools. I was a buyer, and I didn’t feel foolish. Since that date, the best yield on any 4- to 5-year TIPS auction was -0.13% for a reopening of CUSIP 912828UX6 on Aug. 22, 2013, another auction where I was a buyer.

To recap, this is about as normal as we can expect in 2014 and possibly well into 2015:

  • 5-year TIPS at -0.18%, plus inflation. The current yield is -0.25%
  • 10-year TIPS at 1.17%, plus inflation. The current yield is 0.52%
  • 30-year TIPS at 2.19%, plus inflation. The current yield is 1.35%

We have a long way to go, except for the short-term TIPS. If you think a move that large isn’t possible, I will close with this chart of all TIPS auctions in that momentous year of 2011. Study it:

2011 TIPS

Posted in Investing in TIPS | 3 Comments

Savings Bond holders: Your I Bond interest rate could drop to 0.0% on May 1

I Bonds

We are supposed to be in a year of rising interest rates, but so far that hasn’t been true. And holders of I Savings Bonds could be in for a bit of of a ‘shock’ on May 1, when the inflation-adjusted interest rate is re-set for all I Bonds.

With two months left to go, inflation data are pointing to a negative number for the inflation-adjusted interest rate on I Bonds. That could change once the February and March data are in, of course, but right right now we are looking at a -0.1% inflation-adjusted rate.

I Bonds pay a combination of two interest rates:

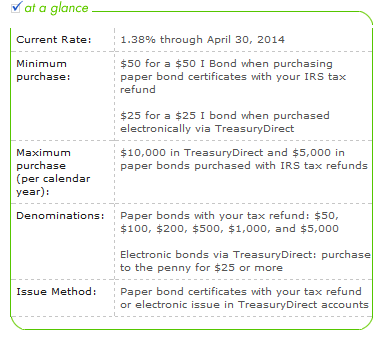
  • The fixed rate, currently 0.2% for as long as you hold the bond, up to 30 years – will never change. So if you bought an I Bond in 2013 with a zero fixed rate, it will continue to have a zero fixed rate. Purchases through April 30, 2014, will have a fixed rate of 0.20%. I Bonds I bought back in 2000 still carry a fixed rate of 3.4% and will continue to do so through 2030.
  • The inflation-adjusted rate changes each six months to reflect the running rate of inflation. That rate is currently set at 1.18% annualized. It will adjust again on May 1, 2014, for all I Bonds, no matter when they were purchased.

To understand how that inflation-adjusted rate is set, take a look at the last adjustment, on Nov. 1. To set the rate for November through April, the Treasury looks at the CPI-U inflation index from the end of March to the end of September. Here is the formula:

End of September 234.149 / End of March 232.773 = 1.0059, or .59%, the current six-month rate, which translates into an annual rate of 1.18%.

The Treasury uses the non-seasonally adjusted CPI-U, and that has been trending negative since the end of September.

End of Month Inflation index Monthly non- adjusted inflation
Sept. 2013 234.149 0.12%
Oct. 2013 233.546 -0.26%
Nov. 2013 233.069 -0.20%
Dec. 2013 233.049 -0.01%
Jan. 2014 233.916 0.37%
Feb. 2014 ?? ??
Mar. 2014 ?? ??

If the Treasury were setting the I Bond inflation-adjusted rate today, it would use this formula:

End of January 233.916 / End of September 234.149  = .999, or -0.1%.

Will the rate end up negative after the full six months? I would guess not, since higher heating fuel costs are likely to give February and March numbers a little boost. That is what happened in January with the .37% non-seasonally adjusted rate of inflation.

What happens if the rate goes negative?

An I Bond can never pay less than 0.0% interest and the accrued principal balance will never go down. (This is an advantage I Bonds have over TIPS in deflationary times. The principal balance of a TIPS does go down, but never below the original purchase.)

If the I Bond inflation-adjustment is set below zero, it is subtracted from the base fixed rate to determine the net interest of those six months. That number cannot go below zero.

For an I Bond purchased in 2014 and paying a base rate of 0.2%, an inflation-adjusted rate of -0.1% would result in a combined rate of 0.1% for six months. For I Bonds with a zero base rate, the combined rate would be 0.0% for six months.

The I Bond inflation-adjusted rate has gone negative only once, from May to November 2009, when it was set at a whopping -2.78%. During those six months, unless you bought your I Bonds before October 2001, you were earning zero interest.

Check out historical I Bond fixed rates and inflation-adjusted rates.

Should you dump I Bonds paying 0.0%?

If your strategy is to buy I Bonds up to the limit each year _ $10,000 per person at Treasury Direct and up to $5,000 in paper I Bonds as a tax refund – I would definitely urge you to ride out the six months at zero interest. Because of the purchase limits, you need to hold I Bonds until you need the cash.

Other folks who stay below the purchase limit could sell their I Bonds with a zero base rate and purchase again after Nov. 1, when the inflation-adjusted rate will be re-set, probably higher. The risk is whether the Treasury will continue the 0.2% base rate, which it set in November 2013 after three years at 0.0%.

Posted in I Bond, Inflation, Investing in TIPS | 6 Comments